
 China Sea Freight Transport Market | 2026-2036
China Sea Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
China Sea Freight Transport Market Outlook
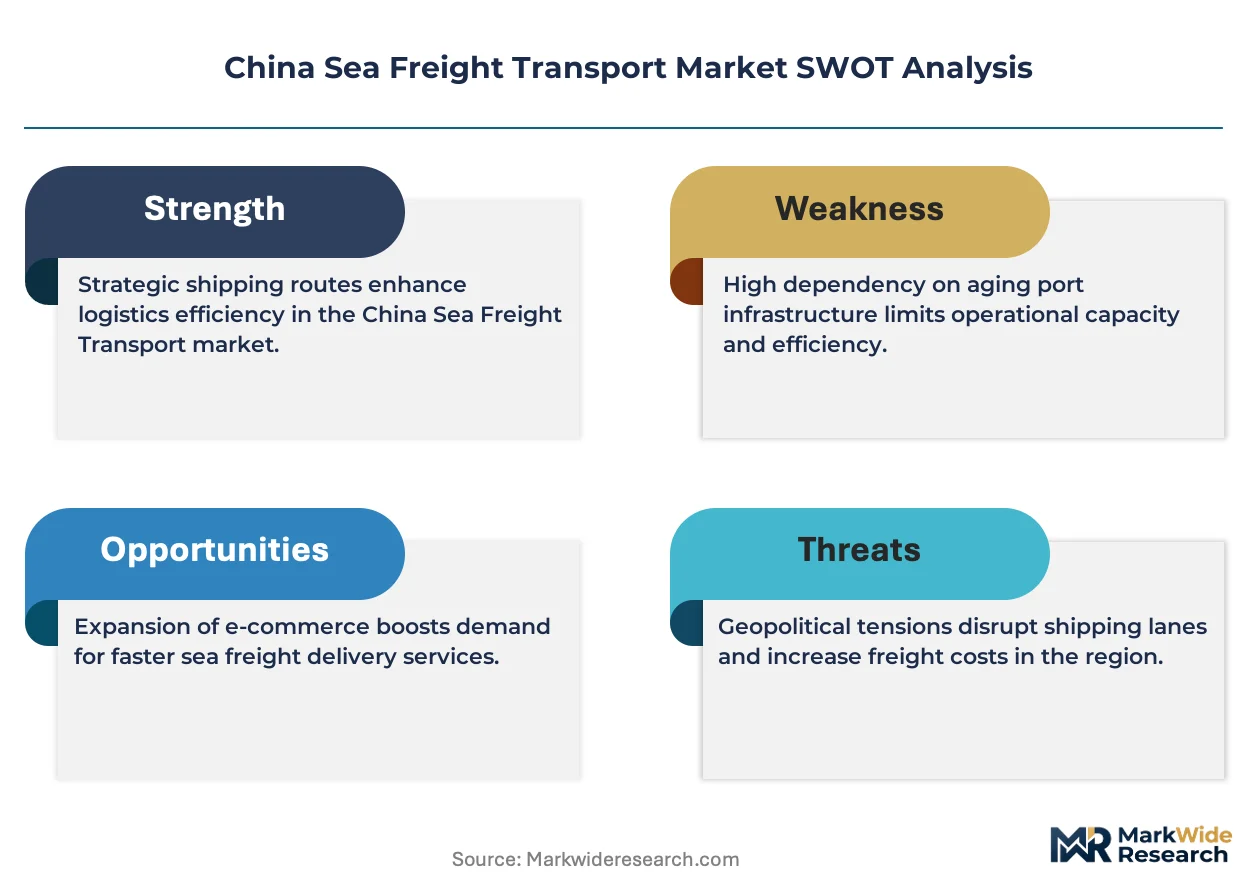
Freight forwarding as a software-defined service layer is hardening into the core revenue model for Chinese maritime operators. COSCO Shipping Lines leverages its state-backed fleet scale to dominate transpacific contract lanes. SINOTRANS Limited anchors its position through integrated customs brokerage and inland logistics control. China Merchants Group differentiates via port-terminal verticality across the Pearl and Yangtze deltas.
China sea freight transport encompasses the movement of containerized, bulk, and liquid cargo aboard ocean-going vessels operating from Chinese ports, with vessel capacities ranging from 2,000 TEU feeders to 24,000 TEU ultra-large container carriers engineered for mainline efficiency. Its primary purpose is to connect Chinese manufacturing and consumption centers with overseas trading partners through scheduled liner services and tramp charter operations. Container ships command the largest revenue pool among transport modes due to high-value cargo density and long-haul route premiums. Bulk carriers sustain steady tonnage demand from iron ore and coal imports through eastern port clusters. Intra-Asia routes within the shipping route dimension are expanding fastest as regional supply chain reconfiguration shifts assembly stages to Southeast Asian nodes.
MEE enforces dual carbon goals that mandate LNG and methanol-ready newbuilds entering Chinese-flagged fleets, tightening emissions compliance timelines for charterers and owners alike. SAMR monitors port service pricing under anti-monopoly frameworks, while GB standards govern container lashing and dangerous goods stowage protocols. China's national maritime regulator coordinates with port authorities in Shanghai, Shenzhen, and Qingdao to align berth allocation with green corridor pilot programs. Stakeholders must weigh fleet renewal capex against charter rate volatility and alternative fuel infrastructure gaps at key load centers.
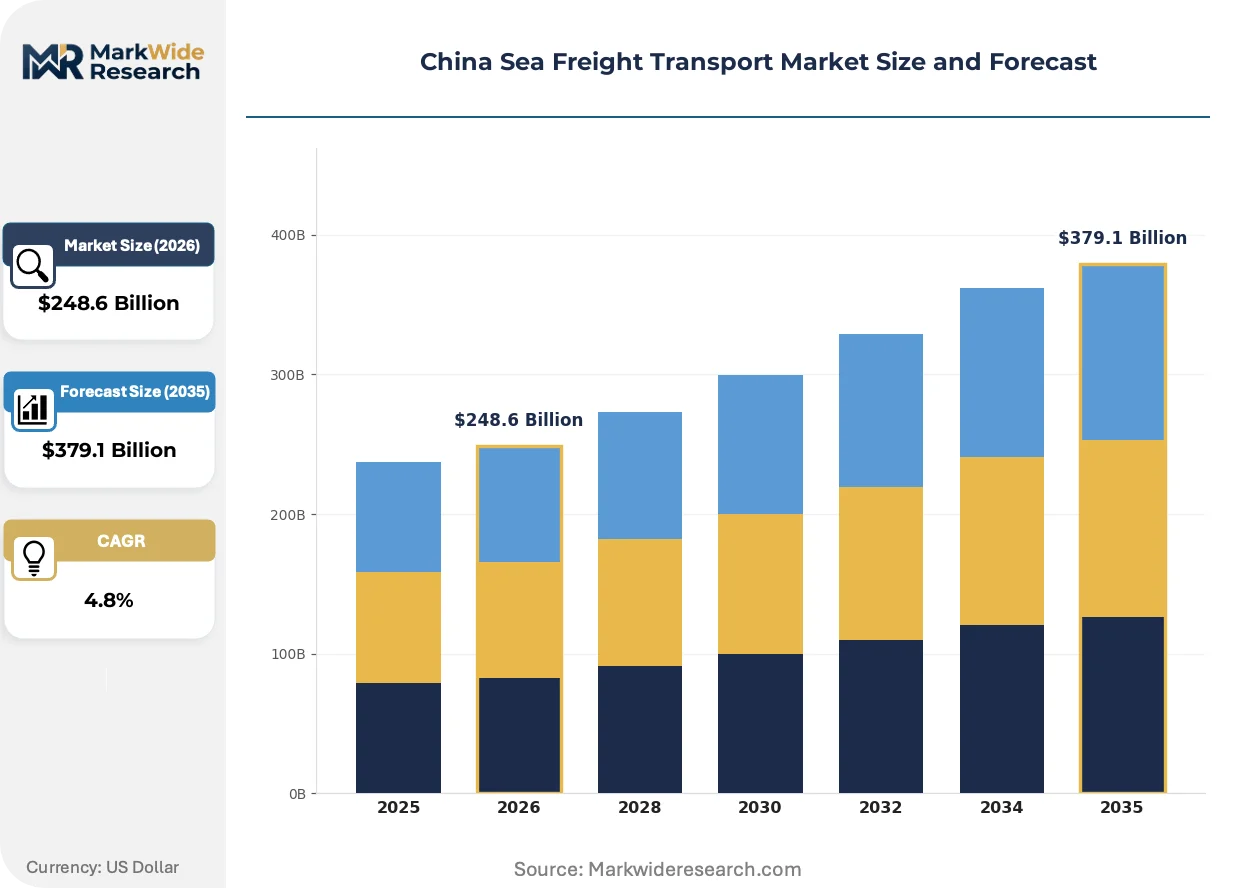
Market Dynamics
Dual carbon mandates from MEE are compressing fleet renewal timelines while LNG and methanol-ready newbuilds absorb capital that would otherwise expand capacity, creating a structural tension between compliance investment and volume growth.
Growth Catalysts
- MEE dual carbon enforcement:Binding emissions timelines accelerate scrappage of older tonnage and pull forward orders for alternative-fuel vessels, concentrating demand at yards with green certification.
- Electronics export surge:Semiconductor and consumer electronics manufacturers along the Yangtze River Delta are expanding dedicated maritime contracts to secure outbound capacity for high-value cargo.
- Intra-Asia supply chain reconfiguration:Assembly stage migration to Vietnam and Indonesia is generating new feeder demand from Ningbo-Zhoushan and Shenzhen to Southeast Asian load centers.
Market Restraints
- Alternative fuel infrastructure gaps:LNG bunkering remains concentrated at Shanghai and Yangshan, forcing vessels to deviate from optimal routing to refuel and eroding schedule reliability.
- Shipyard capacity concentration:Green-certified newbuild slots are monopolized by state-connected yards in Jiangsu and Zhejiang, extending delivery timelines for independent operators.
- Charter rate volatility:Spot market exposure for non-contracted tonnage creates margin compression when vessel supply temporarily exceeds lane demand.
Strategic Opportunities
- Green corridor pilot expansion:MEE-coordinated programs linking Shanghai with Los Angeles and Long Beach offer preferential berth access and accelerated customs clearance for compliant vessels.
- Inland waterway integration:Yangtze River feeder networks connecting Wuhan and Chongqing to deepwater ports remain underdeveloped, presenting first-mover advantages for barge-rail-sea intermodal operators.
- Digital freight platforms:Blockchain-enabled bill-of-lading systems are penetrating the spot charter market, displacing traditional broker intermediation with algorithmic matching.
Industry Challenges
- Marine engineer scarcity:Training pipelines for dual-fuel propulsion specialists lag fleet renewal schedules, forcing operators to poach talent at premium wages or defer vessel deployments.
- GB standards compliance complexity:Container lashing and dangerous goods stowage protocols are tightening faster than crew retraining cycles, elevating detention risk at Qingdao and Tianjin inspections.
- Legacy system integration:Terminal operating systems at older Pearl Delta ports lack API compatibility with new voyage optimization software, fragmenting data visibility across multi-port itineraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sea Freight Transport Market |
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $379.1 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Bulk Carriers, Container Ships, Tankers, Cargo Vessels End User: Manufacturers, Retailers, Importers, Exporters Service Type: Freight Forwarding, Customs Brokerage, Logistics Management, Cargo Handling Shipping Route: Transpacific, Asia-Europe, Intra-Asia, Coastal Shipping |
| Companies Covered | COSCO Shipping Lines, SINOTRANS Limited, China Merchants Group, SITC International Holdings Company Limited, Hebei Ocean Shipping (HOSCO), COSCO SHIPPING International, China Merchants Energy Shipping (CMES), China National Materials Storage and Transportation Corporation, CIMC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sea Freight Transport Market Strategic Shifts
Maritime logistics in China is digitizing at the contract layer, with software platforms compressing the traditional separation between vessel operations, customs clearance, and inland distribution into unified control systems.
Artificial intelligence voyage optimization is converging with real-time bunker price feeds to dynamically reroute vessels around congestion and fuel arbitrage opportunities. Container lines with integrated data science teams are adopting these tools fastest, compressing the competitive gap between asset-heavy operators and technology-enabled challengers. The structural consequence is a shift from fixed schedule adherence to profit-maximizing route elasticity.
SAMR anti-monopoly monitoring of port service pricing is forcing terminal operators to unbundle handling charges and publish transparent tariff structures. This regulatory pressure is eroding the historical cross-subsidy between captive port services and vessel operations at state-connected terminal groups. Smaller freight forwarders in the Yangtze Delta are responding by consolidating purchasing power to negotiate directly with independent stevedoring contractors.
Electronics manufacturers are consolidating outbound freight procurement under direct vessel charter contracts rather than traditional NVOCC intermediation. This buyer concentration is displacing the spot brokerage layer for high-value cargo lanes from Shanghai to Rotterdam and Los Angeles. The shift is most visible among semiconductor fabricators in Jiangsu province seeking supply chain control after pandemic-era capacity crunches.
China Sea Freight Transport Market Segmentation
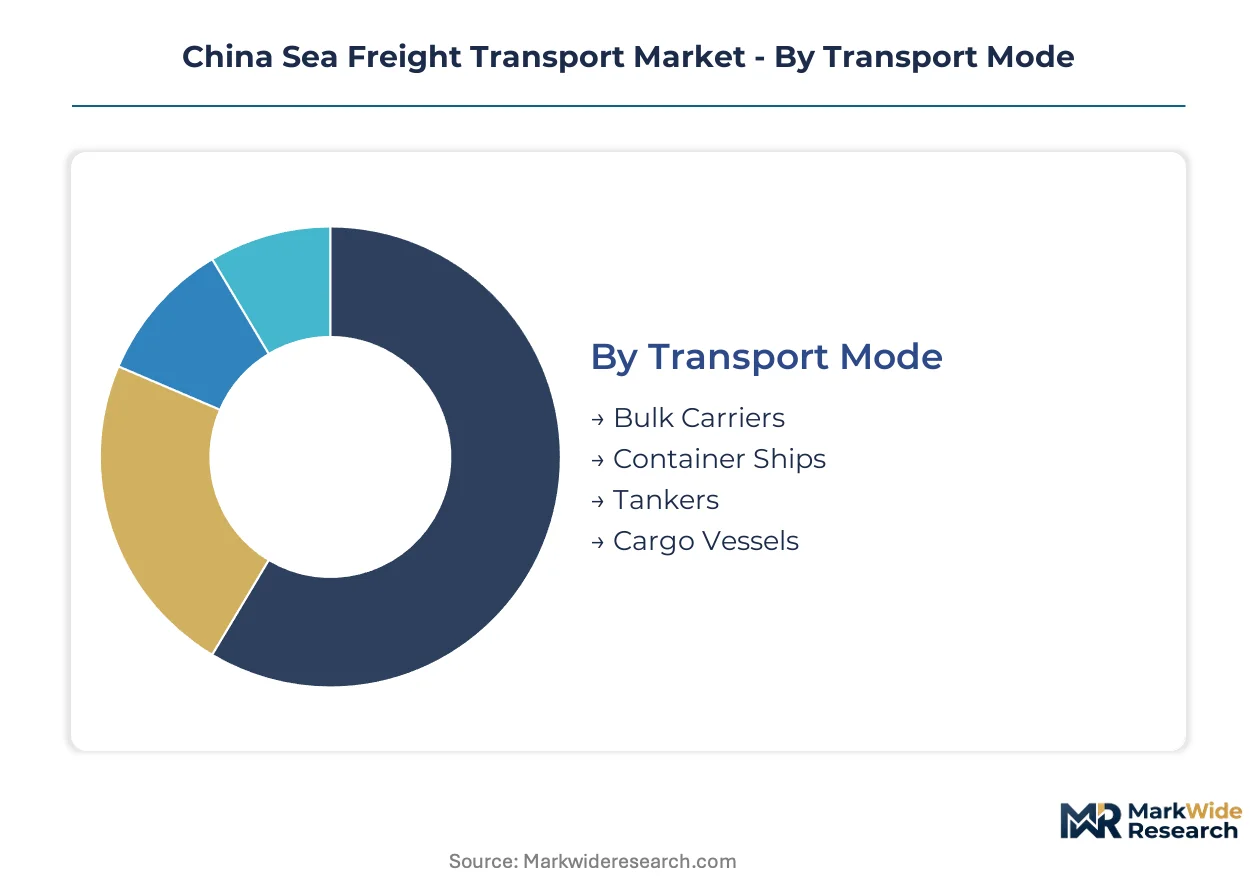
Segmentation in China's sea freight market reveals how cargo characteristics, customer scale, and route economics fragment operational requirements. Transport mode selection determines vessel deployment and fuel strategy. End-user concentration along the Yangtze River Delta corridor shapes service bundling decisions.
Transport Mode:
Container ships command premium revenue per ton-mile while bulk carriers anchor volume throughput at eastern port clusters.
- Container Ships:These vessels handle standardized intermodal containers ranging from 2,000 TEU feeders to 24,000 TEU ultra-large carriers. Electronics manufacturers in Jiangsu province are consolidating procurement under direct vessel charter contracts for Shanghai-Rotterdam and Shanghai-Los Angeles lanes, displacing traditional NVOCC intermediation after pandemic-era capacity crunches.
- Bulk Carriers:Designed for unpackaged commodity cargo including iron ore, coal, and grain with specialized holds and loading equipment. Steady tonnage demand flows through Ningbo-Zhoushan and Qingdao from steel mills and power generators, though MEE dual carbon mandates are compressing thermal coal import forecasts.
- Tankers:Segregated cargo systems transport crude oil, refined products, and chemicals with double-hull mandates under GB standards.
- Cargo Vessels:General breakbulk and project cargo carriers handle oversized manufacturing equipment and non-containerized goods.
Mature deployment sits with bulk carriers serving state-connected commodity traders. Newer deployment is concentrated in methanol-ready container vessels on green corridor pilot routes.
End User:
Procurement scale separates direct charter negotiators from freight-forwarding dependents.
- Manufacturers:Semiconductor fabricators and consumer electronics producers along the Yangtze River Delta are expanding dedicated maritime contracts to secure outbound capacity for high-value cargo, bypassing spot brokerage layers entirely.
- Exporters:Textile and furniture producers in Guangdong province rely on consolidated feeder services from Shenzhen to transshipment hubs, with SAMR anti-monopoly monitoring forcing terminal operators to unbundle handling charges and publish transparent tariff structures.
- Retailers:Omnichannel distribution networks require synchronized inbound inventory flows with seasonal demand spikes.
- Importers:Commodity traders and industrial processors manage raw material supply security through long-term COA arrangements.
Direct charter concentration is deepest among manufacturers. Retailer adoption of integrated logistics management is climbing the fastest.
Service Type:
Software-defined service layers are compressing traditional operational boundaries into unified control systems.
- Freight Forwarding:Digital platforms are penetrating the spot charter market with blockchain-enabled bill-of-lading systems, displacing traditional broker intermediation with algorithmic matching between vessel operators and cargo owners.
- Customs Brokerage:Integrated clearance services anchor SINOTRANS Limited's market position through control of documentation flows and inspection coordination at Shanghai, Shenzhen, and Qingdao ports.
- Logistics Management:End-to-end supply chain orchestration combining ocean freight with inland distribution and warehouse positioning.
- Cargo Handling:Stevedoring and terminal operations governed by GB standards for container lashing and dangerous goods stowage protocols.
Legacy dominance rests with customs brokerage at state-connected port groups. Freight forwarding digitization is gaining share fastest among independent operators.
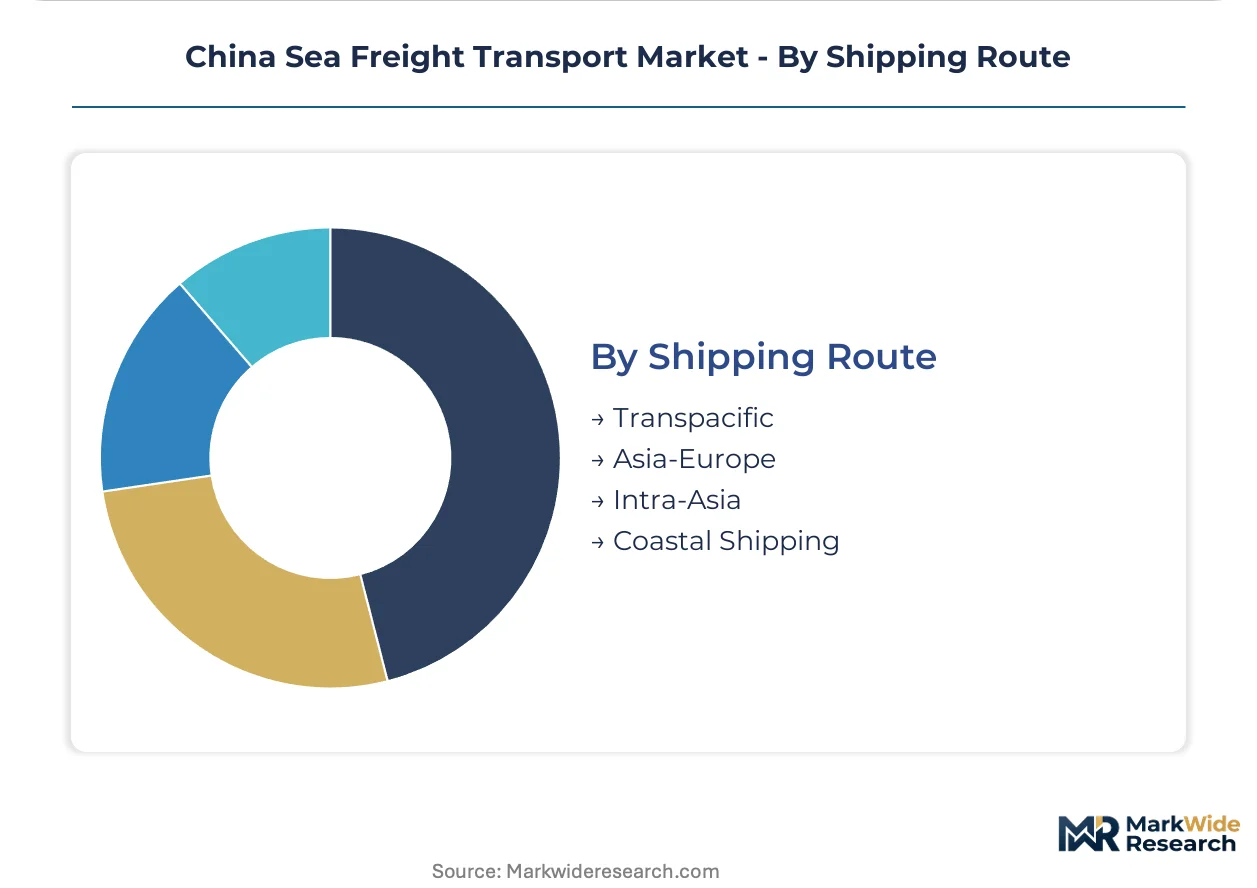
Shipping Route:
Route selection determines fuel infrastructure access and green corridor eligibility under MEE coordination.
- Intra-Asia:Feeder networks connecting Ningbo-Zhoushan and Shenzhen to Vietnam and Indonesia are expanding most quickly as regional supply chain reconfiguration shifts assembly stages to Southeast Asian nodes, generating new demand for 2,000-4,000 TEU vessels.
- Transpacific:Mainline services to Los Angeles and Long Beach command the highest contract premiums, with MEE-coordinated green corridor pilots offering preferential berth access and accelerated customs clearance for LNG and methanol-ready vessels.
- Asia-Europe:Suez-dependent routing faces carbon intensity scrutiny under EU carbon border adjustment mechanisms.
- Coastal Shipping:Domestic cabotage services connecting northern and southern China face competition from rail and road alternatives.
Established volume concentrates on transpacific headhaul lanes. Intra-Asia feeder expansion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters generate outbound container volumes that far exceed domestic consumption capacity, creating structural dependence on deepwater port access. This production-consumption asymmetry concentrates investment along coastal corridors serving export-oriented industrial zones.
Yangtze River Delta
Semiconductor fabricators in Jiangsu province are consolidating freight procurement under direct vessel charter contracts. MEE dual carbon mandates accelerate scrappage of older tonnage at Shanghai and Ningbo-Zhoushan anchor ports. Green corridor pilot programs linking Shanghai with Los Angeles offer preferential berth access for LNG-ready vessels.
Pearl River Delta
Electronics assembly plants in Shenzhen and Dongguan generate feeder demand to Southeast Asian transshipment hubs. SAMR anti-monopoly monitoring forces terminal operators to unbundle handling charges and publish transparent tariff structures. China Merchants Group controls vertical port-terminal integration across Shenzhen and Hong Kong gateway facilities.
Beijing-Tianjin-Hebei
Steel mills and coal-fired power generators sustain bulk carrier throughput at Tianjin and Caofeidian ports. GB standards govern container lashing and dangerous goods stowage protocols with tightening inspection cycles. Tianjin Port Group is retrofitting berths for methanol bunkering infrastructure to serve alternative-fuel newbuilds.
Shandong Peninsula
Petrochemical refineries at Qingdao generate tanker demand for crude oil and refined product movements. The national maritime regulator coordinates berth allocation with green corridor pilot programs at Qingdao container terminals. Independent freight forwarders are consolidating purchasing power to negotiate directly with stevedoring contractors.
Sichuan-Chongqing
Inland manufacturing centers in Chongqing rely on Yangtze River feeder networks connecting to Shanghai deepwater facilities. Yangtze River barge-rail-sea intermodal corridors remain underdeveloped, presenting first-mover advantages for integrated logistics operators. Chongqing-Xinjiang-Europe rail-sea intermodal services compete with pure maritime routing for European-bound cargo.
China Sea Freight Transport Market Competitive Environment
Capital-heavy fleet operators compete with asset-light freight forwarding platforms for control of contract margins. State-backed shipping lines dominate transpacific headhaul lanes through scale advantages in vessel deployment. Three archetypes define competitive positioning: integrated port-terminal operators, pure-play container lines, and digital freight platforms. Consolidation pressure favors M&A between terminal operators and inland logistics providers, while technology partnerships link vessel operators with voyage optimization software vendors.
Among state-connected maritime conglomerates, COSCO Shipping Lines, SINOTRANS Limited, and China Merchants Group occupy anchor positions across different value chain segments. COSCO Shipping Lines exemplifies the fleet-scale archetype with dominance in transpacific contract lanes. SINOTRANS Limited represents the integrated service model through customs brokerage and inland logistics control. China Merchants Group anchors the port-terminal verticality archetype across the Pearl and Yangtze deltas.
| Leading Market Players |
|---|
| COSCO Shipping Lines |
| SINOTRANS Limited |
| China Merchants Group |
| SITC International Holdings Company Limited |
| Hebei Ocean Shipping (HOSCO) |
| COSCO SHIPPING International |
| China Merchants Energy Shipping (CMES) |
| China National Materials Storage and Transportation Corporation |
| CIMC |
| Others |
Value Chain & Pricing Dynamics
Marine engineer scarcity in Jiangsu and Zhejiang provinces widens labor-cost spreads between state-connected yards and independent operators, compressing margins on standard-class tonnage while premium LNG-ready newbuilds sustain rate premiums through certified yard queues.
Pricing Analysis
Cost-down pressure on standard-class feeder vessels accelerates because green-certified newbuild slots at Jiangsu and Zhejiang yards monopolize capacity, forcing independent operators into extended delivery timelines or premium charter rates. Three-tier pricing structure across premium LNG-methanol ready, standard compliant-class, and legacy economy tonnage reflects certification grade and fuel infrastructure access. Spot market exposure for non-contracted capacity intensifies price sensitivity among smaller freight forwarders, while electronics manufacturers with direct charter contracts exhibit lowest price elasticity due to supply chain control priorities.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu and Zhejiang green-certified shipyards for alternative-fuel newbuilds, concentrating hull fabrication and engine integration capacity under state-connected operators. Steel plate and dual-fuel propulsion systems draw from China, South Korea, and Japan, with LNG bunkering infrastructure anchored at Shanghai and Yangshan creating logistics chokepoints for vessels on non-optimal routing. Distribution runs through Ningbo-Zhoushan and Shenzhen transshipment hubs to Southeast Asian load centers, with feeder networks extending to Vietnam and Indonesia assembly nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China sea freight transport is consolidating around fleet-scale advantages and green corridor access, with MEE dual carbon timelines forcing sub-scale operators into acquisition targets or exit.
For Market Incumbents: To counter charter rate volatility and independent digital freight platforms, COSCO Shipping Lines and state-connected operators should deepen backward integration into methanol bunkering infrastructure at Tianjin and Qingdao while securing long-term COA arrangements with Yangtze River Delta electronics manufacturers to lock headhaul capacity commitments. For New Entrants and Emerging Players: Digital freight platforms with blockchain-enabled bill-of-lading capabilities represent the most penetrable wedge, targeting spot charter market fragmentation among independent operators in the Yangtze River feeder segment and offering algorithmic matching to displace traditional broker intermediation. For Investors and Strategic Acquirers: Re-rating potential sits with port-terminal verticality plays given MEE-coordinated green corridor expansion and preferential berth access monetization, with China Merchants Group's Pearl and Yangtze delta positioning offering template value. Long-term viability hinges on LNG-methanol fuel transition completion; watch methanol bunkering infrastructure deployment at Caofeidian and Qingdao as inflection signal for compliant fleet competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative-Fuel Fleet Renewal | MEE dual carbon mandates accelerate scrappage of older tonnage and pull forward LNG-methanol newbuild orders at green-certified yards. |
| Green Corridor Pilot Expansion | Preferential berth access at Shanghai and Los Angeles accelerates customs clearance for compliant vessels on transpacific headhaul lanes. |
| Digital Freight Platform Deployment | Blockchain-enabled bill-of-lading systems displace traditional broker intermediation with algorithmic matching in spot charter markets. |
| Inland Waterway Integration | Yangtze River barge-rail-sea intermodal corridors connecting Wuhan and Chongqing remain underdeveloped with first-mover advantages available. |
| Port-Terminal Verticality Consolidation | SAMR anti-monopoly monitoring forces tariff transparency and erodes cross-subsidies, favoring integrated operators with captive stevedoring control. |
Study Parameters
Multi-period observation of vessel deployment patterns, charter rate indices, and green corridor pilot participation anchored the trend analysis, supplemented by interviews with fleet operations directors, port authority planning officers, customs brokerage leads, and LNG bunkering infrastructure developers. Secondary validation drew from MEE emissions compliance filings, SAMR port service pricing disclosures, China Port Association throughput statistics, and vessel registration databases. Bottom-up capacity modeling and top-down trade flow analysis were triangulated against manufacturer procurement survey data.
Input-output matrices mapped transport mode, end-user scale, service type, and shipping route dimensions across the projection horizon, with CAGRs derived from fleet renewal schedules and carbon compliance trajectory modeling. Container ship deployment, bulk carrier tonnage flows, and intra-Asia feeder expansion were modeled separately with fuel transition pathways and alternative-fuel infrastructure buildout curves as primary forecast inputs.
Caveats apply where MEE enforcement intensity, shipyard capacity allocation shifts, or LNG-methanol price spreads could materially shift the outlook for fleet economics and charter rate trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive & Transportation
Marine Propeller Market
Automotive & Transportation
Europe Automotive Smart Keys Market
Automotive & Transportation
Vehicles for Disabled Market
Automotive & Transportation
Automotive Display Units Market
Automotive & Transportation
Marine Interiors Market
Automotive & Transportation
Global Automotive Fog Lights Market
Automotive & Transportation
Automated Guided Cart Market
Automotive & Transportation
Autonomous Underwater Vehicle (AUV) Market
Automotive & Transportation
Adaptive Front Lighting Market
Automotive & Transportation
Bicycle Rim Market
Automotive & Transportation
Automotive Flex Fuel Engine Market
Automotive & Transportation
Intelligent Traffic Management Market
Automotive & Transportation
Global Electric Vehicles Market
Automotive & Transportation
China Automotive Adaptive Lighting System Market
Automotive & Transportation
Global Port Logistics Market
Automotive & Transportation
Wheel Loaders Market