
 China Home Mortgage Finance Market | 2026-2036
China Home Mortgage Finance Market Size, Share, and Industry Trends Forecast 2026-2036
China Home Mortgage Finance Market Outlook
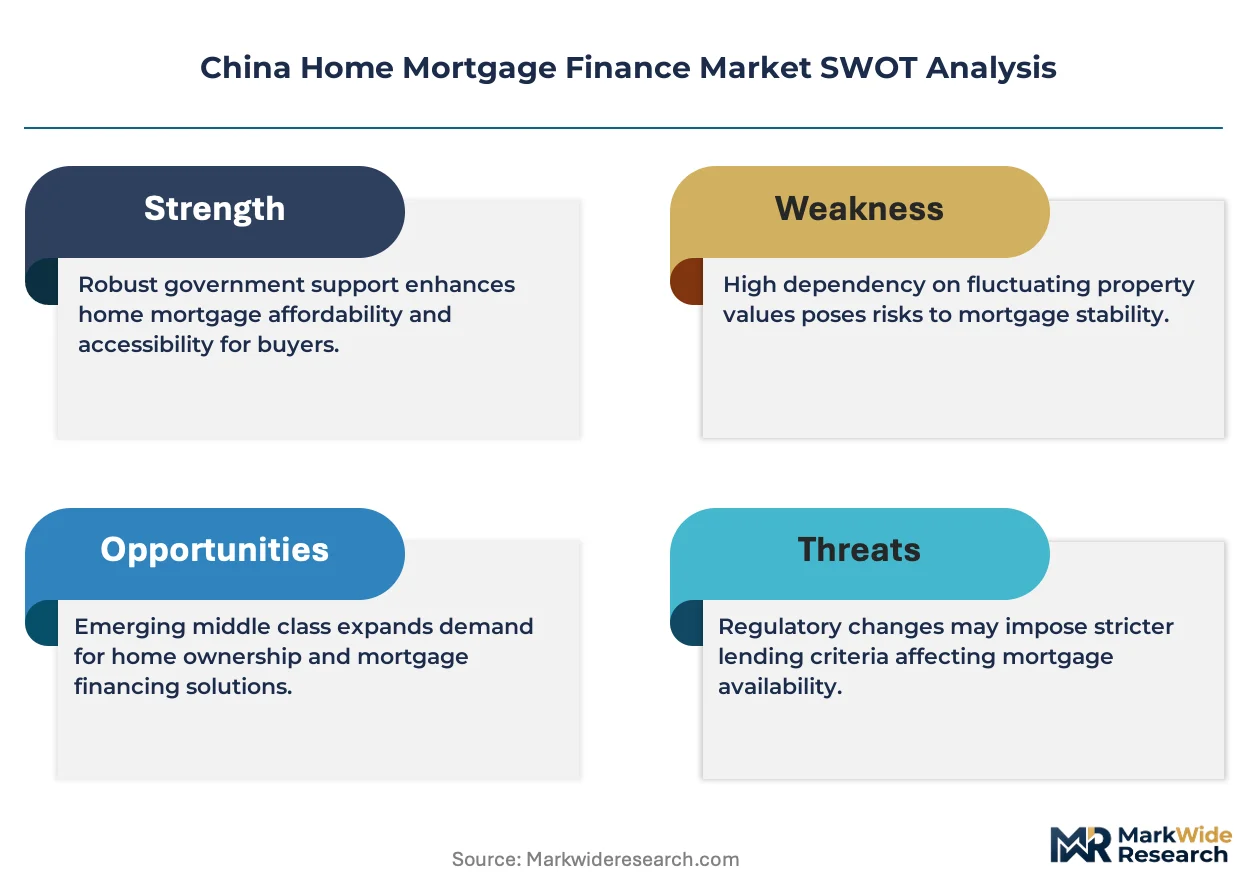
China's dual carbon goals are recalibrating mortgage eligibility criteria for green-certified residential developments, pushing lenders to embed energy performance benchmarks into underwriting protocols. Industrial and Commercial Bank of China leverages its state-backed balance sheet to dominate infrastructure-linked housing finance across provincial capital cities. China Construction Bank anchors its mortgage portfolio in affordable housing quotas mandated by municipal governments. Agricultural Bank of China specializes in rural-urban fringe lending where township property rights conversions create collateral complexity.
China Home Mortgage Finance encompasses secured lending instruments collateralized by residential real property, where loan-to-value ratios typically range from sixty to eighty percent and tenors extend from ten to thirty years, serving the primary purpose of enabling household property acquisition while generating interest income for depository institutions. Fixed rate mortgages occupy the largest share of outstanding balances as borrowers seek payment certainty amid policy rate volatility, while interest-only structures are gaining traction among investor borrowers in coastal provinces seeking cash flow optimization. First-time buyers represent the fastest-growing borrower segment as hukou reform expands urban residency access for migrant households.
The People's Bank of China sets benchmark loan prime rates that directly filter into mortgage pricing, while the China Banking and Insurance Regulatory Commission enforces capital adequacy buffers and concentration limits on property exposure. Local housing bureaus in Beijing, Shenzhen, and Chengdu implement purchase restriction policies that toggle demand eligibility by household registration status and ownership history. Stakeholders must monitor how municipal property tax pilots and common prosperity wealth redistribution frameworks reshape collateral valuation methodologies and borrower qualification thresholds.
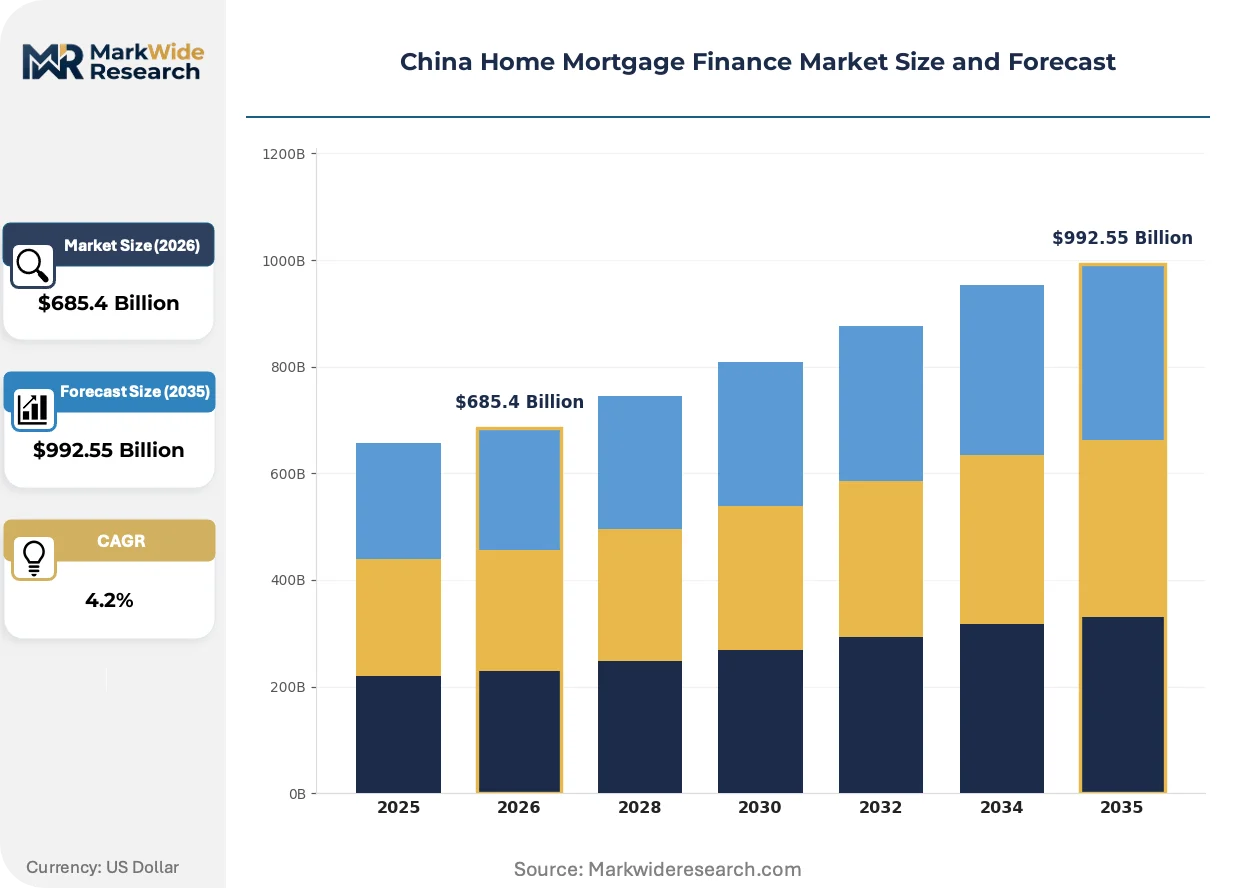
Market Dynamics
China's dual carbon goals are compressing mortgage origination timelines as lenders race to embed energy performance benchmarks into underwriting protocols before municipal green building mandates take full effect.
Growth Catalysts
- Hukou reform acceleration:Provincial residency relaxation in tier-two cities is unlocking mortgage eligibility for migrant households previously excluded from formal lending channels.
- Green mortgage-linked incentives:The People's Bank of China's differentiated loan prime rate pricing rewards energy-efficient housing with preferential borrowing costs.
- Yangtze River Delta clustering:Shanghai-Nanjing-Hangzhou metropolitan integration is concentrating household formation and property demand in this corridor.
Market Restraints
- Collateral valuation opacity:Township property rights conversions in rural-urban fringe zones create title uncertainty that depresses loan-to-value ratios.
- Developer concentration risk:Exposure to distressed property developers in third-tier cities is forcing lenders to provision against contingent liabilities.
- Interest rate volatility:Benchmark loan prime rate adjustments transmit directly into mortgage servicing costs, compressing borrower debt capacity.
Strategic Opportunities
- Rental-to-ownership conversion:Long-term rental platform data is creating alternative credit scoring pathways for first-time buyers without traditional income documentation.
- Cross-provincial mortgage portability:Hukou transfer simplification between Yangtze River Delta municipalities enables loan product standardization across jurisdictional boundaries.
- Digital collateral registries:Blockchain-based title verification in Shenzhen and Chengdu is compressing due diligence cycles for secondary market transactions.
Industry Challenges
- Green certification talent scarcity:Shortage of assessors qualified under evolving GB standards for residential energy performance is bottlenecking loan approval velocity.
- Legacy core system integration:State-owned banks are struggling to retrofit decades-old loan origination platforms with real-time carbon intensity data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Home Mortgage Finance Market |
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $992.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Rate Mortgages, Adjustable Rate Mortgages, Interest-Only Mortgages, Reverse Mortgages Borrower Type: First-Time Buyers, Move-Up Buyers, Investors, Refinancers Loan Purpose: Purchase, Refinance, Debt Consolidation, Home Equity Line of Credit Payment Structure: Principal and Interest, Interest-Only, Balloons, Graduated |
| Companies Covered | Bank of China, Postal Savings Bank of China, Industrial and Commercial Bank of China, China Merchants Bank, HSBC, China Construction Bank, Bank of Communications, China CITIC Bank, Agricultural Bank of China, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Home Mortgage Finance Market Strategic Shifts
Digitization of mortgage underwriting is compressing approval timelines while embedding environmental risk assessment directly into credit decisioning workflows.
Artificial intelligence-driven property valuation models are unifying disparate data streams including satellite imagery, transaction records, and energy consumption patterns. Commercial lenders in Shanghai and Hangzhou are deploying these tools for secondary market appraisals. This capability is unifying previously siloed underwriting functions into integrated credit risk platforms.
China's dual carbon goals are recalibrating mortgage eligibility criteria through tiered interest rate subsidies for green-certified residential developments. Lenders must now verify building energy performance ratings before finalizing loan terms. First-time buyer segments in tier-two cities face the steepest documentation requirements under these protocols.
Households are migrating from branch-based mortgage applications to fully digital origination channels supported by facial recognition identity verification and electronic contract execution. This channel shift is displacing traditional broker intermediaries in coastal provinces. The Yangtze River Delta metropolitan corridor shows the highest digital adoption intensity among all Chinese regions.
China Home Mortgage Finance Market Segmentation
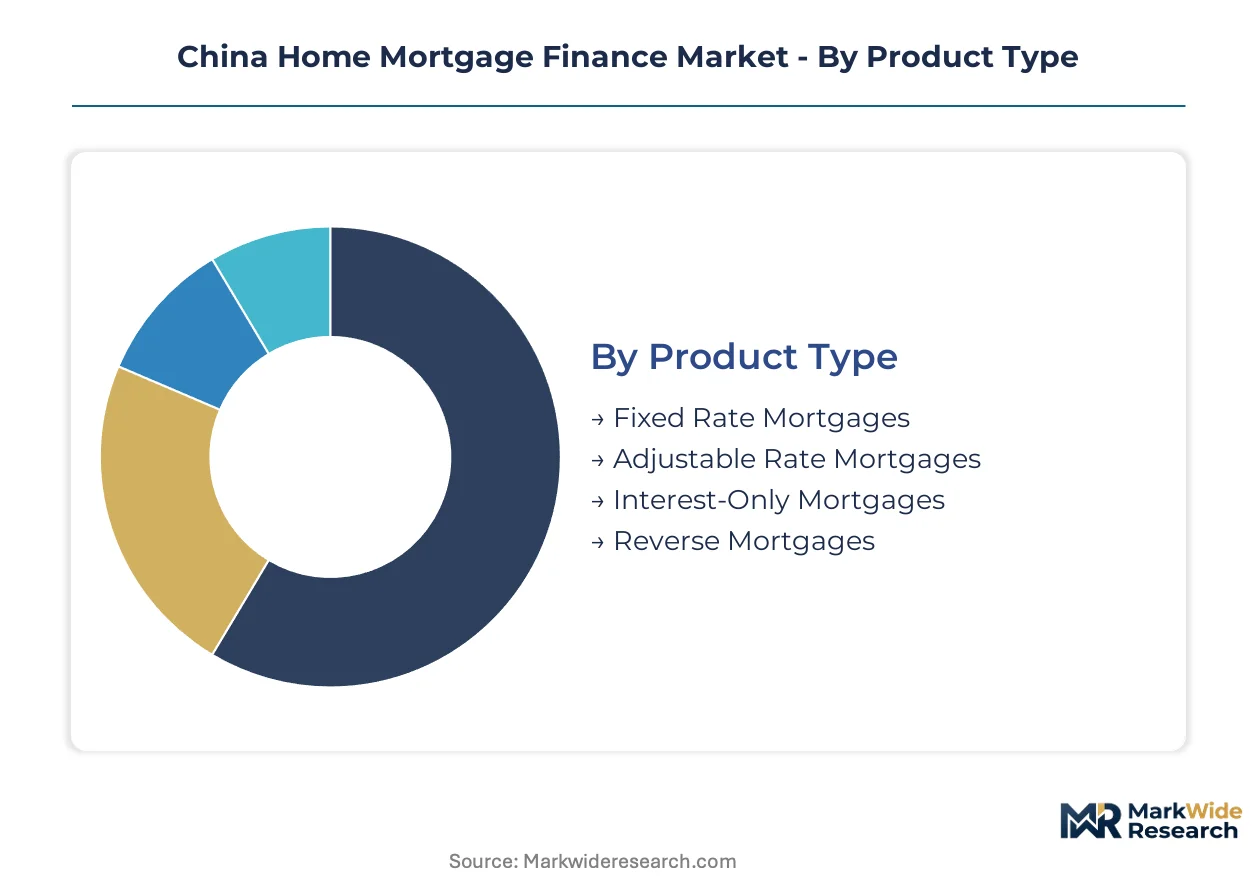
China's mortgage market segments reveal divergent capital deployment patterns as lenders balance payment certainty against interest rate risk exposure. Product differentiation intensifies along the Yangtze River Delta corridor where digital origination platforms enable precise borrower matching.
Product Type:
Capital intensity varies sharply across mortgage structures, with fixed-rate instruments demanding the heaviest balance sheet reserves to hedge against benchmark loan prime rate volatility.
- Fixed Rate Mortgages:Lock borrowing costs at origination, transferring interest rate risk entirely to lenders. Industrial and Commercial Bank of China anchors its portfolio here to attract risk-averse households in Shanghai and Nanjing.
- Adjustable Rate Mortgages:Reset periodically against the People's Bank of China's loan prime rate, compressing lender hedging costs. These instruments concentrate among move-up buyers in Hangzhou seeking lower initial payments.
- Interest-Only Mortgages:Coastal province investors favor these structures for cash flow optimization.
- Reverse Mortgages:Emerging products collateralized by existing home equity for elderly homeowners.
Fixed Rate Mortgages absorb the bulk of installed capacity; Interest-Only Mortgages are expanding most quickly.
Borrower Type:
Customer acquisition costs stratify sharply, with first-time buyers requiring extensive documentation support while refinancers trigger minimal incremental origination expense.
- First-Time Buyers:Hukou reform beneficiaries in tier-two cities dominate this segment. Municipal affordable housing quotas in Chengdu and Xi'an channel subsidized credit toward these households.
- Move-Up Buyers:Existing homeowners trading into larger properties. These borrowers concentrate in the Yangtze River Delta where household formation rates exceed national averages.
- Investors:Coastal province purchasers seeking rental income streams.
- Refinancers:Existing borrowers repricing loans during benchmark rate adjustment windows.
First-Time Buyers command the largest origination volume; Investors show the steepest expansion trajectory.
Loan Purpose:
Risk-weighted capital requirements diverge substantially, with purchase mortgages demanding full property appraisal protocols while home equity lines leverage existing collateral valuations.
- Purchase:Primary market acquisitions collateralized by newly constructed residential property. China Construction Bank specializes here through municipal affordable housing partnerships.
- Refinance:Existing loan repricing or term restructuring. Agricultural Bank of China targets rural-urban fringe borrowers seeking payment relief.
- Debt Consolidation:Multi-liability restructuring into single mortgage obligations.
- Home Equity Line of Credit:Revolving facilities secured by accumulated property equity.
Purchase mortgages anchor lender balance sheets; Home Equity Line of Credit products are gaining share fastest.
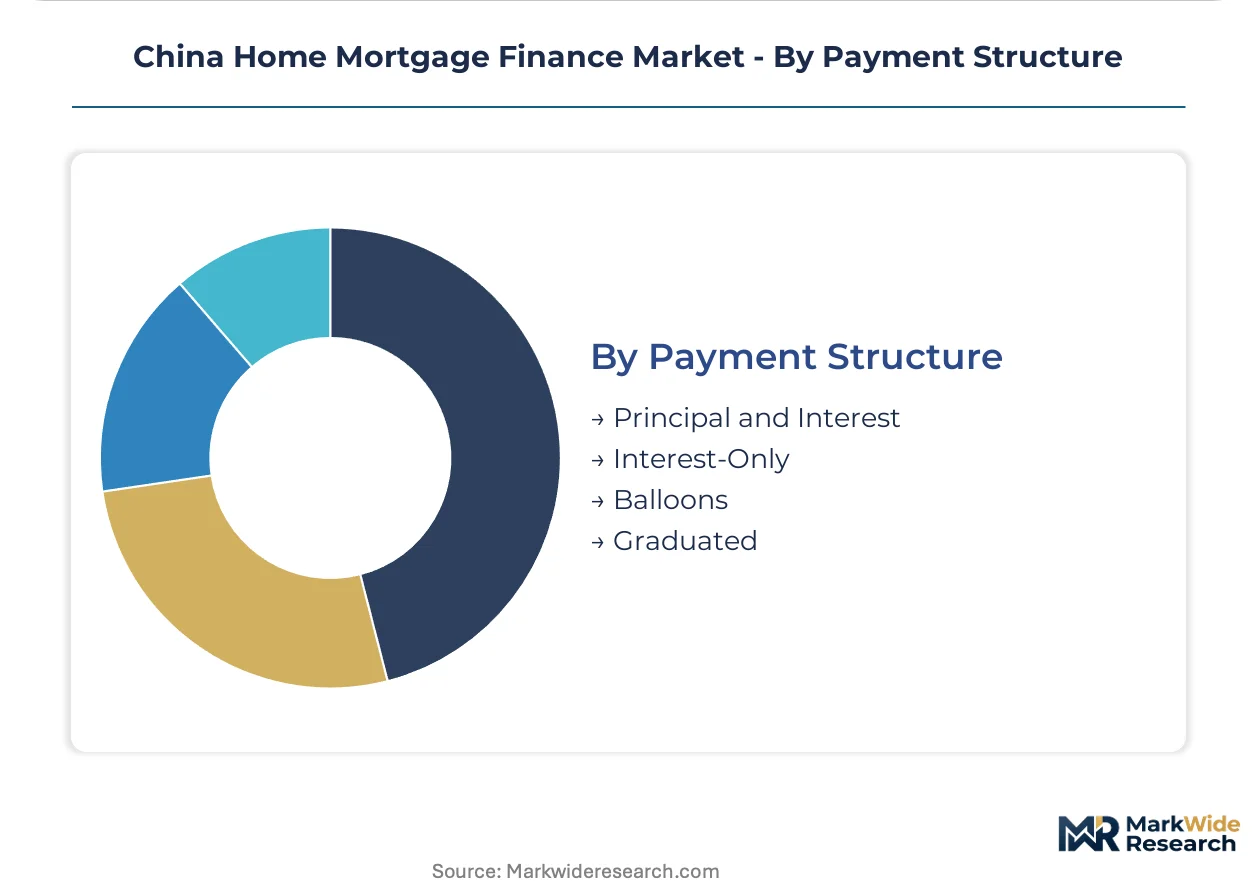
Payment Structure:
Amortization mechanics determine servicing complexity, with graduated structures requiring dynamic payment recalculation systems that strain legacy core banking platforms.
- Principal and Interest:Standard amortization schedules reducing outstanding balance over loan tenor. This structure dominates state-owned bank portfolios serving salaried employees.
- Interest-Only:Deferred principal repayment maximizing short-term affordability. Shenzhen and Hangzhou investors favor these terms for speculative acquisitions.
- Balloons:Large terminal payments requiring refinancing or liquidation.
- Graduated:Payment schedules escalating over time to match anticipated income growth.
Principal and Interest structures hold the majority of outstanding balances; Interest-Only arrangements are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's mortgage finance market displays stark regional asymmetry between origination demand in eastern coastal metros and collateral complexity in interior provinces. Consumption concentrates in wealthier municipalities while underwriting capacity stretches to accommodate rural-urban fringe conversions.
Yangtze River Delta
Shanghai, Hangzhou, and Nanjing anchor the nation's highest mortgage origination volumes as household formation accelerates metropolitan integration. The People's Bank of China's differentiated loan prime rate pricing rewards energy-efficient housing developments across this corridor with preferential borrowing costs. Digital collateral registries in Shanghai compress due diligence cycles for secondary market transactions.
Pearl River Delta
Shenzhen and Guangzhou generate intense demand from technology sector employees seeking primary market acquisitions. Local housing bureaus implement purchase restriction policies that toggle demand eligibility by household registration status and ownership history. Blockchain-based title verification pilots in Shenzhen reduce collateral valuation opacity for cross-border investors.
Beijing-Tianjin-Hebei
The capital region enforces stringent affordable housing quotas that channel subsidized credit toward first-time buyers. Municipal property tax pilots reshape collateral valuation methodologies in Beijing's peripheral districts. Industrial and Commercial Bank of China leverages its state-backed balance sheet to dominate infrastructure-linked housing finance across provincial capital nodes.
Sichuan-Chongqing
Chengdu's municipal affordable housing partnerships expand mortgage eligibility for hukou reform beneficiaries. The China Banking and Insurance Regulatory Commission enforces capital adequacy buffers that limit property exposure concentration in third-tier city developments. Agricultural Bank of China specializes in rural-urban fringe lending where township property rights conversions create collateral complexity.
Shandong Peninsula
Qingdao and Jinan exhibit rising origination volumes from move-up buyers trading into larger properties. Green building finance standards recalibrate mortgage-linked incentives for energy-efficient housing across coastal prefectures. Interest-only structures gain traction among investor borrowers seeking cash flow optimization in port city rental markets.
China Home Mortgage Finance Market Competitive Environment
The competitive structure tilts toward state-backed depository institutions with balance sheet scale to absorb long-duration fixed-rate assets. Four strategic archetypes dominate: universal commercial banks with municipal infrastructure partnerships, policy banks executing affordable housing mandates, joint-stock commercial banks targeting affluent coastal borrowers, and foreign banks serving cross-border clientele. Competitive moves concentrate on digital origination platform deployment and green mortgage product differentiation.
Among state-owned commercial banks, Industrial and Commercial Bank of China, China Construction Bank, and Agricultural Bank of China occupy positions reflecting distinct geographic and segment specializations. Industrial and Commercial Bank of China anchors the universal bank archetype through provincial capital penetration. China Construction Bank exemplifies the policy-execution model via municipal affordable housing quotas. Agricultural Bank of China represents rural-urban fringe expertise where collateral complexity demands specialized underwriting protocols.
| Leading Market Players |
|---|
| Bank of China |
| Postal Savings Bank of China |
| Industrial and Commercial Bank of China |
| China Merchants Bank |
| HSBC |
| China Construction Bank |
| Bank of Communications |
| China CITIC Bank |
| Agricultural Bank of China |
| Others |
Value Chain & Pricing Dynamics
State-backed depository institutions with sovereign balance sheet capacity anchor mortgage supply chains across China's provincial banking networks, compressing origination margins through scale-driven pricing discipline while channeling credit toward policy-mandated housing segments.
Pricing Analysis
Margin tightening in fixed-rate mortgage tiers reflects the People's Bank of China's benchmark loan prime rate volatility, which forces lenders to absorb hedging costs or transfer them through wider spreads. Pricing stratifies across premium green-certified developments, standard urban residential, and economy-tier affordable housing quotas based on energy performance ratings and municipal subsidy eligibility. Cost-down pressure on adjustable-rate products accelerates as first-time buyers in tier-two cities demonstrate heightened price sensitivity, while coastal province investors in interest-only structures show minimal elasticity.
Supply Chain Analysis
Refurbishment and secondary market transaction flows are digitizing through blockchain-based title verification pilots in Shenzhen and Chengdu, compressing due diligence cycles for mortgage collateral assessment. Geographic supply concentration centers on Shanghai, Hangzhou, and Nanjing in the Yangtze River Delta, with Beijing-Tianjin-Hebei and Pearl River Delta serving secondary origination hubs. Raw material dependencies include residential construction steel, cement, and copper wiring feeds from domestic smelters. Supply chain risk hinges on developer concentration exposure in third-tier cities where distressed property inventories depress collateral valuations. Distribution runs through state-owned bank branch networks and emerging digital origination platforms displacing traditional broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around state-backed institutions with balance sheet depth to absorb long-duration fixed-rate assets, as interest rate volatility and green certification mandates force smaller regional lenders toward exit or acquisition.
For Market Incumbents: Deepen vertical integration into digital collateral registries by acquiring or partnering with blockchain title verification platforms in Shenzhen and Chengdu, reducing due diligence costs that currently compress net interest margins. Expand green mortgage product specialization ahead of municipal dual carbon mandate deadlines, leveraging existing municipal infrastructure relationships to lock in preferential loan prime rate pricing from the People's Bank of China. For New Entrants and Emerging Players: The mid-market pricing gap between premium green-certified developments and economy-tier affordable housing quotas offers white-space entry through specialized underwriting for energy-efficient retrofit financing in tier-two cities. Target rural-urban fringe zones where Agricultural Bank of China's collateral complexity constraints create service gaps, deploying alternative credit scoring through rental platform data for first-time buyers lacking traditional income documentation. For Investors and Strategic Acquirers: Municipal property tax pilot expansion in Beijing's peripheral districts is the leading indicator that collateral valuation methodologies will shift toward income-based approaches, favoring lenders with advanced property assessment capabilities. Position for five-to-ten year consolidation plays by targeting joint-stock commercial banks with affluent coastal borrower bases but limited green certification infrastructure. Monitor hukou reform acceleration signals in provincial capitals as early indicators of origination volume inflection in tier-two city mortgage markets.| Strategic Initiative | Industry Significance |
|---|---|
| Green Mortgage Product Launch | Aligns lending portfolios with People's Bank of China differentiated loan prime rate incentives for energy-efficient housing. |
| Digital Collateral Registry Integration | Compresses secondary market transaction cycles through blockchain title verification in Shenzhen and Chengdu municipal pilots. |
| Municipal Affordable Housing Partnership | Locks in subsidized credit quotas mandated by Chengdu and Xi'an housing bureaus for first-time buyer segments. |
| Cross-Provincial Mortgage Portability | Enables product standardization across Yangtze River Delta jurisdictions as hukou transfer simplification accelerates. |
| AI-Driven Property Valuation Deployment | Unifies satellite imagery, transaction records, and energy consumption data for secondary market appraisals in Shanghai and Hangzhou. |
Study Parameters
Document review covered regulatory filings from the China Banking and Insurance Regulatory Commission, People's Bank of China loan prime rate announcements, and municipal housing bureau policy circulars, complemented by interviews with mortgage underwriting executives at state-owned commercial banks, digital platform product managers, and property valuation specialists. Secondary validation drew from China Construction Bank and Industrial and Commercial Bank of China annual disclosures, provincial statistical yearbooks, and green building certification databases. Bottom-up origination volume estimates were triangulated against top-down macroeconomic housing demand projections.
Cross-reference between historical benchmark rate adjustment patterns and expert panel input on dual carbon policy implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, borrower category, loan purpose, payment structure, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for policy intervention scenarios. Industry-specific forecast inputs incorporated hukou reform velocity indices and municipal affordable housing quota fulfillment rates.
Inputs from central bank policy announcements and major state-owned bank disclosures were available through the study window; gaps in township property rights conversion documentation and developer distress granularity introduce uncertainty bands around third-tier city collateral valuation assumptions. Practitioners should monitor municipal green building mandate enforcement intensity and property tax pilot geographic expansion for early signals of underwriting protocol shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Egypt Facility Management Market
Real Estate
Saudi Arabia Office Real Estate Market
Real Estate
Saudi Arabia Condominiums and Apartments Market
Real Estate
Bahrain Senior Living Market
Real Estate
Norway Facility Management Market
Real Estate
Global Unified Facility Management Market
Real Estate
United Arab Emirates Co-Working Space Market
Real Estate
United Kingdom (UK) Facility Management Market
Real Estate
Qatar Co-Working Office Spaces Market
Real Estate
Germany Manufactured Homes Market
Real Estate
United States Office Real Estate Market
Real Estate
Italy Facility Management Services Market
Real Estate
Indonesia Residential Real Estate Market
Real Estate
Egypt Commercial Real Estate Market
Real Estate
US Real Estate and Hospitality Market
Real Estate
Luxury-Minded Retirement Residences Market