
 Children Wear Market | 2026-2036
Children Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Children Wear Market Intelligence
The children wear sector is pivoting along a widening gap between premium organic-certified lines and mass-market synthetic blends. Carter's Inc. anchors the North American mid-tier through its vertically integrated supply chain and direct-to-consumer channel control. Inditex competes on speed-to-market with its responsive manufacturing network across southern Europe. Nike Inc. differentiates via performance-led activewear positioning that leverages its adult brand equity into licensed children's lines.
Children wear encompasses garments and accessories engineered for wearers from birth through early adolescence, typically sized by age-correlated height and weight percentiles with fabric compositions ranging from conventional cotton-polyester blends to GOTS-certified organic textiles treated with low-impact dyes. The category serves dual commercial purposes: functional protection during developmental stages and symbolic consumption by parent purchasers. Activewear commands accelerating demand as school sports participation expands and athleisure norms migrate downward in age demographics. Outerwear retains concentrated margin pools due to seasonal replacement cycles and technical fabric requirements. Online retail reshapes distribution economics, though specialty stores sustain relevance for fit-dependent categories like infantwear where tactile evaluation reduces return rates.
FDA textile flammability standards, CPSIA lead and phthalate limits, and OEKO-TEX certification protocols collectively elevate compliance costs while screening out informal producers. The EU Green Deal's extended producer responsibility framework for textiles will tighten traceability requirements across cotton sourcing and chemical finishing stages. Stakeholders must monitor how regulatory layering between consumer safety and environmental mandates reshapes supplier qualification criteria and inventory risk profiles.
Market Dynamics
The children wear market is bifurcating along a sustainability fault line where EU Green Deal textile traceability mandates collide with millennial parental preference for organic-certified infant apparel. This tension between regulatory compliance and premium positioning is forcing wholesale supply chain reconfiguration across cotton sourcing, dye chemistry, and end-of-life accountability.
Growth Catalysts
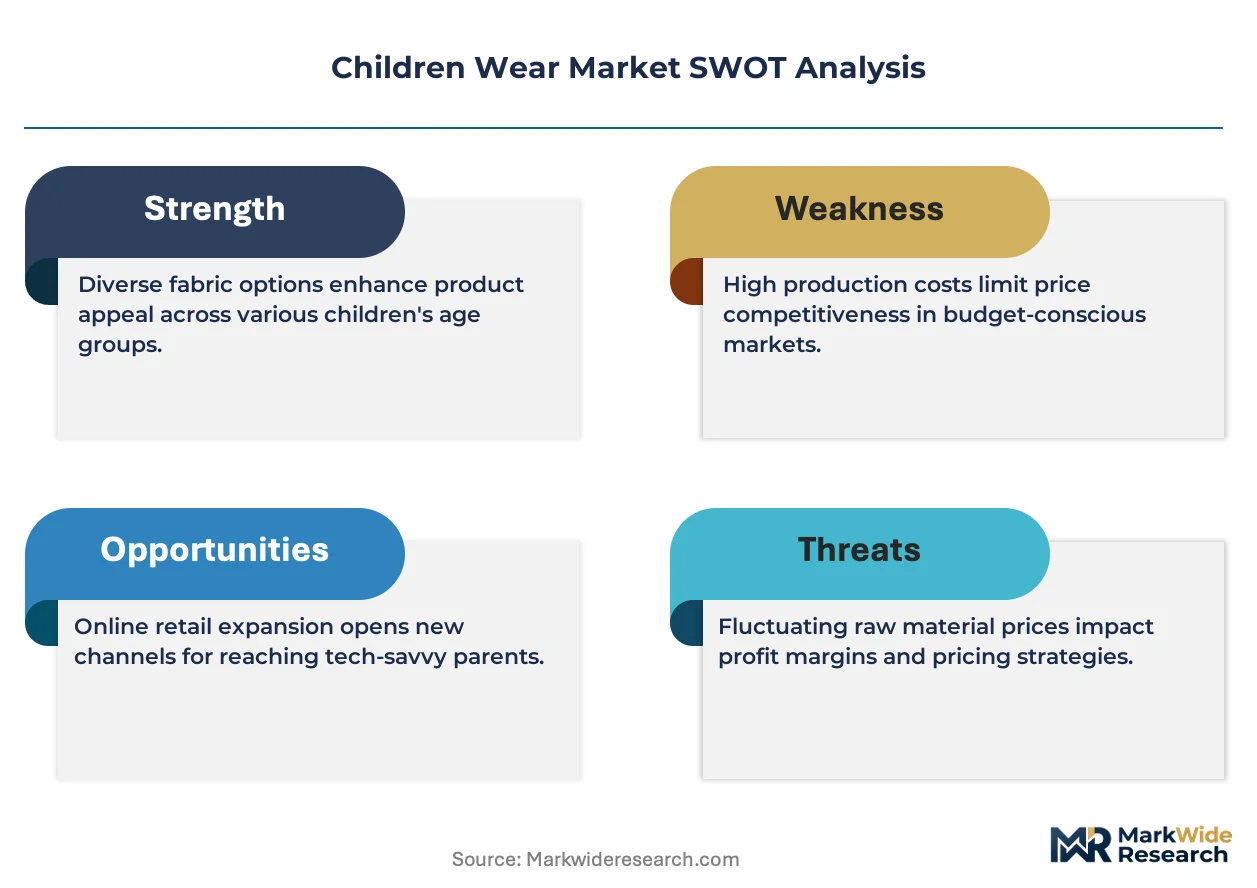
- EU Green Deal Extended Producer Responsibility:Mandatory textile collection and recycling targets are accelerating certified organic cotton adoption as brands preempt compliance costs through upstream material substitution.
- Activewear demand from school sports expansion:Performance-led children's lines are capturing volume as physical education requirements intensify across China's tier-one cities and urban India.
- Millennial parental purchasing power:Urban Indian consumers are driving premiumization through GOTS-certified organic infantwear purchases that signal environmental values.
Market Restraints
- Organic cotton supply concentration:Certified fiber availability clusters in Turkey and India, creating input bottlenecks during harvest volatility.
- CPSIA compliance cost escalation:US lead and phthalate testing requirements impose fixed-cost burdens that disproportionately screen out small-batch domestic producers.
- Technical limitation in biodegradable synthetics:Performance durability gaps in compostable alternatives restrict substitution in outerwear and activewear segments.
Strategic Opportunities
- Underpenetrated secondary cities in China:Tier-two and tier-three urban centers lack premium international brand presence, creating whitespace for localized omnichannel entry.
- Direct-to-consumer subscription models:Size-prediction algorithms and rapid exchange logistics are displacing traditional seasonal bulk purchasing in infantwear.
- India PLI scheme for technical textiles:Production-linked incentives for man-made fiber and technical fabric investments are lowering capital barriers for domestic manufacturing scale-up.
Industry Challenges
- GOTS certification timeline compression:Multi-stage organic supply chain audits create 12-18 month qualification delays that mismatch fast-fashion production cycles.
- Legacy ERP integration with traceability platforms:Blockchain-enabled fiber tracking requires middleware investment that mid-tier brands struggle to resource.
- Colorfastness chemistry reformulation:Low-impact dye performance gaps versus conventional azo compounds create quality-control friction in licensed character apparel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Wear Market |
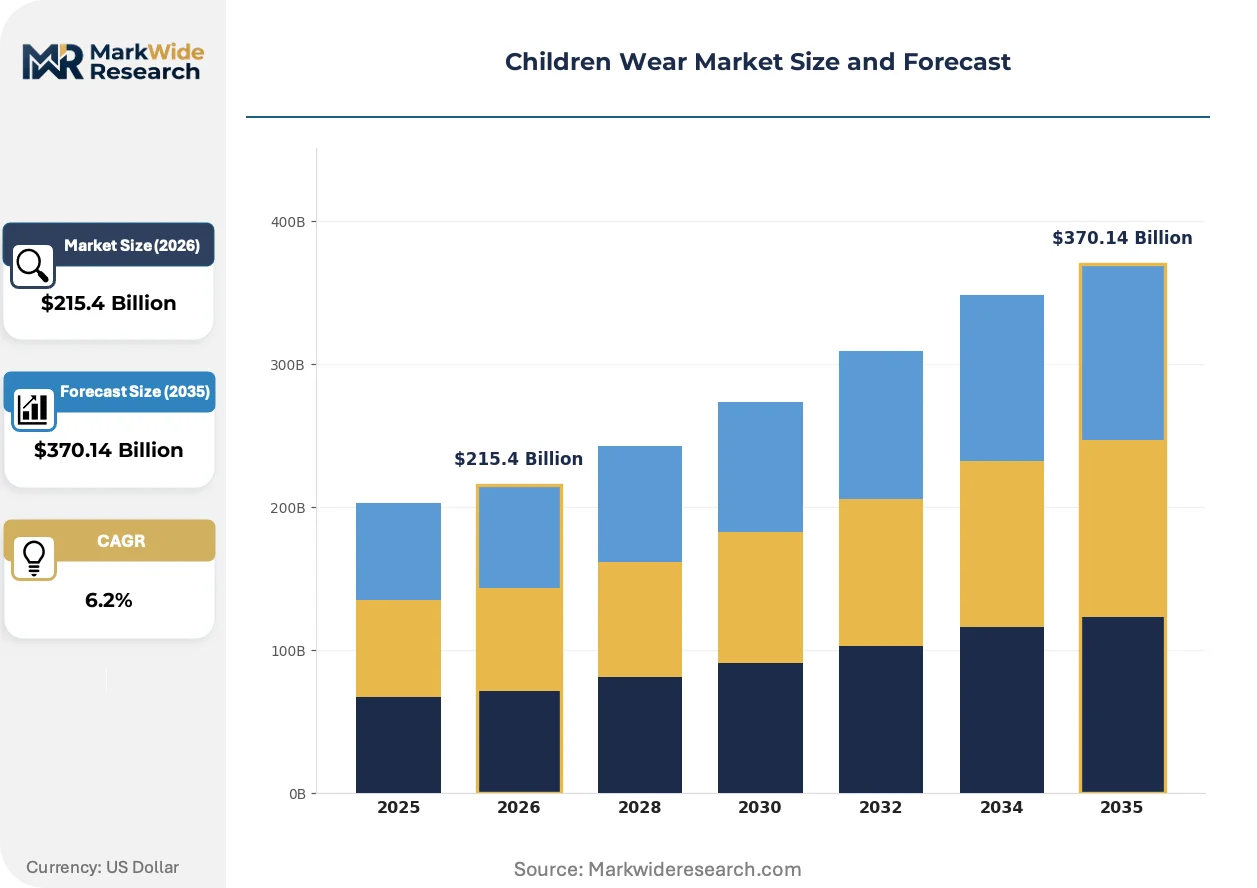
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $370.14 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tops, Bottoms, Outerwear, Activewear Age Group: Infants, Toddlers, Kids, Pre-Teens Gender: Boys, Girls, Unisex, Accessories Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets |
| Companies Covered | Carter's Inc., Nike Inc., Adidas AG, Hennes & Mauritz AB, The Children's Place Inc., Gap Inc., Industria de Diseño Textil S.A. (Inditex), Burberry, Mothercare plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Wear Market Strategic Shifts & Innovations
Digital sizing tools and predictive fit algorithms are compressing return rates in online children wear, while material science advances in bio-based fibers reshape sourcing economics. These intersecting forces are redrawing competitive boundaries between vertically integrated specialists and platform-dependent brands.
Regenerative organic cotton cultivation is absorbing carbon verification premiums into fiber pricing structures. Premium children's brands in Germany and the Netherlands are contracting directly with regenerative farms to secure climate-positive material claims. This backward integration into agricultural practices is compressing margins for conventional cotton traders while creating captive supply advantages for early movers.
REACH chemical restriction expansions are forcing reformulation of wrinkle-resistant and flame-retardant finishes across EU-bound children wear. The industrial consequence is accelerated R&D investment in bio-based alternatives by finishing chemical suppliers. Outerwear and sleepwear categories face the steepest compliance curves, with Portuguese and Italian manufacturers leading substitution timelines due to proximity to regulatory intelligence.
Size-prediction algorithms trained on pediatric growth percentile data are displacing traditional age-based sizing in direct-to-consumer channels. Subscription services leveraging these tools are capturing repeat purchase loyalty in the US and UK markets. This behavioral shift is most visible in infantwear, where tactile evaluation barriers historically protected brick-and-mortar specialty stores.
Children Wear Market Segmentation
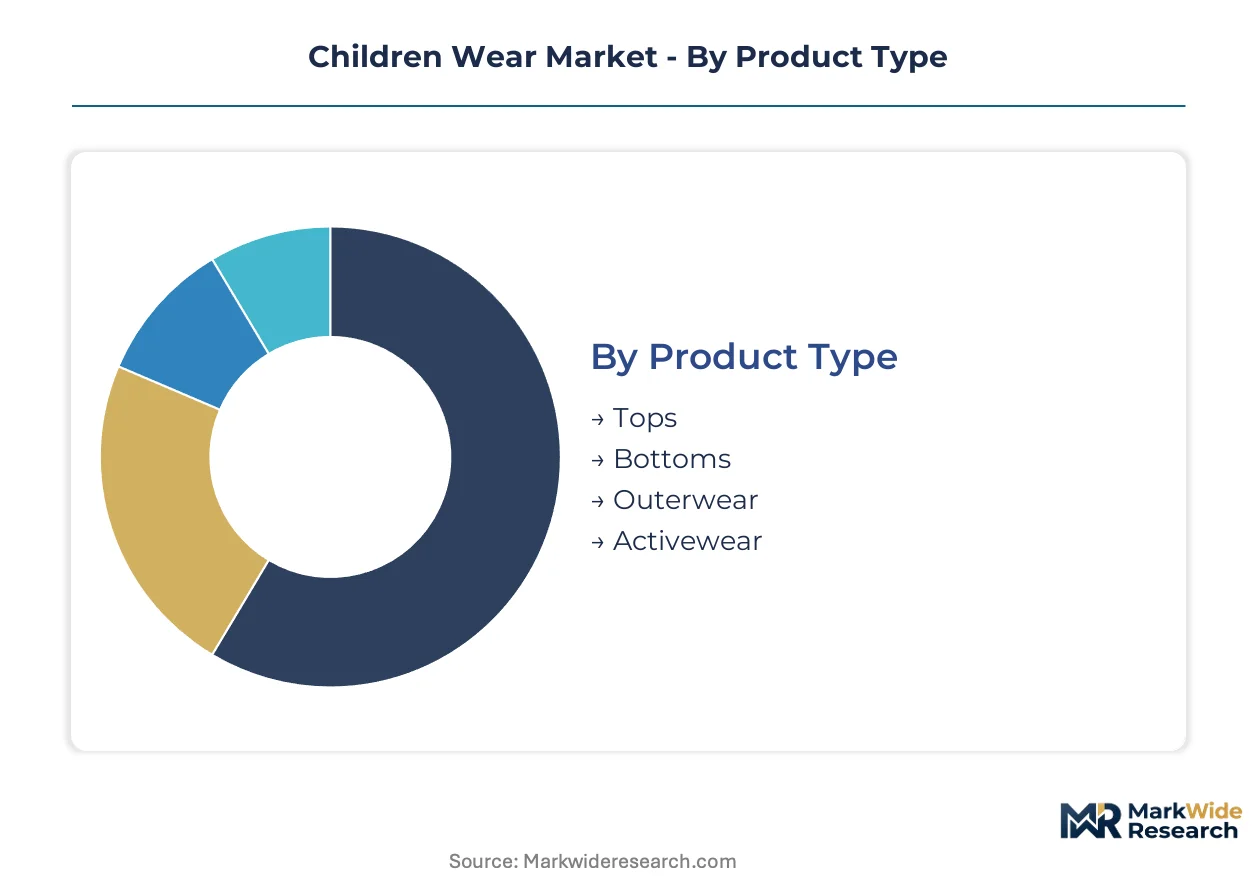
Children wear segmentation reflects dual purchasing logic: functional sizing requirements tied to developmental stages, and symbolic consumption patterns where parental values shape material and channel selection. Distinct margin structures and compliance burdens apply across each dimension.
Product Type:
Integration depth varies sharply: activewear and outerwear embed technical performance specifications into fabric engineering, while tops and bottoms function as standalone commodity purchases with lower entry barriers.
- Tops:Cotton-polyester blends dominate mass-market production. Demand concentrates in China's tier-one cities where licensed character prints command premium shelf space at department stores.
- Bottoms:Denim and knit leggings comprise the volume core. Urban India drives premiumization through organic cotton basics that carry GOTS certification for millennial parental purchasers.
- Outerwear:Technical fabric requirements for waterproofing and thermal regulation elevate compliance costs. EU Green Deal traceability mandates are reshaping sourcing for polyester fill and membrane laminates.
- Activewear:Performance-led lines leverage moisture-wicking synthetics and four-way stretch constructions. School sports expansion across urban India and China's tier-one cities is accelerating category velocity.
Tops and bottoms lead volumes today; activewear is gaining share fastest.
Age Group:
Cost tier stratification dominates: infantwear carries the highest per-unit margin and strictest safety compliance, while pre-teen segments approach adult pricing logic with lower replacement frequency.
- Infants:Sized by weight percentiles with mandatory flame-resistant sleepwear under FDA textile flammability standards. Organic cotton concentration peaks here as parental risk aversion drives certification premiums.
- Toddlers:Rapid growth cycles compress wearable lifespan to 3-4 months per size. Subscription services with predictive sizing algorithms are displacing seasonal bulk purchasing in US and UK markets.
- Kids:School dress codes and physical education requirements shape demand. Activewear penetration deepens as sports participation mandates expand.
- Pre-Teens:Brand consciousness emerges with peer-influenced preferences. Licensed character appeal fades while athletic brand equity from adult lines transfers downward.
Infantwear commands the steepest premium pricing; toddler subscription models are expanding most quickly.
Gender:
Application-driven divergence has softened: unisex styling now spans functional categories while gendered segments retain strength in occasion wear and licensed apparel.
- Boys:Activewear and outerwear dominate purchasing. Performance durability requirements align with school sports participation and outdoor play patterns.
- Girls:Wider category dispersion across dresses, accessories, and athleisure. Social occasion dressing sustains higher average transaction values.
- Unisex:Infant basics and sustainable lines lead positioning. GOTS-certified organic cotton concentrates here as values-driven purchasing transcends traditional gender marketing.
- Accessories:Footwear, headwear, and bags complete outfits. Margin structures exceed apparel due to lower size-driven return rates.
Girls' wear retains the broadest SKU breadth; unisex is climbing the fastest on sustainability positioning.
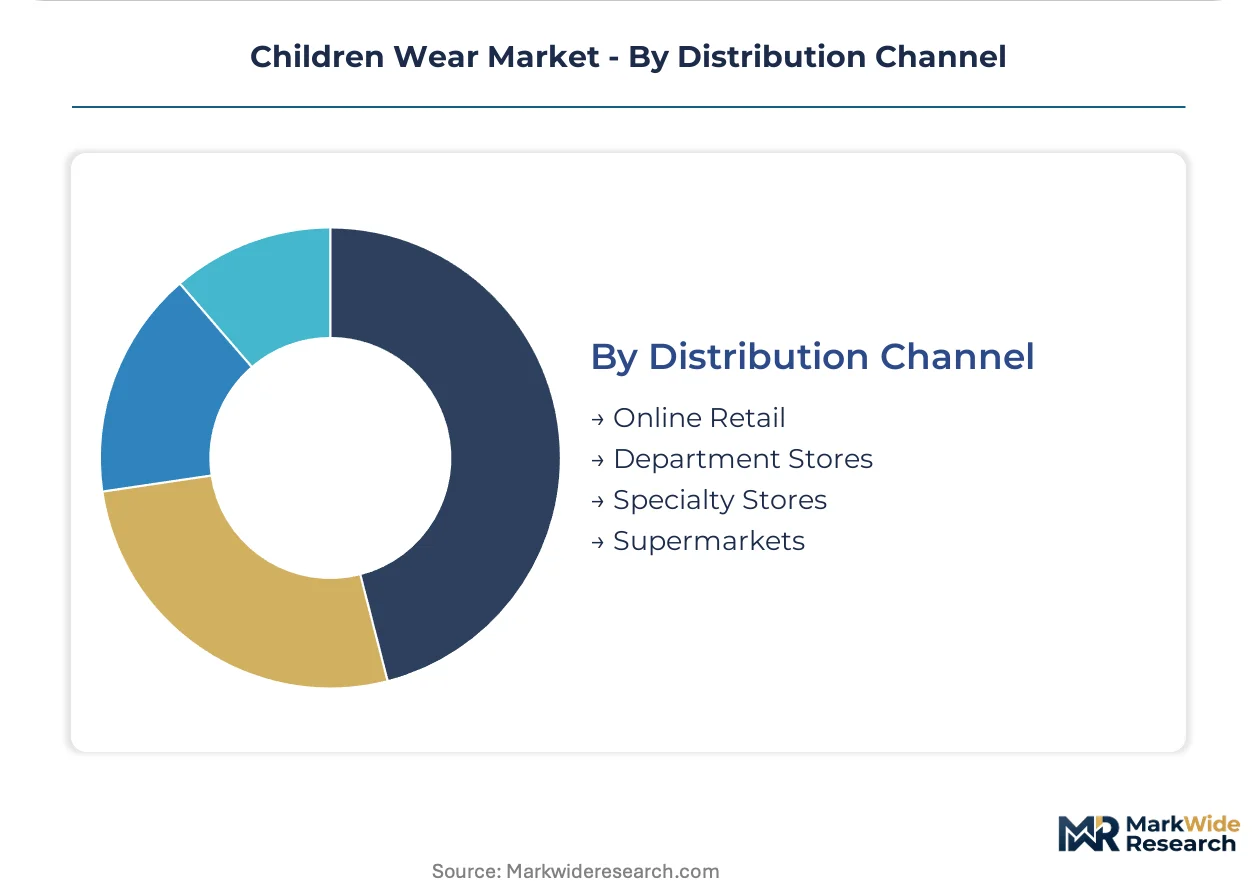
Distribution Channel:
Supply concentration determines competitive access: vertically integrated brands control direct channels while fragmented wholesale relationships dominate legacy retail.
- Online Retail:Digital sizing tools and predictive fit algorithms compress return rates. Subscription models with rapid exchange logistics capture repeat purchase loyalty in infantwear.
- Department Stores:Curated brand mix with seasonal merchandising cycles. Licensed character apparel and occasion dressing sustain relevance despite foot traffic erosion.
- Specialty Stores:Tactile evaluation remains critical for fit-dependent infantwear. Knowledgeable staff reduce return rates through in-person sizing assistance.
- Supermarkets:Price-driven volume play for commodity basics. Private label concentration limits branded premium access.
Specialty stores anchor premium positioning today; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled garment workers in Bangladesh, Vietnam, and southern China anchor production capacity for children's apparel, while design and brand development talent concentrates in New York, London, and Paris. Regulatory divergence between EU Green Deal mandates and US CPSIA compliance creates sourcing complexity for multinational brands.
United States
Millennial parents in urban coastal metros drive premium organic cotton demand for infantwear. FDA textile flammability standards and CPSIA lead testing requirements elevate compliance costs that favor scaled domestic distributors over small-batch producers. Carter's Inc. anchors mid-tier market positioning through vertically controlled supply chains headquartered in Atlanta.
China
Tier-one city households in Shanghai and Beijing absorb premium international brand volumes alongside rising local label competition. SAMR product safety standards and GB textile regulations enforce chemical residue limits that reshape dye chemistry sourcing. The Yangtze River Delta manufacturing cluster dominates export-oriented children wear production with technical activewear specialization.
Germany
Regenerative organic cotton adoption accelerates among environmentally conscious parental purchasers in Berlin and Hamburg. EU Green Deal extended producer responsibility mandates and REACH chemical restrictions force reformulation of flame-retardant finishes. Bavarian technical textile suppliers lead substitution R&D for compliant outerwear membrane laminates.
India
Urban millennial parents in Mumbai and Delhi-NCR propel GOTS-certified organic infantwear premiumization. The PLI scheme for technical textiles lowers capital barriers for domestic man-made fiber manufacturing scale-up. Tiruppur's knitwear cluster pivots toward certified organic cotton processing to capture EU-bound export demand.
United Kingdom
Subscription-based infantwear services leveraging predictive sizing algorithms capture repeat purchase loyalty in London and Manchester. Trading standards enforcement of flammability labeling sustains compliance burdens for imported goods. Leicester's garment manufacturing base contracts for value-oriented private label production serving supermarket channels.
Children Wear Market Key Industry Players
Capital-heavy vertically integrated producers compete with asset-light brand licensors across tiered market positions. The vendor base fragments between multinational apparel conglomerates controlling direct-to-consumer channels, mid-tier specialists with captive supply networks, and regional private label contractors serving price-driven retail. Three archetypes dominate: speed-to-market fast-fashion operators, sustainability-certified premium specialists, and performance-led athletic brand licensors. Competitive moves concentrate on supply chain traceability investments and direct channel expansion.
Within the multinational conglomerate tier, Inditex S.A. and Nike Inc. exemplify divergent sourcing philosophies—European responsive manufacturing versus Asian contract production leveraged through adult brand equity transfer. Carter's Inc. anchors the North American mid-tier through in-house production control. These three occupy positions that illustrate how capital deployment choices separate inventory-risk-bearing verticalists from marketing-heavy licensors.
| Leading Market Players |
|---|
| Carter's Inc. |
| Nike Inc. |
| Adidas AG |
| Hennes & Mauritz AB |
| The Children's Place Inc. |
| Gap Inc. |
| Industria de Diseño Textil S.A. (Inditex) |
| Burberry |
| Mothercare plc |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in Portugal and northern Italy anchor premium outerwear production, wielding captive dye-house control to enforce pricing discipline against Asian contract competitors. Their backward integration into GOTS-certified finishing insulates margin pools from commodity cotton volatility while EU Green Deal traceability mandates compound compliance costs for unintegrated rivals.
Pricing Analysis
Bundled subscription services with predictive sizing algorithms command recurring revenue premiums against unbundled transactional purchasing at department stores. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel control, with GOTS-certified organic lines capturing parental willingness-to-pay in urban India and Germany. Cost compression in mass-market synthetic basics is intensifying because Bangladeshi and Vietnamese producers compete on volume scale. Supermarket private-label buyers exhibit the highest price sensitivity; millennial parents in tier-one Chinese cities show the least.
Supply Chain Analysis
Certification and qualification gating through GOTS, OEKO-TEX, and EU Green Deal extended producer responsibility frameworks concentrates supplier power among pre-audited Turkish and Indian cotton processors. Raw material dependencies center on certified organic fiber, low-impact dye chemistry, and technical membrane laminates for outerwear. Single-source vulnerability in regenerative cotton contracting with specific Turkish farms exposes brands to harvest volatility. Distribution runs through vertically integrated direct-to-consumer channels, wholesale department store partnerships, and rapid-exchange subscription logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France run substantially above India's PLI-subsidized technical textile production, creating margin capture opportunities for cross-border supply restructuring.
For Market Incumbents: Extend GOTS-certified organic cotton contracting into regenerative agriculture partnerships to preempt fiber scarcity as EU traceability mandates tighten. Deepen backward integration into Tiruppur knitting clusters to defend against emerging Indian domestic brands leveraging PLI scheme subsidies for technical activewear scale-up.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium GOTS-certified lines and economy supermarket basics offers whitespace for certified-organic private-label positioning. Target China's tier-two cities with localized omnichannel entry; deploy size-prediction algorithms through WeChat mini-programs to bypass legacy specialty store fit-evaluation advantages.
For Investors and Strategic Acquirers: Apparel conglomerates with adult brand equity are the most active acquirer in this space, seeking licensed children's line extensions. Five-to-ten year viability hinges on traceability infrastructure ownership; target mid-tier specialists with captive GOTS-certified supply networks. Watch for EU Green Deal textile collection mandate enforcement as inflection indicator for compliance-cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Cotton Contracting | Secures climate-positive fiber claims ahead of EU carbon verification requirements. |
| Direct-to-Consumer Subscription Launch | Captures repeat purchase loyalty through predictive sizing algorithms in infantwear. |
| GOTS Certification Acceleration | Preempts 12-18 month audit delays that mismatch fast-fashion production cycles. |
| Technical Textile PLI Utilization | Lowers capital barriers for domestic Indian manufacturing of man-made fiber activewear. |
| Blockchain Traceability Integration | Meets EU Green Deal extended producer responsibility mandates for fiber origin verification. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with brand supply chain directors, retail category buyers, GOTS certification auditors, and technical textile R&D leads with secondary validation. Primary fieldwork draws from customs trade databases, SEC apparel company filings, EU ECHA chemical restriction updates, and Indian PLI scheme disbursement records. Bottom-up segment sizing triangulates against top-down macroeconomic consumption indicators.
Rate-of-change decomposition separates volume growth from pricing mix effects across the projection horizon. The analytical framework models product type, age group, distribution channel, and certification tier as core segmentation dimensions. CAGRs derive from pediatric population growth trajectories, school sports participation mandates, and organic cotton supply elasticity assumptions. Industry-specific inputs include GOTS certification pipeline data and EU Green Deal implementation timelines.
Caveats apply where regulatory enforcement delays, organic cotton harvest failures, or biodegradable synthetic performance breakthroughs could materially shift the outlook. Forecasts rest on documented assumptions about substitution elasticity and compliance cost pass-through. A model refresh is warranted upon material change in EU extended producer responsibility mandate rollout schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO