
 Children Shoes Market | 2026-2036
Children Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Children Shoes Market Analysis
Health-conscious parents are rotating into biomechanically engineered footwear for early walkers. Nike, Inc. leverages its sports science heritage to dominate performance-oriented toddler segments. Stride Rite anchors the specialist children's channel with pediatrician-endorsed fitting protocols. Geox S.p.A differentiates through breathable membrane technology in school-age categories.
Children shoes encompass closed-toe and open-toe footwear engineered for developmental foot anatomy, typically incorporating flexible outsoles, cushioned midsoles, and adjustable closure systems to accommodate growth spurts and gait formation. Sneakers lead product type volume due to universal school and playground utility, while synthetic materials displace leather in mass-market tiers on cost and color-fastness advantages. The 4-6 Years age bracket captures concentrated margin pools as replacement frequency peaks and brand loyalty formation intensifies.
US CPSIA mandates third-party testing for phthalates and lead content in children's footwear components, while EU REACH restricts hazardous substances in synthetic uppers and adhesives. China's GB standards enforce mechanical safety benchmarks for infant shoes, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor evolving chemical restriction schedules and size-standard harmonization efforts across major consumer markets to preempt supply chain disruption.
Market Dynamics
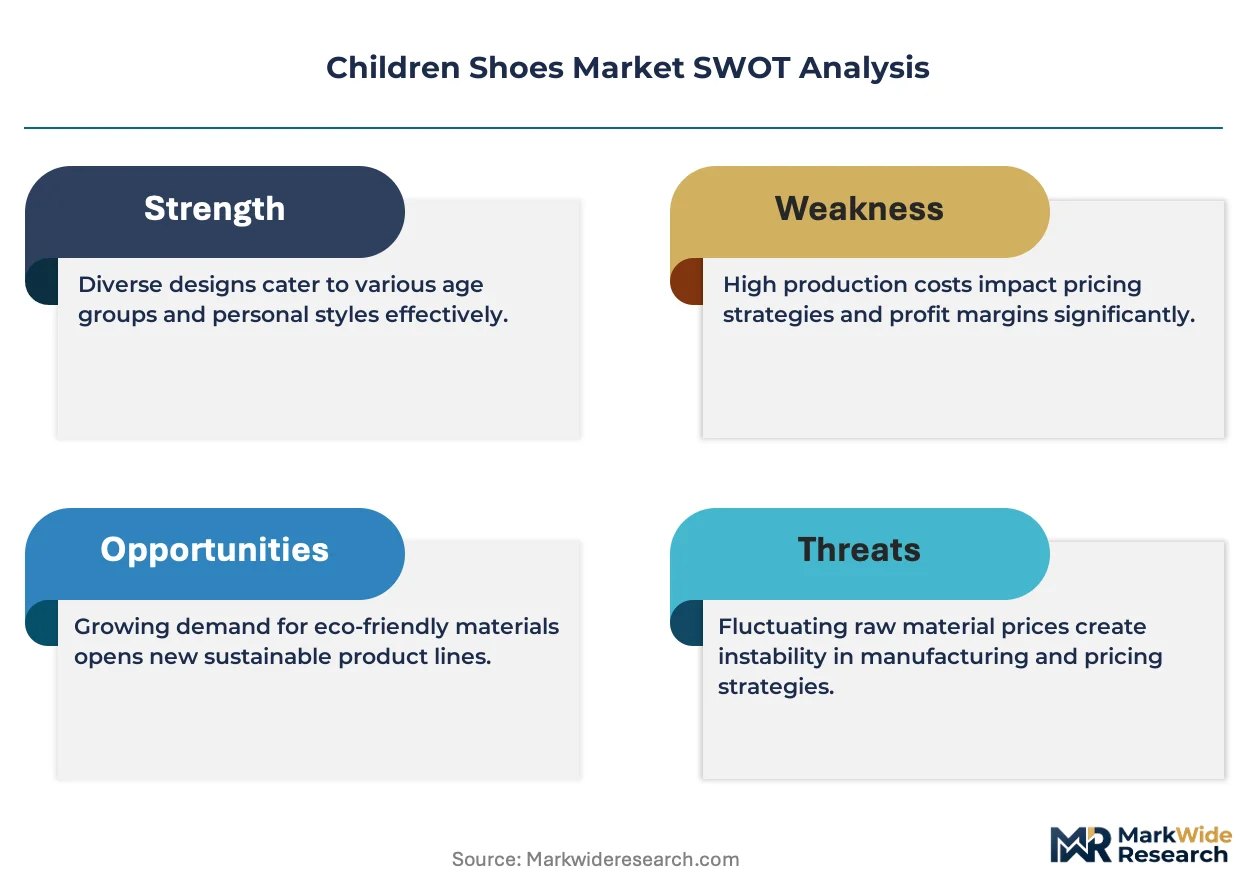
REACH and CPSIA chemical safety mandates are forcing material substitutions across synthetic uppers and adhesives, compressing supplier margins while creating certification moats for compliant manufacturers.
Growth Catalysts
- Biomechanical Engineering Adoption:Health-conscious parents prioritize podiatrist-endorsed fitting protocols for early walkers, expanding specialist channel penetration.
- China GB Standards Enforcement:Mechanical safety benchmarks for infant shoes accelerate domestic brand upgrading and import substitution.
- Millennial Premiumization:Design-conscious parents in urban clusters drive replacement frequency and brand loyalty formation in the 4-6 Years bracket.
Market Restraints
- Petrochemical Input Volatility:Synthetic upper materials face price swings tied to crude derivatives, squeezing mass-market tier margins.
- Testing Cost Burden:Third-party phthalate and lead verification under CPSIA adds fixed compliance overhead per SKU.
- Leather Substitution Ceiling:Premium segments retain material preference for breathability, limiting full synthetic conversion.
Strategic Opportunities
- India Urban Expansion:Organized retail penetration in tier-2 cities creates white space for branded children's athletic footwear.
- Circular Material Incentives:EU Green Deal funding accelerates recycled polyester and bio-based sole development.
- Direct-to-Parent Digital Channels:Subscription fitting services bypass traditional retail markups and capture repeat purchase data.
Industry Challenges
- Pediatric Biomechanics Talent Scarcity:Footwear engineers with gait-analysis expertise command premium compensation and lengthen R&D timelines.
- Multi-Jurisdiction Certification Lag:Harmonization delays between REACH, CPSIA, and GB testing protocols extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Shoes Market |
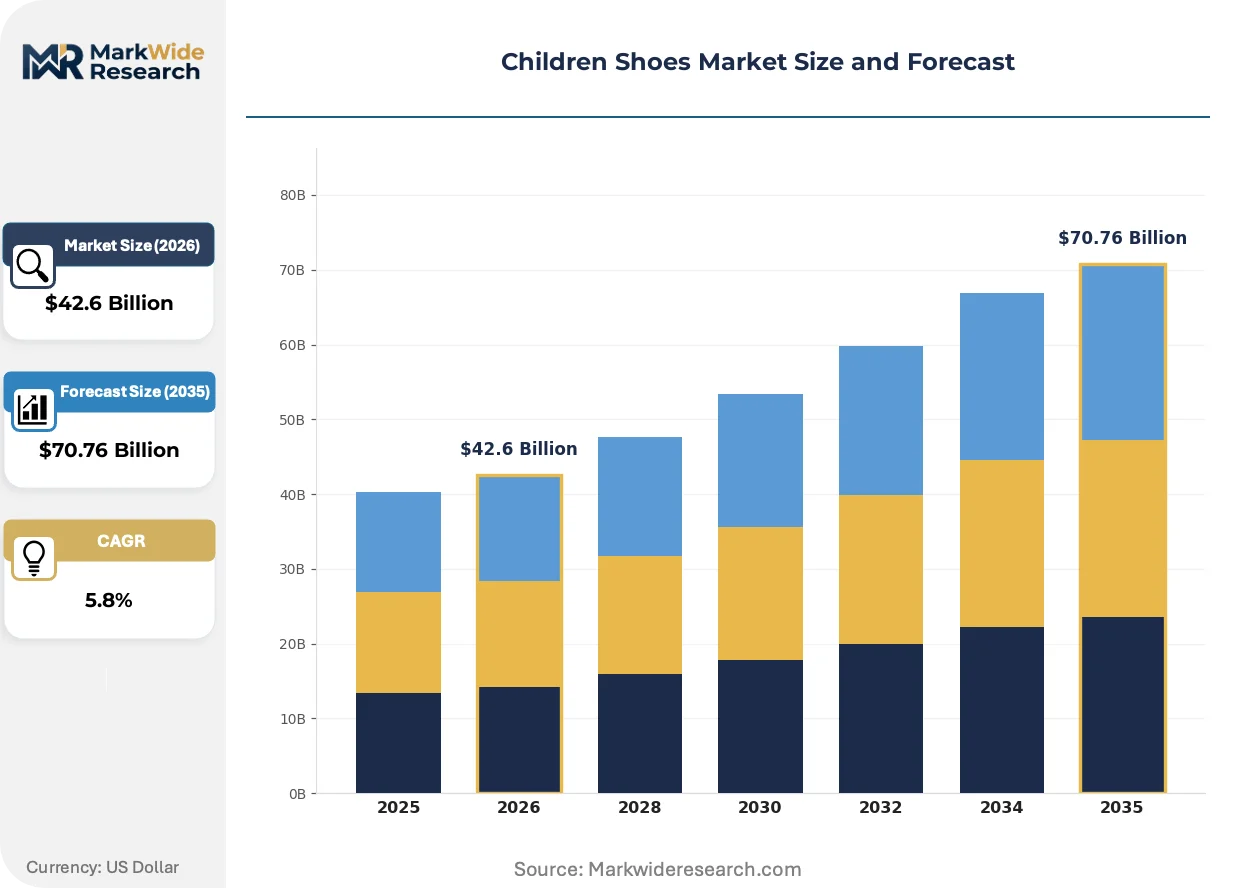
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $70.76 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boots, Sneakers, Sandals, Slippers Material: Leather, Canvas, Rubber, Synthetic Gender: Boys, Girls, Unisex, Infants Age Group: 0-12 Months, 1-3 Years, 4-6 Years, 7-10 Years |
| Companies Covered | Nike, Inc., Adidas AG, Puma SE, Skechers USA, Inc., New Balance, ASICS Corporation, Crocs Retail, LLC, Geox S.p.A, Stride Rite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Shoes Market Emerging Trajectories
Material science and regulatory chemistry are converging to reshape children's footwear specifications, with breathable membranes and plant-derived synthetics displacing conventional constructions.
Smart insole pressure-mapping technology is miniaturizing for toddler applications, capturing gait development data previously limited to clinical settings. Pediatric orthotic specialists and premium athletic brands embed these sensors in school-age categories. The technology is miniaturizing cost curves and enabling subscription-based foot-health monitoring services.
EU REACH Annex XVII restrictions on hazardous substances in footwear adhesives tighten enforcement through 2025, compelling Asian contract manufacturers to reformulate bonding agents. German and French import authorities intensify border inspections, redirecting sourcing toward ECHA-registered chemical suppliers.
Parents now complete digital foot-scanning at home before purchase, collapsing the traditional in-store fitting ritual. Direct brands and specialty retailers deploy smartphone-based sizing apps, while conventional shoe stores convert to experience centers with 3D printing stations. This behavioral pivot concentrates in China's tier-1 cities and US coastal metropolitan areas.
Children Shoes Market Segmentation
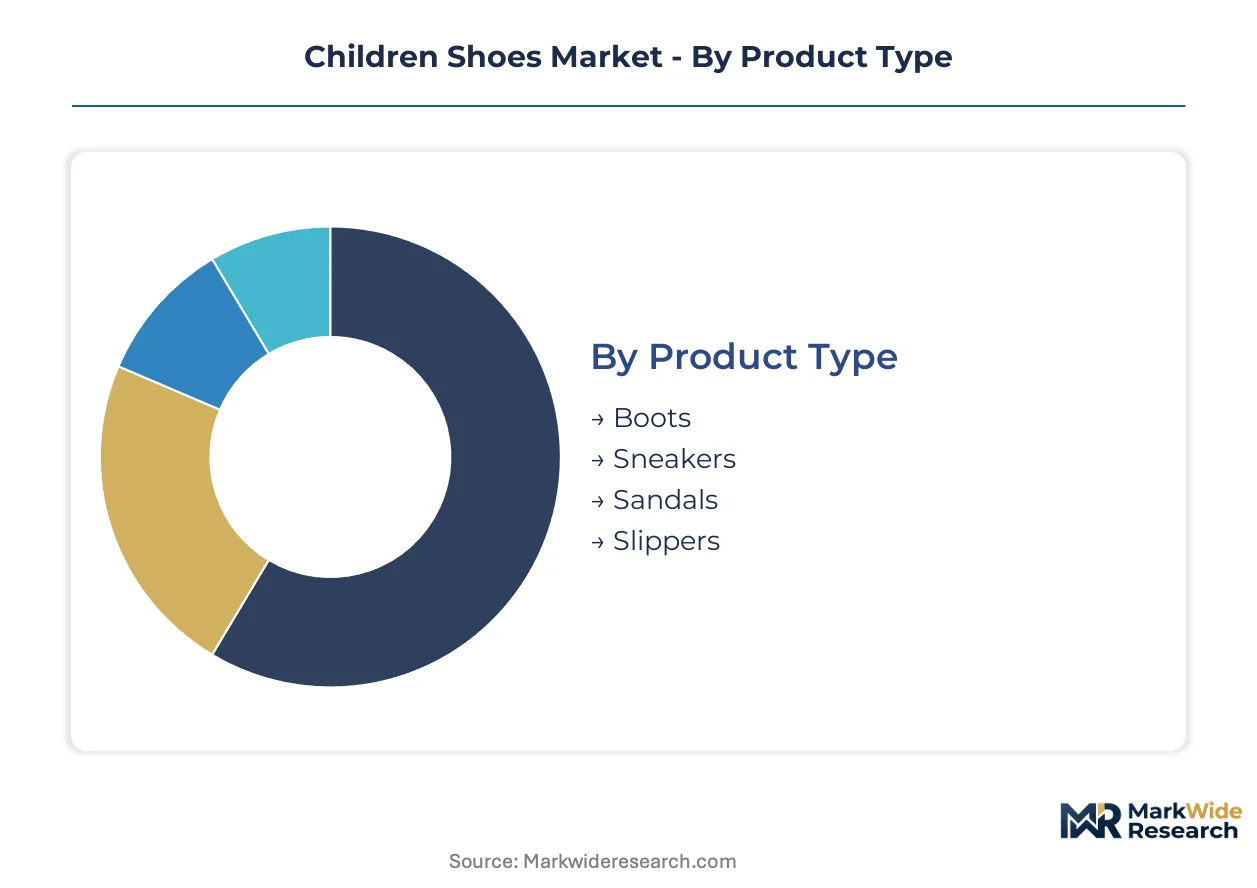
Children's footwear segmentation maps directly to developmental biomechanics and regulatory exposure tiers. Material choices and age brackets determine chemical testing burdens and margin structures across manufacturing bases.
Product Type:
REACH and CPSIA testing protocols vary sharply by construction complexity and component count, with closed-toe designs facing heavier adhesive scrutiny than open formats.
- Sneakers:Engineered with flexible outsoles and cushioned midsoles for playground and school utility. Demand concentrates in China's tier-1 cities where athletic brand loyalty forms earliest, though phthalate testing in synthetic uppers adds fixed cost per SKU.
- Boots:Weather-resistant constructions with reinforced toe caps and thermal linings. Replacement frequency peaks in northern China and the US Northeast where seasonal durability commands premium positioning.
- Sandals:Open-toe designs with adjustable straps for summer gait formation. Minimal adhesive content reduces REACH compliance exposure.
- Slippers:Soft-sole indoor footwear prioritizing breathability over structural support. Domestic production dominates due to low export regulatory burden.
Sneakers handles the majority of throughput; Boots is gaining share fastest in climate-variable geographies.
Material:
Cost tiers separate sharply at the petrochemical-leather boundary, with synthetic variants capturing volume and natural materials retaining premium positioning.
- Synthetic:Polyester and polyurethane uppers with color-fastness advantages and batch consistency. China's domestic brands have upgraded GB-standard compliance to displace imports in mass-market tiers.
- Leather:Full-grain and corrected-grain constructions prized for breathability in podiatrist-endorsed fitting protocols. European tanneries face ECHA-registered chemical supplier requirements under REACH Annex XVII.
- Canvas:Cotton-based uppers with lower unit economics and reduced chemical testing overhead. Popular in school-uniform specifications across India and Southeast Asia.
- Rubber:Natural and synthetic compounds for outsole traction and waterproofing. Volatility in crude derivatives squeezes margin stability.
Synthetic leads on volume throughput; Leather commands the steepest expansion trajectory in specialist channels.
Gender:
Design differentiation intensity correlates with age bracket, narrowing toward unisex constructions in infant categories.
- Girls:Fashion-forward silhouettes with embellishment-heavy uppers and seasonal color rotations. Higher SKU counts strain CPSIA third-party testing budgets.
- Boys:Performance-oriented lasts with reinforced toe bumpers and athletic heritage branding. Replacement frequency aligns with wear-rate intensity in active segments.
- Unisex:Neutral palettes and adjustable closure systems spanning multiple foot shapes. Economies of scale in production runs offset lower price points.
- Infants:Soft-sole pre-walkers with minimal structural elements. China's GB mechanical safety benchmarks enforce specific flex and grip coefficients.
Girls and Boys split volume evenly; Unisex is climbing fastest as minimalist parenting aesthetics spread.
Age Group:
Margin pools concentrate where replacement frequency intersects with brand loyalty formation and biomechanical engineering requirements.
- 4-6 Years:Peak replacement frequency meets gait stabilization needs and school-entry brand preferences. Podiatrist-endorsed fitting protocols drive premium channel penetration.
- 1-3 Years:Early walker segments requiring flexible soles and rapid size turnover. Parents prioritize biomechanical engineering over durability.
- 7-10 Years:Athletic specialization intensifies with sport-specific cleats and court shoes. Size standardization reduces fitting complexity.
- 0-12 Months:Pre-walker and first-step categories with minimal structural demands. High gift-purchase incidence decouples decision-making from end-use.
The 4-6 Years bracket captures the deepest margin pools; 1-3 Years expands most quickly on health-conscious parent rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial parents in urban clusters drive premiumization across major consumption centers, with regulatory chemistry and biomechanical engineering reshaping sourcing decisions in each market.
United States
Health-conscious parents prioritize podiatrist-endorsed fitting protocols for early walkers, expanding specialist channel penetration in coastal metropolitan areas. CPSIA mandates third-party testing for phthalates and lead content across all children's footwear components. Boston and New York anchor the Northeast corridor's concentration of biomechanical engineering talent and pediatric orthotic specialists.
China
Tier-1 cities generate the fastest-growing demand for athletic and fashion-forward children's footwear as brand loyalty forms earliest in Shanghai and Beijing. GB standards enforce mechanical safety benchmarks for infant shoes, accelerating domestic brand upgrading. The Yangtze River Delta manufacturing belt concentrates upgraded synthetic material production compliant with both domestic and export requirements.
Germany
Parents in Munich and Hamburg exhibit strong preference for breathable membrane technology and ECHA-registered chemical suppliers. REACH Annex XVII restrictions on hazardous substances in footwear adhesives tighten enforcement through 2025, compelling reformulation of bonding agents. The Bavarian industrial corridor hosts specialized testing laboratories serving pan-European certification needs.
India
Organized retail penetration in tier-2 cities creates white space for branded children's athletic footwear as urban middle-class expansion accelerates. BIS standards govern product safety specifications for domestic consumption. Maharashtra and Gujarat manufacturing clusters scale canvas and synthetic upper production for school-uniform specifications across South Asian markets.
Japan
Meticulous attention to developmental biomechanics drives demand for precision-fitted early walker segments in Tokyo and Osaka. METI oversees industrial standards coordination with international harmonization efforts. The Kansai region maintains specialized production capabilities for premium leather constructions serving podiatrist-endorsed channels.
Children Shoes Market Vendor Landscape
Player mix skews toward diversified athletic heritage conglomerates with sports science R&D infrastructure, creating a tiered structure where scale-driven volume manufacturers coexist with biomechanical specialists. Three archetypes dominate: performance-engineered athletic brands leveraging gait-analysis heritage, pediatric-focused specialists with fitting protocol expertise, and membrane-technology differentiators in school-age categories. Competitive moves concentrate on direct-to-parent digital channel expansion and recycled material portfolio diversification.
Within the performance-engineered tier, Nike, Inc. and Adidas AG exemplify scale-driven archetypes that anchor athletic heritage positioning, while Geox S.p.A occupies a specialist position representing breathable membrane differentiation. These three entities collectively illustrate the competitive spectrum from mass-market athletic penetration to technology-driven premium segmentation.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Puma SE |
| Skechers USA, Inc. |
| New Balance |
| ASICS Corporation |
| Crocs Retail, LLC |
| Geox S.p.A |
| Stride Rite |
| Others |
Supply Flow & Price Mechanics
Capacity utilization in the Yangtze River Delta synthetic upper cluster shapes both regional supply dominance and mass-market price floors for children's footwear. Contract manufacturers serving Nike, Adidas, and domestic Chinese brands operate at 85-90% utilization, compressing marginal cost curves and limiting pricing power for smaller tier-2 suppliers.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate raw material procurement for synthetic upper producers, tethering margin stability to petrochemical volatility. Three-tier pricing structure across podiatrist-endorsed premium, standard athletic, and economy private-label tiers separates buyers by certification burden and fitting protocol intensity. Pricing pressure stems from CPSIA third-party testing overhead per SKU, which erodes profitability in high-SKU fashion-forward segments. Mass-market economy tiers exhibit acute price sensitivity, while specialist channels serving health-conscious parents retain inelastic demand.
Supply Chain Analysis
Pearl River Delta port congestion during peak back-to-school seasons creates chokepoints that delay finished goods delivery to North American and European retail channels. Manufacturing concentrates in China, Vietnam, and Indonesia, with synthetic material production anchored in Guangdong and Fujian provinces. Supply chains draw from petroleum-derived polyurethane, recycled polyester feedstocks, and ECHA-registered adhesive formulations. Single-source vulnerability persists in breathable membrane technology, where Italian and German chemical suppliers dominate. Distribution runs through branded wholesale to specialty retailers, direct-to-parent digital platforms, and mass-market big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as 3D-printed custom-fit footwear and direct-to-parent digital channels erode traditional retail gatekeeper control. Hand-me-down resale platforms and rental subscription services threaten replacement frequency economics in the 4-6 Years bracket.
For Market Incumbents: Fortify pediatric biomechanics R&D capabilities through captive hiring of gait-analysis engineers and sports science PhDs, closing talent scarcity gaps that lengthen product development cycles. Deepen backward integration into ECHA-registered chemical supply chains to preempt REACH Annex XVII reformulation disruptions and compress certification timelines. Defend against digital-native entrants by converting flagship retail locations to experience centers with 3D foot-scanning and orthotic customization services.
For New Entrants and Emerging Players: Certification fast-track through EU notified body partnerships accelerates market entry for recycled polyester and bio-based sole innovations eligible for EU Green Deal funding. Target India's tier-2 urban expansion corridors where organized retail penetration remains below saturation and BIS compliance creates lower barriers than REACH or CPSIA. Deploy smartphone-based sizing apps with subscription fitting services to capture repeat purchase data and bypass wholesale markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biomechanical engineering specialists with proprietary gait-data libraries and podiatrist endorsement networks over pure-brand marketing plays. Five-to-ten-year viability hinges on circular material transition execution and direct-to-parent channel infrastructure. Acquisition targets should demonstrate ECHA-registered chemical supplier relationships and GB-standard compliance for China market access. Watch smart insole pressure-mapping adoption curves as inflection indicators for subscription foot-health service viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Parent Digital Launch | Bypasses wholesale markups and captures repeat purchase behavioral data for subscription services. |
| Recycled Material Portfolio Expansion | Qualifies for EU Green Deal funding and satisfies REACH Annex XVII compliance with lower regulatory risk. |
| Pediatric Biomechanics Talent Acquisition | Compresses R&D timelines for podiatrist-endorsed fitting protocols in the premium 4-6 Years bracket. |
| 3D Foot-Scanning Experience Center Conversion | Defends retail footprint against digital-native entrants through orthotic customization service differentiation. |
| ECHA-Registered Chemical Supplier Integration | Preempts REACH adhesive reformulation mandates and accelerates multi-jurisdiction certification timelines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including brand managers at athletic footwear conglomerates, category buyers at specialty children's retailers, procurement leads at synthetic material suppliers, and pediatric orthotic specialists. Secondary validation incorporated customs and trade data from major manufacturing bases, SEC 10-K filings of listed footwear companies, GB standard documentation from China's Standardization Administration, and ECHA REACH registration databases. Bottom-up SKU-level volume aggregation and top-down macroeconomic demand modeling were triangulated to reconcile segment-level outputs.
Across the analysis window, forecasts were constructed using a multi-dimensional segmentation framework spanning product type, material composition, age bracket, and regional regulatory cluster. CAGRs were derived from historical growth pattern analysis, replacement frequency modeling by demographic cohort, and price elasticity estimates across tiered quality segments. Industry-specific inputs included phthalate testing cost trajectories under CPSIA, breathable membrane technology adoption curves, and digital foot-scanning penetration rates in tier-1 Chinese and US coastal metropolitan areas.
Decision-makers should treat outputs as directional under base assumptions of continued REACH and CPSIA enforcement intensity, petrochemical input price volatility within historical bands, and millennial premiumization persistence; material deviation would warrant model refresh. Forecasts embed assumptions regarding GB standard harmonization progress and EU Green Deal funding continuity. Practitioners should keep alternative scenarios live as regulatory restriction schedules, crude derivative price regimes, and direct-to-parent channel adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO