
 Cargo Vessel Market | 2026-2036
Cargo Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Vessel Market Analytics
Modular vessel configurations and standardized container slot arrangements is shifting procurement patterns across major fleet operators. Hyundai Heavy Industries leverages integrated engineering platforms to dominate ultra-large container carrier construction. China State Shipbuilding Corporation anchors government-backed fleet modernization programs across state-owned shipping lines. Samsung Heavy Industries differentiates through advanced LNG containment systems for dual-fuel propulsion architectures.
Cargo vessels are steel-hulled commercial ships engineered to transport bulk commodities, containerized goods, or liquid cargoes across maritime routes, with deadweight tonnage ratings spanning 10,000 to 200,000+ tonnes and structural designs optimized for specific load distributions. Container ships command premium contract values due to standardized TEU capacity scaling and repeat-order economics from integrated logistics carriers. Bulk carriers represent a mature segment where margin pools concentrate in capesize and very large ore carrier categories serving iron ore and coal trades. Tanker demand bifurcates between crude oil carriers with long-haul route specialization and product tankers serving refined petroleum distribution networks.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index and Carbon Intensity Indicator standards that mandate hull retrofits or scrapping decisions for older tonnage. Classification societies including Lloyd's Register and DNV apply tiered notation systems for alternative fuels that directly shape newbuild specification sheets and financing terms. Shipowners and charterers must monitor regulatory enforcement consistency across flag states and port state control regimes to align fleet investment cycles with compliance thresholds.
Market Dynamics
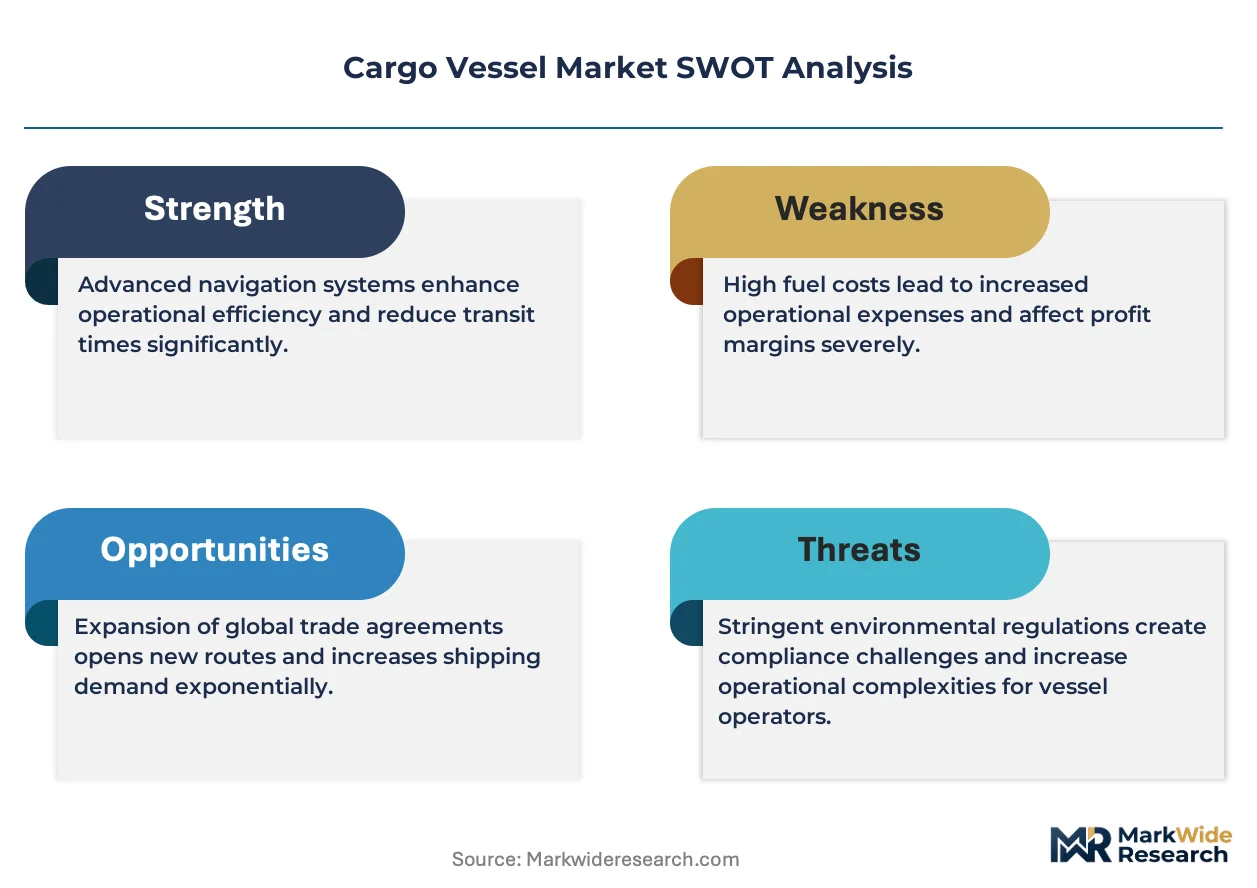
The International Maritime Organization's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator regulations are forcing shipowners into accelerated fleet renewal decisions, compressing investment cycles and redirecting capital toward dual-fuel propulsion architectures.
Growth Catalysts
- E-commerce logistics expansion:Container shipping lines are scaling ultra-large carrier orders to capture trans-Pacific and intra-Asian parcel volume surges. Terminal operators in Shanghai and Singapore are expanding berth capacity to match.
- EU Green Deal maritime provisions:The European Union's inclusion of shipping in its emissions trading system creates compliance-driven demand for LNG-ready and methanol-capable newbuilds.
- Iron ore trade concentration:Brazilian and Australian mining majors are locking in long-term capesize charter contracts, stabilizing orderbook visibility for Korean and Chinese shipyards.
Market Restraints
- Steel plate cost volatility:Shipbuilding margins compress when heavy plate prices spike, particularly affecting mid-tier yards in China's Yangtze River delta.
- Engine supply concentration:WinGD and MAN Energy Solutions dominate two-stroke marine engine manufacturing, creating bottlenecks for alternative fuel retrofit programs.
- Limited green methanol availability:Fuel production capacity lags vessel delivery schedules, constraining operational deployment of dual-fuel tonnage on deep-sea routes.
Strategic Opportunities
- Indian shipbreaking modernization:Alang-Sosiya yards are upgrading environmental compliance infrastructure to capture EU-flagged vessel recycling demand under the Hong Kong Convention.
- Autonomous navigation systems:Machine learning-based route optimization is converging with satellite connectivity to enable reduced-crew operations on coastal feeder routes.
- Japan's offshore wind vessel demand:METI-backed floating foundation installation programs require specialized heavy-lift vessel designs absent from current orderbooks.
Industry Challenges
- Marine engineer shortage:Classification societies including Lloyd's Register and DNV face extended certification backlogs for dual-fuel system engineers, delaying vessel delivery acceptance.
- Retrofit financing complexity:First-of-kind hull modification projects for methanol conversion lack standardized loan covenant structures, freezing capital deployment for older tonnage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Vessel Market |
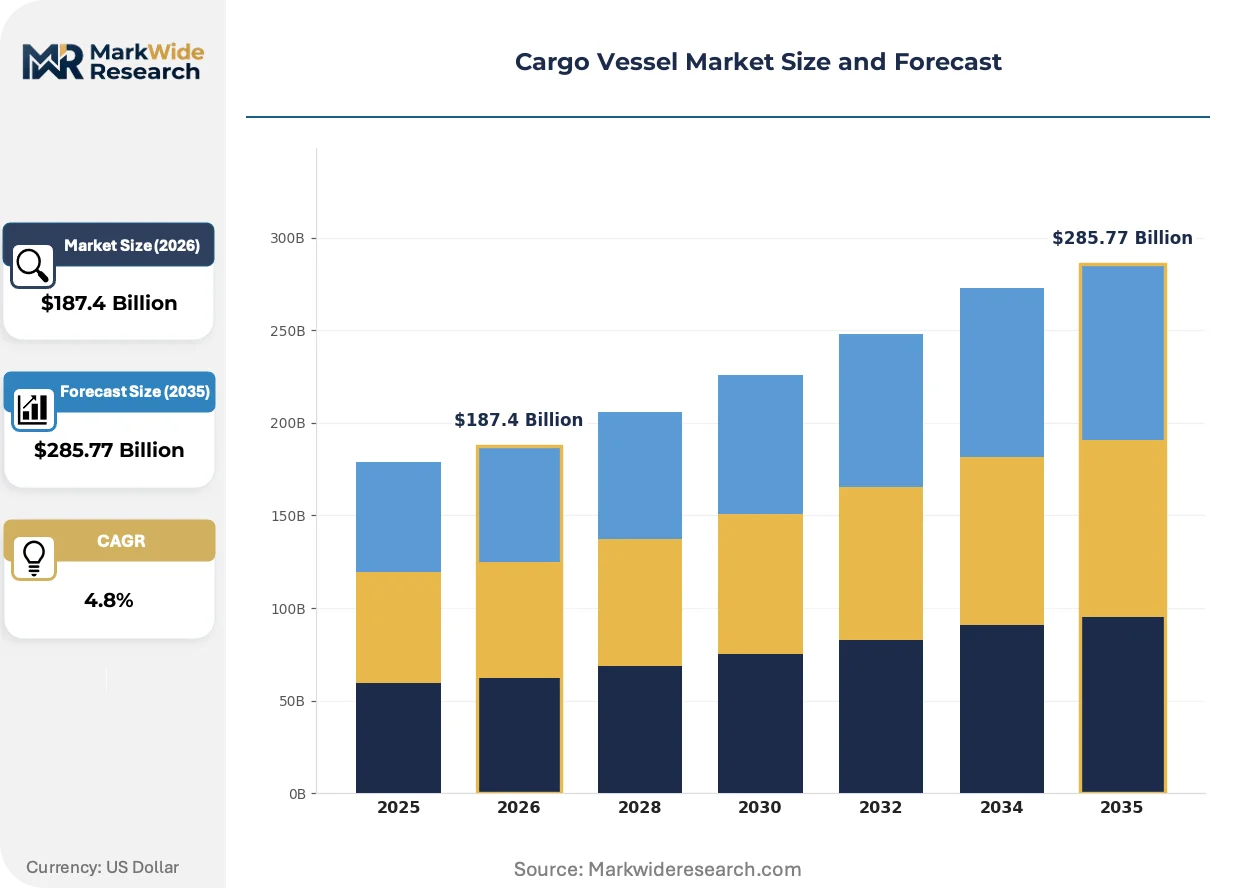
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Container Ship, Bulk Carrier, Tanker, Ro-Ro Ship Size Category: Small, Medium, Large, Very Large Propulsion Technology: Diesel, LNG, Wind-Assisted, Hybrid Application Area: International Trade, Coastal Shipping, Inland Waterway, Charter Services |
| Companies Covered | Hyundai Heavy Industries, China State Shipbuilding Corporation, Mitsubishi Heavy Industries, Samsung Heavy Industries, Daewoo Shipbuilding & Marine Engineering, Korea Shipbuilding & Offshore Engineering, Damen Shipyards Group, General Dynamics NASSCO, Namura Shipbuilding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Vessel Market Evolving Landscape
Alternative fuel propulsion architectures are displacing conventional heavy fuel oil systems across all vessel size categories, with shipowners treating fuel flexibility as a residual value hedge against regulatory tightening.
Ammonia fuel cell technology is converging with solid oxide fuel cell systems to enable zero-carbon propulsion without carbon capture equipment. Maersk and CMA CGM are piloting ammonia-ready engine specifications in 8,000+ TEU newbuilds. This convergence is compressing the commercialization timeline for hydrogen-derived marine fuels and forcing engine makers to accelerate R&D spending.
China's Ministry of Ecology and Environment is enforcing domestic emission control area standards that exceed IMO global sulfur caps, requiring scrubber installations or fuel switching for vessels calling Shanghai, Ningbo, and Shenzhen. The regulation affects 40% of global container throughput. Shipowners are responding by prioritizing LNG dual-fuel specifications for Asia-dedicated strings.
Charterers are unbundling vessel employment from integrated logistics contracts, creating spot-market exposure for independent shipowners. Commodity traders and agribusiness conglomerates are building in-house freight desks to capture arbitrage between time-charter and voyage-charter rate cycles. This pattern is most visible in dry bulk markets serving Brazilian soybean and Australian coal exports.
Cargo Vessel Market Segmentation
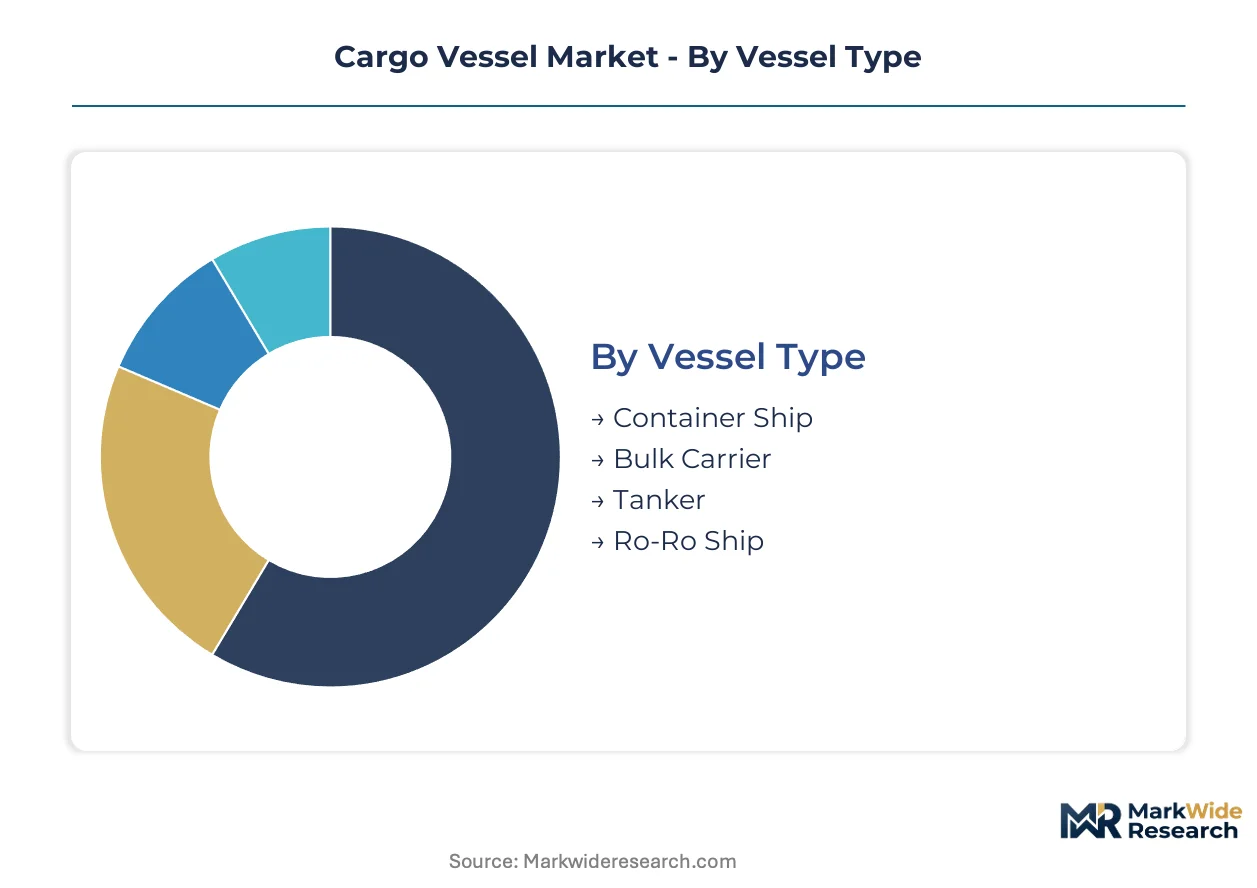
Vessel segmentation dictates procurement economics and yard specialization. Fleet operators align segment selection with route density, cargo mix, and regulatory exposure across flag states.
Vessel Type:
Construction capacity concentrates in South Korean and Chinese shipyards with dedicated slipways for each hull category.
- Container Ship:Standardized TEU slot configurations enable repeat-order economics from integrated logistics carriers. Demand clusters on trans-Pacific and intra-Asian routes serving e-commerce fulfillment networks.
- Bulk Carrier:Capesize and very large ore carrier designs dominate iron ore and coal trades. Brazilian and Australian mining majors lock in long-term charter contracts, stabilizing orderbook visibility for builders.
- Tanker:Crude oil carriers specialize in long-haul routes; product tankers serve refined petroleum distribution.
- Ro-Ro Ship:Vehicle carrier designs accommodate rolling cargo for automotive supply chains.
Container ships absorb the bulk of installed capacity; bulk carriers are expanding most quickly on mining export contract renewals.
Size Category:
Scale thresholds determine port compatibility and slot cost efficiency for terminal operators.
- Small:Feeder vessels serve secondary ports with restricted berth depths.
- Medium:Panamax designs balance canal transit fees against cargo lift.
- Large:Post-Panamax hulls exploit expanded lock infrastructure.
- Very Large:Ultra-large crude carriers and 24,000 TEU boxships maximize unit transport cost reduction on dense routes.
Large vessels command the majority of newbuild capital deployment; very large designs are gaining share fastest on hub-and-spoke network consolidation.
Propulsion Technology:
Engine supply bottlenecks at WinGD and MAN Energy Solutions constrain alternative fuel adoption timelines.
- Diesel:Conventional two-stroke heavy fuel oil systems face IMO Energy Efficiency Existing Ship Index compliance pressure.
- LNG:Dual-fuel architectures dominate near-term orderbooks as EU emissions trading inclusion raises carbon cost exposure.
- Wind-Assisted:Rotor sails and kite systems reduce fuel consumption on favorable trade routes.
- Hybrid:Battery-buffered propulsion optimizes load profiles for coastal feeder operations.
Diesel retains the largest installed base; LNG specifications are climbing the fastest on EU Green Deal maritime provisions.
Application Area:
Charter market unbundling creates spot exposure for independent owners across contract types.
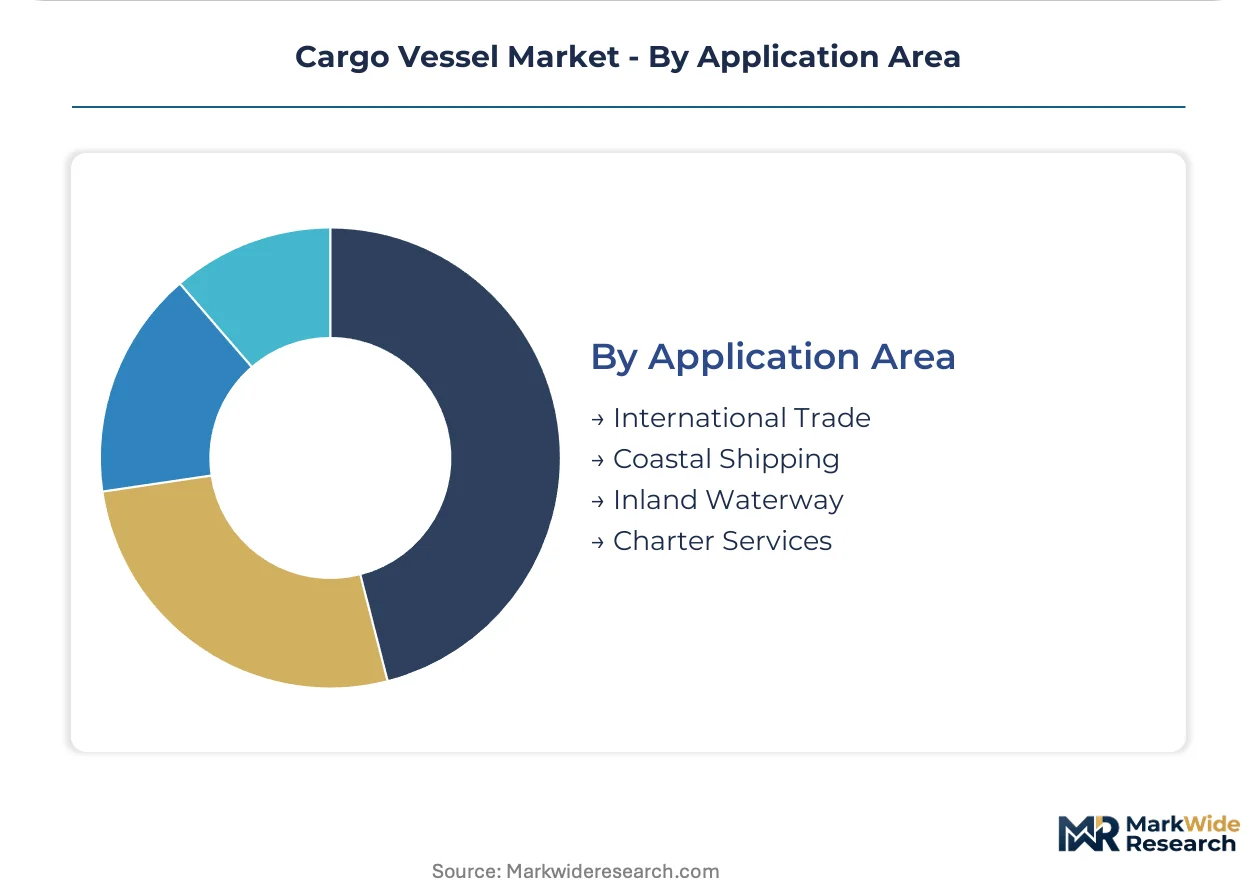
- International Trade:Deep-sea liner services connect manufacturing clusters with consumption markets.
- Coastal Shipping:Domestic cabotage regulations protect national fleet participation in short-sea trades.
- Inland Waterway:Barge designs navigate river systems with draft and bridge clearance constraints.
- Charter Services:Project cargo and spot voyage contracts serve commodity trader freight desks.
International trade absorbs the bulk of fleet tonnage; charter services are expanding most quickly as traders internalize freight operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding capacity concentrates in East Asian industrial clusters while vessel demand originates from commodity export terminals and container hub ports across three continents. Fleet renewal investment flows toward yards with proven dual-fuel construction capabilities.
China
State-owned shipping lines are expanding ultra-large container carrier orders through China State Shipbuilding Corporation's integrated engineering platforms. The Ministry of Ecology and Environment enforces domestic emission control area standards exceeding IMO global sulfur caps at Shanghai, Ningbo, and Shenzhen terminals. Yangtze River delta yards dominate mid-tier bulk carrier construction despite margin pressure from steel plate cost volatility.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor ultra-large container carrier and LNG-ready tanker production for trans-Pacific liner operators. The Korea Shipbuilding & Offshore Engineering holding structure consolidates design resources across DSME and HHI subsidiaries. Busan-Ulsan industrial corridor shipyards specialize in dual-fuel propulsion architectures with advanced containment systems.
Japan
Japanese shipping consortia are contracting ammonia-ready engine specifications through Mitsubishi Heavy Industries for 8,000+ TEU newbuilds. METI-backed floating offshore wind foundation programs generate specialized heavy-lift vessel demand absent from current orderbooks. Nagoya and Kobe maritime engineering clusters focus on precision components for alternative fuel retrofit programs.
Germany
Container feeder operators based in Hamburg and Bremen are retrofitting existing tonnage to meet EU emissions trading system compliance thresholds. The EU Green Deal maritime provisions mandate LNG-ready or methanol-capable specifications for vessels trading European routes. German classification society DNV applies tiered notation systems that directly shape newbuild financing terms.
United States
Jones Act cabotage requirements protect domestic tanker and container vessel construction at General Dynamics NASSCO's San Diego yard. EPA and Coast Guard joint enforcement of ballast water treatment standards accelerates scrapping decisions for older Great Lakes and coastal tonnage. Gulf Coast petrochemical exporters are contracting product tanker newbuilds with methanol dual-fuel options.
Cargo Vessel Market Competitive Landscape
The competitive structure tilts toward consolidated national champions with state-backed financing and integrated engineering platforms. East Asian shipyards command premium contract values through repeat-order relationships with integrated logistics carriers. Two strategic archetypes dominate: diversified heavy industrial conglomerates with captive steel supply, and specialized marine engineering groups focused on alternative fuel containment systems. Capacity expansion and technology licensing represent the dominant competitive moves as engine supply bottlenecks constrain orderbook fulfillment.
Among Korean industrial conglomerates, Hyundai Heavy Industries and Samsung Heavy Industries exemplify the integrated engineering platform archetype, leveraging consolidated design resources across multiple slipway facilities. China State Shipbuilding Corporation occupies a parallel position within the state-backed tier, anchoring government-directed fleet modernization programs through coordinated yard networks. Damen Shipyards Group represents the specialized mid-tier archetype, focusing on standardized vessel families with modular configuration options.
| Leading Market Players |
|---|
| Hyundai Heavy Industries |
| China State Shipbuilding Corporation |
| Mitsubishi Heavy Industries |
| Samsung Heavy Industries |
| Daewoo Shipbuilding & Marine Engineering |
| Korea Shipbuilding & Offshore Engineering |
| Damen Shipyards Group |
| General Dynamics NASSCO |
| Namura Shipbuilding |
| Others |
Value Network & Pricing Analysis
IMO's Energy Efficiency Existing Ship Index gates qualified supply access for Korean and Chinese yards, reserving premium-tier contract pricing for builders with proven dual-fuel construction records while marginalizing legacy heavy fuel oil specialists. This regulatory filter concentrates pricing power among integrated engineering platforms that can certify alternative fuel containment systems.
Pricing Analysis
Margin tightening in mid-tier Chinese yards reflects steel plate cost volatility and compressed repeat-order economics from state-owned shipping lines. Three-tier pricing structure across IMO-certified dual-fuel, LNG-ready, and conventional diesel specifications separates Hyundai Heavy Industries premium contracts from Yangtze River delta standard builds. Cost-down pressure on economy-tier bulk carriers accelerates because Brazilian mining majors demand long-term charter rate visibility. Integrated logistics carriers show least price sensitivity on ultra-large container carrier orders; independent dry bulk owners absorb maximum pricing pressure on spot voyage fixtures.
Supply Chain Analysis
Dual-sourcing mandates from European charterers force Korean and Chinese yards to qualify secondary engine suppliers beyond WinGD and MAN Energy Solutions dominance. Geographic supply concentration centers on South Korea, China, and Japan for hull construction, with Finland and Germany anchoring specialized containment engineering. Raw material dependencies rest on Chinese heavy steel plate, South Korean high-tensile specialty alloys, and German precision engine components. Single-source vulnerability concentrates in two-stroke marine engine manufacturing. Distribution runs through direct yard-to-operator contracting for newbuilds, with broker-mediated secondary markets for resale tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where IMO Carbon Intensity Indicator thresholds erect a barrier-to-entry moat, advantaging incumbent yards with certified dual-fuel portfolios and stranding conventional diesel specialists.
For Market Incumbents: Cement repeat-order relationships with integrated logistics carriers through guaranteed delivery slots for 24,000 TEU ultra-large container carriers. Anchor capacity expansion in Busan-Ulsan industrial corridor to capture EU emissions trading system-driven LNG-ready demand. Defend against Chinese state-backed pricing pressure by deepening certification investment with Lloyd's Register and DNV tiered notation systems. For New Entrants and Emerging Players: The premium-to-economy price gap in methanol-capable tanker specifications creates entry space for specialized containment engineering firms. Target Indian shipbreaking modernization at Alang-Sosiya yards as the most penetrable geography for EU-flagged vessel recycling under Hong Kong Convention. Pursue technology licensing from established containment system specialists rather than greenfield R&D. For Investors and Strategic Acquirers: Extended certification backlogs for dual-fuel system engineers at classification societies is the leading indicator that vessel delivery acceptance delays will concentrate orderbook fulfillment among proven yards. Frame long-term viability around five-to-ten year regulatory compliance windows favoring ammonia-ready engine specifications. Target acquisition profiles at Japanese precision component suppliers for alternative fuel retrofit programs. Watch ammonia fuel cell pilot results from Maersk and CMA CGM as the inflection signal for hydrogen-derived marine fuel commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Propulsion Certification | DNV tiered notation unlocks EU emissions trading compliant financing terms for Korean yards. |
| Backward Integration into Steel Supply | China State Shipbuilding Corporation's captive heavy plate sourcing insulates margin from Yangtze delta volatility. |
| Ammonia-Ready Engine Specification | Mitsubishi Heavy Industries pilots position Japanese consortia for zero-carbon regulatory phase-ins. |
| Alang-Sosiya Recycling Upgrade | Hong Kong Convention compliance captures EU-flagged vessel demolition demand from German owners. |
| Autonomous Navigation Partnership | Machine learning route optimization enables reduced-crew coastal feeder operations for Singapore terminal links. |
Research Methodology
Multi-period observation of orderbook composition, delivery schedules, and classification society certification backlogs anchored the trend analysis, supplemented by interviews with shipyard procurement directors, marine engineering consultants, chartering executives at commodity trading houses, and classification society surveyors. Secondary validation drew from Lloyd's Register statistical reports, DNV maritime forecast publications, UNCTAD Review of Maritime Transport, and customs trade data on steel plate imports. Bottom-up vessel-type demand modeling and top-down fleet replacement cycle analysis provided triangulation.
Input-output matrices mapped propulsion technology adoption rates against regulatory compliance thresholds across the projection horizon. Segmentation dimensions modeled included vessel type, size category, propulsion architecture, and application area, with regional regulatory cluster as the industry-specific overlay. CAGRs derived from fleet age distribution analysis and replacement cost economics. Industry-specific forecast inputs incorporated IMO enforcement consistency patterns and alternative fuel production capacity buildout timelines.
Inputs from classification society delivery acceptance records and shipyard orderbook disclosures were available through the study window; gaps in retroactive fuel consumption monitoring data introduce uncertainty bands around carbon intensity compliance projections. Deviation in EU emissions trading system enforcement stringency or green methanol supply scaling would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Air-Cushion Vehicle Market