
 Car Audio Market | 2026-2036
Car Audio Market Size, Share, and Industry Trends Forecast 2026-2036
Car Audio Market Analysis
Aluminum voice-coil formers is rebalancing thermal performance against copper in high-output speaker designs, cutting weight while maintaining power handling. Pioneer leverages its aftermarket channel density to sustain install-base loyalty across North America and Asia. Harman International Industries anchors premium OEM contracts with Mercedes-Benz and BMW through branded audio systems. Bose differentiates via active noise cancellation integrated into factory head units.
Car audio encompasses electromechanical transducers, signal processors, and amplification modules engineered to reproduce sound within vehicle cabins constrained by acoustic reflection, vibration, and ambient noise. Systems typically operate across 20 Hz to 20 kHz frequency response with multi-channel DSP calibration to compensate for glass and plastic interior surfaces. Head units and smart audio technology command the highest margin pools as software-defined audio architectures displace fixed-function hardware. Aftermarket speakers and amplifiers retain volume leadership but face compression from factory-installed upgrade packages.
FCC governs wireless transmission protocols including Bluetooth and satellite radio frequency allocations in the United States, while Ecodesign requirements under EU regulations mandate standby power limits for automotive electronics. Japan's METI sets efficiency benchmarks that shape amplifier topology selection for export-bound suppliers. Stakeholders must monitor how software-updateable audio platforms alter replacement cycles and intellectual property licensing structures.
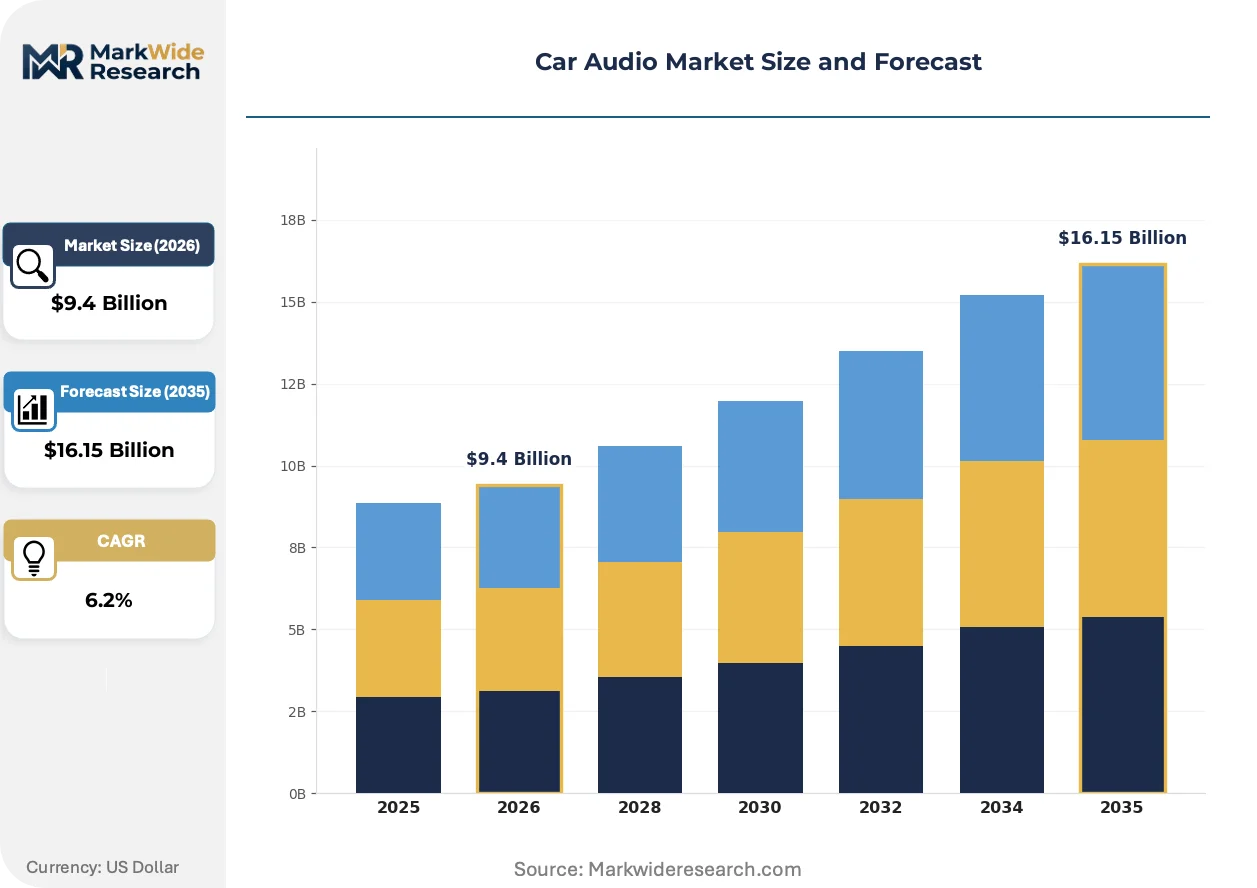
Market Dynamics
Software-defined audio architectures are compressing hardware replacement cycles as OEMs push over-the-air updates to extend system lifespans, forcing aftermarket suppliers to reposition around installation services and acoustic customization.
Growth Catalysts
- EU Ecodesign standby power limits:These regulations mandate sub-watt standby consumption for automotive electronics, accelerating Class-D amplifier adoption and creating upgrade demand for legacy Class-AB systems in vehicle parcs.
- Extended vehicle lifespans:Consumers retain vehicles beyond 12 years on average in the United States, generating sustained aftermarket speaker and head-unit replacement cycles independent of new-car sales.
- Aluminum voice-coil formers:This material transition cuts moving mass by 30-40% versus copper while maintaining thermal dissipation, enabling higher output from compact enclosures in cabin-constrained installations.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium sourcing clusters in China creates price volatility and forced substitution to ferrite magnets in entry-level speaker lines, degrading sensitivity specifications.
- FCC Part 15 emissions compliance:Wireless audio modules face stringent unintentional radiator testing, extending certification timelines and freezing small-batch aftermarket releases.
- Factory-installed premium audio packages:Branded OEM systems from Harman and Bose capture upgrade spend at point-of-sale, compressing aftermarket amplifier and speaker attachment rates.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Production-linked incentives attract component manufacturing, creating localized supply for domestic vehicle production and export to Middle East and Africa.
- Subscription-based DSP tuning:Cloud-hosted acoustic calibration profiles enable recurring revenue from enthusiasts seeking venue-specific sound signatures without hardware swaps.
- Vehicle-to-everything audio integration:Convergence of external sound synthesis for pedestrian warning with cabin audio systems opens unified amplifier architectures for electric vehicle platforms.
Industry Challenges
- Acoustic engineering talent scarcity:DSP calibration and cabin modeling expertise concentrates among aging specialists, constraining product development velocity at mid-tier suppliers.
- Legacy analog head-unit integration:Maintaining compatibility with 20-year-old vehicle electrical architectures while supporting modern digital sources fragments R&D and inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Audio Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speakers, Amplifiers, Subwoofers, Head Units Technology: Bluetooth, Wired, Satellite, Smart Audio Installation Type: OEM, Aftermarket, Custom, Plug-and-Play End User: Individual Consumers, Car Manufacturers, Fleet Operators, Audio Enthusiasts |
| Companies Covered | Bang & Olufsen, Pioneer, Bose, Alpine, Sony, Harman International Industries, Bowers & Wilkins, Meridian Audio, Dynaudio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Audio Market Emerging Trajectories
Digital signal processing is migrating from dedicated hardware to vehicle compute platforms, collapsing traditional amplifier boundaries and forcing audio suppliers to redefine their value around transducer physics and acoustic software.
Beam-steering array speakers are overtaking conventional point-source designs in premium electric vehicles. These systems use phased driver arrays to create spatial audio zones without physical speaker relocation. Mercedes-Benz integrates this architecture in EQS and S-Class platforms. The technology is overtaking multi-channel analog wiring by reducing cable mass and enabling software-configurable sound staging.
Japan's METI energy efficiency benchmarks now govern amplifier topology selection for export-bound suppliers. These standards mandate minimum conversion efficiency thresholds that disqualify linear amplifier classes from new vehicle programs. European OEMs sourcing from Japanese tier-1 suppliers must certify compliance to maintain supply continuity. The regulation accelerates gallium nitride power stage adoption in Class-D designs.
Direct-to-consumer acoustic calibration tools are fragmenting traditional installer channels. Smartphone-based room-correction apps from DSP chip vendors enable end-users to execute parametric equalization without professional installation. This pattern concentrates in Germany and the United States where enthusiast communities drive self-install culture. Retailers respond by unbundling hardware from tuning services, compressing margin pools on entry-level configurations.
Car Audio Market Segmentation
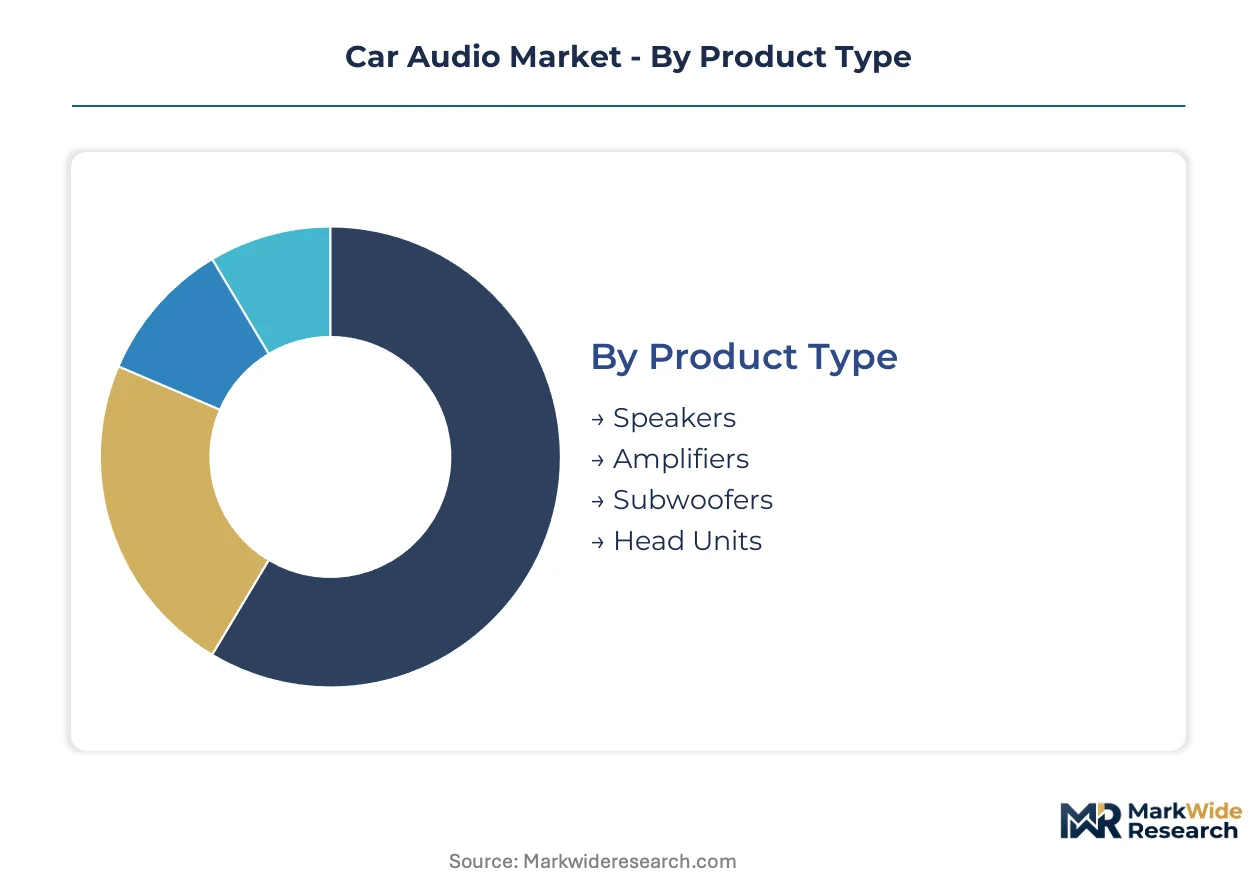
Car audio segmentation reflects divergent supply chain configurations across factory-integrated and consumer-upgrade channels. Component sourcing, certification requirements, and distribution density vary sharply between OEM-specified and aftermarket installation pathways.
Product Type:
Supply concentration clusters around transducer manufacturing in China and amplifier assembly in Mexico, with head-unit production gravitating toward electronics manufacturing services in Taiwan and South Korea.
- Speakers:Electromechanical transducers converting electrical signals to sound pressure waves through cone or dome diaphragms. Demand concentrates in the United States for full-range coaxial replacements in aging vehicle parcs, constrained by rare-earth magnet price volatility from Chinese sourcing clusters.
- Amplifiers:Power electronics modules boosting line-level signals to drive speaker loads. Germany anchors Class-D adoption for EU Ecodesign compliance, with gallium nitride power stages displacing silicon MOSFETs in premium tier designs.
- Subwoofers:Low-frequency specialized drivers operating below 200 Hz.
- Head Units:Central control interfaces integrating source selection, amplification, and display functions.
Speakers absorb the bulk of installed capacity; head units are expanding most quickly as software-defined architectures extend replacement cycles through over-the-air updates.
Technology:
Cost tier stratification separates legacy wired infrastructure from wireless and intelligent systems commanding premium positioning in new vehicle programs.
- Bluetooth:Short-range wireless protocol enabling smartphone audio streaming and hands-free calling. The United States drives specification upgrades through FCC Part 15 emissions mandates, compressing certification timelines for aftermarket module releases.
- Smart Audio:Voice-activated, cloud-connected systems with natural language processing and over-the-air capability. China concentrates demand as domestic EV platforms integrate branded intelligent cockpit experiences.
- Wired:Analog and digital cabled connections including RCA, optical, and USB interfaces.
- Satellite:Subscription-based broadcast radio services requiring dedicated receiver hardware and antenna systems.
Bluetooth dominates current installed base; smart audio is climbing the fastest as OEMs bundle intelligent cockpit experiences into premium trim configurations.
Installation Type:
Customer type fragmentation splits between factory-integrated procurement by vehicle manufacturers and discretionary spending by individual owners seeking acoustic upgrades.
- OEM:Factory-installed systems specified during vehicle design and assembled on production lines. Germany and Japan anchor demand through Mercedes-Benz, BMW, and Toyota branded audio partnerships, with multi-year supply contracts locking amplifier and speaker sourcing.
- Aftermarket:Post-purchase upgrades installed by consumers or specialty retailers. The United States sustains volume through extended vehicle lifespans exceeding twelve years, generating replacement cycles for head units and speakers independent of new-car sales.
- Custom:Bespoke fabricated installations requiring vehicle modification and acoustic treatment.
- Plug-and-Play:Pre-configured modules designed for specific vehicle models without wiring modification.
OEM captures the majority of value pool concentration; aftermarket is gaining share fastest as vehicle parc age extends replacement demand.
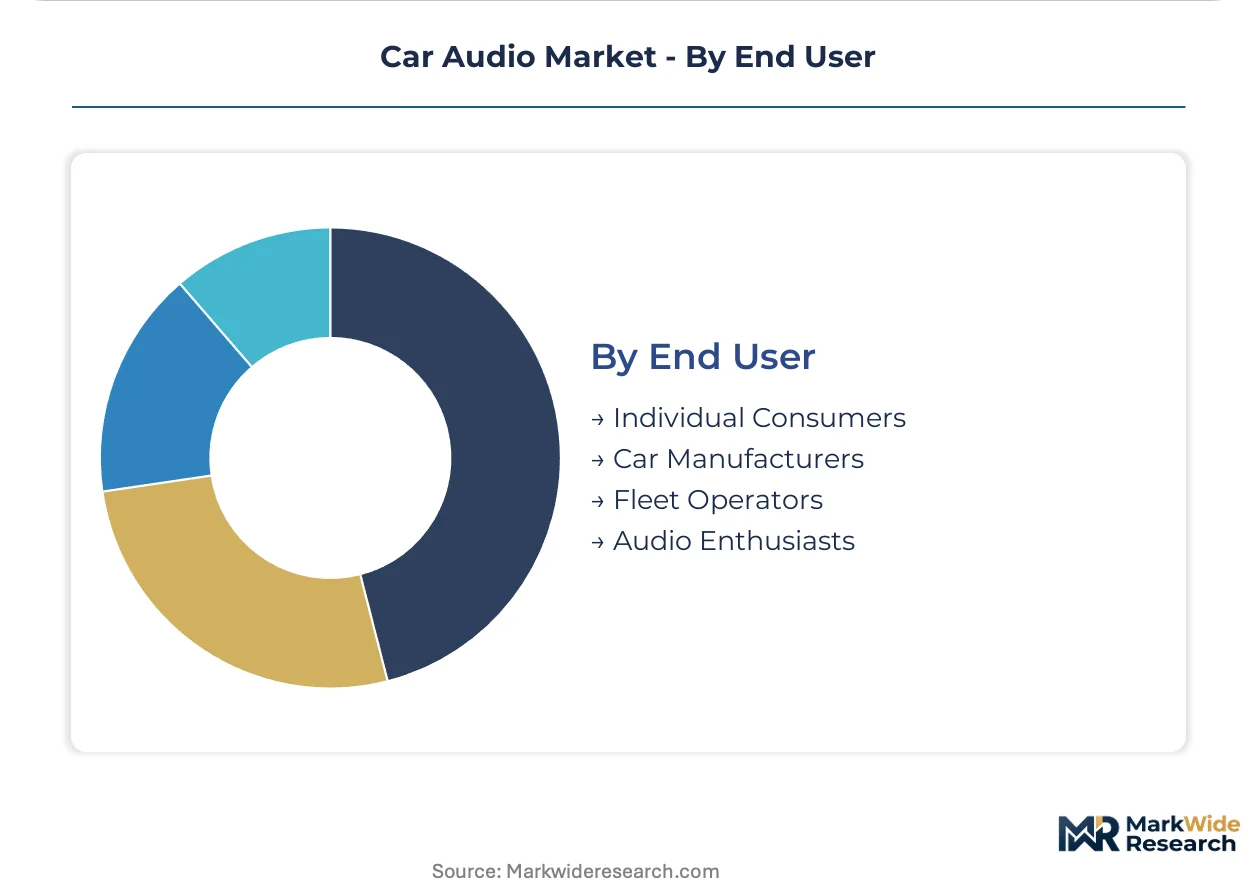
End User:
Application divergence separates individual discretionary spending from fleet-scale procurement and enthusiast-driven premium customization.
- Individual Consumers:Private vehicle owners purchasing replacement or upgrade audio components. The United States concentrates demand for smartphone-integrated head units and Bluetooth-enabled speakers as owners retain vehicles beyond warranty periods.
- Car Manufacturers:OEMs specifying branded audio systems for factory installation. Germany leads through premium contracts with Harman International Industries and Bose for Mercedes-Benz, BMW, and Volkswagen Group platforms.
- Fleet Operators:Commercial vehicle managers procuring standardized audio for delivery, rental, and service fleets.
- Audio Enthusiasts:Hobbyist consumers pursuing high-fidelity or competition-grade installations.
Car manufacturers absorb the bulk of component volume; individual consumers are expanding most quickly as extended vehicle retention drives aftermarket speaker and head-unit replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for car audio systems concentrates in the United States, Germany, and China where premium audio branding drives purchase decisions at both factory and aftermarket stages.
United States
Extended vehicle lifespans exceeding twelve years sustain aftermarket speaker and head-unit replacement cycles independent of new-car sales. FCC Part 15 emissions mandates govern Bluetooth and wireless audio module certification, compressing timelines for small-batch aftermarket releases. Detroit and the broader Midwest manufacturing corridor anchor OEM supply relationships with tier-1 audio suppliers.
Germany
Mercedes-Benz and BMW branded audio partnerships lock multi-year supply contracts for amplifier and speaker sourcing. EU Ecodesign standby power limits mandate sub-watt consumption for automotive electronics, accelerating Class-D amplifier adoption across vehicle programs. Stuttgart and Munich concentrate premium OEM specification engineering and acoustic R&D facilities.
China
Domestic EV platforms integrate branded intelligent cockpit experiences, concentrating demand for smart audio systems with voice activation and cloud connectivity. The country's national electronics regulator enforces GB standards for electromagnetic compatibility in automotive components. Shenzhen and Shanghai anchor electronics manufacturing services for head-unit production serving export markets.
Japan
Toyota and Honda maintain long-standing audio system partnerships with domestic tier-1 suppliers. METI energy efficiency benchmarks govern amplifier topology selection for export-bound suppliers, mandating minimum conversion efficiency thresholds that disqualify linear amplifier classes. Nagoya and the broader Chubu region concentrate automotive electronics assembly for global vehicle programs.
South Korea
Hyundai and Kia integrate premium audio branding into Genesis luxury sub-brand configurations. The country's national automotive safety and standards authority enforces KC certification for electromagnetic emissions in vehicle electronics. Seoul Capital Area anchors R&D centers for DSP chip vendors supplying global audio module manufacturers.
Car Audio Market Vendor Landscape
Multi-year OEM supply contract wins dominate the current landscape as audio suppliers defend install-base positions against factory-installed upgrade packages. The vendor base organizes around three tiers: premium branded system integrators, high-volume amplifier and speaker manufacturers, and specialized DSP software vendors. Two strategic archetypes define competitive positioning: OEM-anchored premium audio houses leveraging vehicle-brand partnerships, and aftermarket-focused suppliers exploiting extended vehicle parc replacement cycles. Contract renewals with Mercedes-Benz, BMW, and Toyota represent the dominant competitive arena, while gallium nitride power stage adoption in Class-D designs marks the critical technology differentiation vector.
Within the premium branded tier, Harman International Industries and Bose exemplify OEM-anchored positioning through multi-year vehicle-brand partnerships, while Pioneer occupies a distinct aftermarket-focused archetype leveraging channel density across North America and Asia. Bang & Olufsen and Bowers & Wilkins represent European-origin premium audio houses competing for luxury vehicle program inclusion. These three archetypes—OEM-contract premium integrators, aftermarket channel specialists, and European luxury audio brands—structure competitive rivalry as software-defined architectures compress hardware replacement cycles and force repositioning around acoustic customization services.
| Leading Market Players |
|---|
| Bang & Olufsen |
| Pioneer |
| Bose |
| Alpine |
| Sony |
| Harman International Industries |
| Bowers & Wilkins |
| Meridian Audio |
| Dynaudio |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign standby power limits gate qualified amplifier supply and premium-tier pricing access, as sub-watt compliance mandates disqualify linear Class-AB designs and concentrate margin capture among gallium nitride-equipped Class-D suppliers serving Mercedes-Benz and BMW programs.
Pricing Analysis
Volume leadership sits with entry-level ferrite-magnet speakers while margin pools concentrate in software-defined head units and DSP-enabled smart audio systems. Three-tier pricing structure across premium, standard, and economy levels separates Harman-branded OEM contracts from aftermarket Pioneer configurations and generic replacement speakers. Cost compression in entry-level transducers is intensifying because Chinese rare-earth magnet price volatility forces ferrite substitution. Fleet operators exhibit highest price sensitivity; audio enthusiasts pursuing competition-grade installations show lowest.
Supply Chain Analysis
Freight cost volatility from China to North America and Europe shapes inventory positioning for neodymium magnet-dependent speaker manufacturers. Transducer production concentrates in China, amplifier assembly in Mexico, and head-unit electronics manufacturing services in Taiwan and South Korea. Rare-earth magnet supply draws from Chinese mining clusters; voice-coil formers source aluminum from Australian smelters; DSP chips rest on Taiwanese foundry capacity. Single-source vulnerability in neodymium creates forced substitution risk. Distribution runs through OEM tier-1 supplier networks and aftermarket specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car audio market sits in a technology-transition phase as software-defined architectures displace fixed-function hardware and compress traditional amplifier replacement cycles.
For Market Incumbents: Extend software-updateable platform roadmaps to defend against over-the-air update cycles that OEMs push to Mercedes-Benz and BMW vehicles, eroding aftermarket attachment rates. Deepen backward integration into gallium nitride power stage sourcing to secure Class-D amplifier cost positions against silicon MOSFET suppliers. For New Entrants and Emerging Players: Launch via direct-to-consumer acoustic calibration apps that fragment traditional installer channels in Germany and the United States, where smartphone-based DSP tuning concentrates among self-install enthusiasts. Target India's PLI scheme for automotive electronics manufacturing to supply domestic EV platforms and Middle East export markets. For Investors and Strategic Acquirers: Gallium nitride power stage adoption in premium Class-D designs is the leading indicator that margin pools are migrating from hardware volume to acoustic software services. Long-term viability favors suppliers with DSP calibration expertise and vehicle-brand partnership access. Watch for subscription-based DSP tuning revenue models as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Audio Platform Investment | Enables over-the-air updates that extend system lifespans and lock OEM supply relationships. |
| Gallium Nitride Power Stage Adoption | Meets METI efficiency benchmarks and EU Ecodesign standby limits for premium tier qualification. |
| Subscription-Based DSP Tuning Launch | Creates recurring revenue from enthusiasts seeking venue-specific acoustic profiles without hardware swaps. |
| India PLI Scheme Manufacturing Footprint | Captures production-linked incentives for automotive electronics serving domestic EV and export demand. |
| Beam-Steering Array Speaker Integration | Reduces cable mass in Mercedes-Benz EQS platforms through phased driver architecture. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with OEM platform engineers, aftermarket distributor operations heads, tier-1 supplier procurement managers, and DSP chip vendor R&D directors. FCC Part 15 emissions databases, EU Ecodesign compliance registries, METI efficiency benchmark publications, and vehicle production databases supplied validation. Bottom-up component demand modeling and top-down OEM program value triangulation cross-checked projections.
Granularity-level modeling ran product type, installation channel, and technology tier across the analysis window, with vehicle class and regional production cluster as automotive-specific dimensions. CAGRs derived from installed base aging curves, replacement cycle frequency, and premium audio package attachment rate trajectories. Rare-earth magnet price volatility assumptions and software-update penetration curves shaped amplifier and head-unit forecasts.
Regulatory timeline shifts, rare-earth supply disruption events, and OEM software platform consolidation are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Electronic Drums Market
Audio Equipment
India Wireless Audio Market
Audio Equipment
Global Automotive Premium Audio System Market
Audio Equipment
United Kingdom Gaming Headset Market
Audio Equipment
India Consumer Speaker Market
Audio Equipment
Monitoring Sound Box for Playing Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
Consumer Audio Market
Audio Equipment
High-End Audiophile Speakers Market
Audio Equipment
North America Gaming Headsets Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Asia-Pacific Wireless Audio Market
Audio Equipment
Smart Audio System Market
Audio Equipment
Global Audio Devices and Components Market
Audio Equipment
Digital a/V Decoder Market
Audio Equipment
Audio Kits Market