
 Braille Book Market | 2026-2036
Braille Book Market Size, Share, and Industry Trends Forecast 2026-2036
Braille Book Market Insights
The European Accessibility Act is expanding the compliance burden for publishers entering the Braille book supply chain, raising capital requirements for embossing equipment and digital-to-tactile conversion workflows. American Printing House for the Blind leverages its Kentucky-based production campus to dominate institutional contracting across U.S. school districts. National Braille Press competes through specialized children's literature catalogs and teacher-training programs. HumanWare anchors the technology frontier with refreshable Braille display integration that bridges static books with dynamic reading systems.
Braille books are tactile reading materials produced through embossing processes that raise dots on paper, PVC, or synthetic fabric substrates according to standardized cell configurations, enabling independent literacy for blind and low-vision individuals. Educational texts command the largest production volume due to sustained funding from government-mandated special education programs, while children's books represent the fastest-growing category as early-intervention reading initiatives expand. PVC and durable plastics are displacing traditional paper in high-use environments such as school libraries, where material longevity directly affects replacement cycles and total cost of ownership.
The U.S. Department of Education, through the Individuals with Disabilities Education Act, shapes demand patterns by specifying accessible-format procurement quotas for federally funded schools. Health Canada and the country's national accessibility regulator enforce comparable production standards for materials distributed through Canadian provincial education systems. Publishers must monitor evolving national accessibility mandates as governments tighten enforcement timelines and expand covered product categories beyond traditional print formats.
Market Dynamics
The Individuals with Disabilities Education Act locks in institutional procurement quotas for embossed educational materials, while the European Accessibility Act forces publishers to retool production workflows for tactile formats.
Growth Catalysts
- IDEA Funding Mandates:Federal special education appropriations in the United States guarantee baseline volume for educational Braille texts across K-12 districts.
- REACH Compliance Pathways:European chemical safety standards for embossing substrates are accelerating PVC and synthetic material adoption over cellulose paper.
- Early-Intervention Literacy Programs:Pediatric ophthalmology networks in Canada are expanding newborn screening protocols, creating downstream demand for children's tactile books.
Market Restraints
- Embossing Equipment Capital Intensity:Industrial-grade thermoforming presses for PVC substrate processing require seven-figure capital commitments, concentrating supply among established producers.
- Skilled Transcription Bottlenecks:Certified Braille transcriptionists command premium wages in the United States and Germany, limiting production scaling velocity.
- Refreshable Display Substitution:HumanWare and Orbit Research electro-mechanical Braille terminals compete for the same institutional budgets as static embossed books.
Strategic Opportunities
- Canadian Provincial Expansion:Health Canada accessibility enforcement timelines lag European and American counterparts, creating first-mover windows for compliant publishers.
- Teacher-Training Certification Bundles:Professional development credits tied to tactile literacy instruction represent attach-rate opportunities for curriculum providers.
- Digital-to-Tactile Workflow Convergence:XML-first publishing pipelines married to automated embossing control systems compress pre-production cycles from weeks to days.
Industry Challenges
- Unified English Braille Transition Friction:The 2016 UEB code revision forced publishers to maintain dual-format inventories during the multi-year changeover period.
- Substrate Supply Chain Reconfiguration:European paper mills exiting specialty grades for PVC and synthetic alternatives require embossers to qualify new material vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braille Book Market |
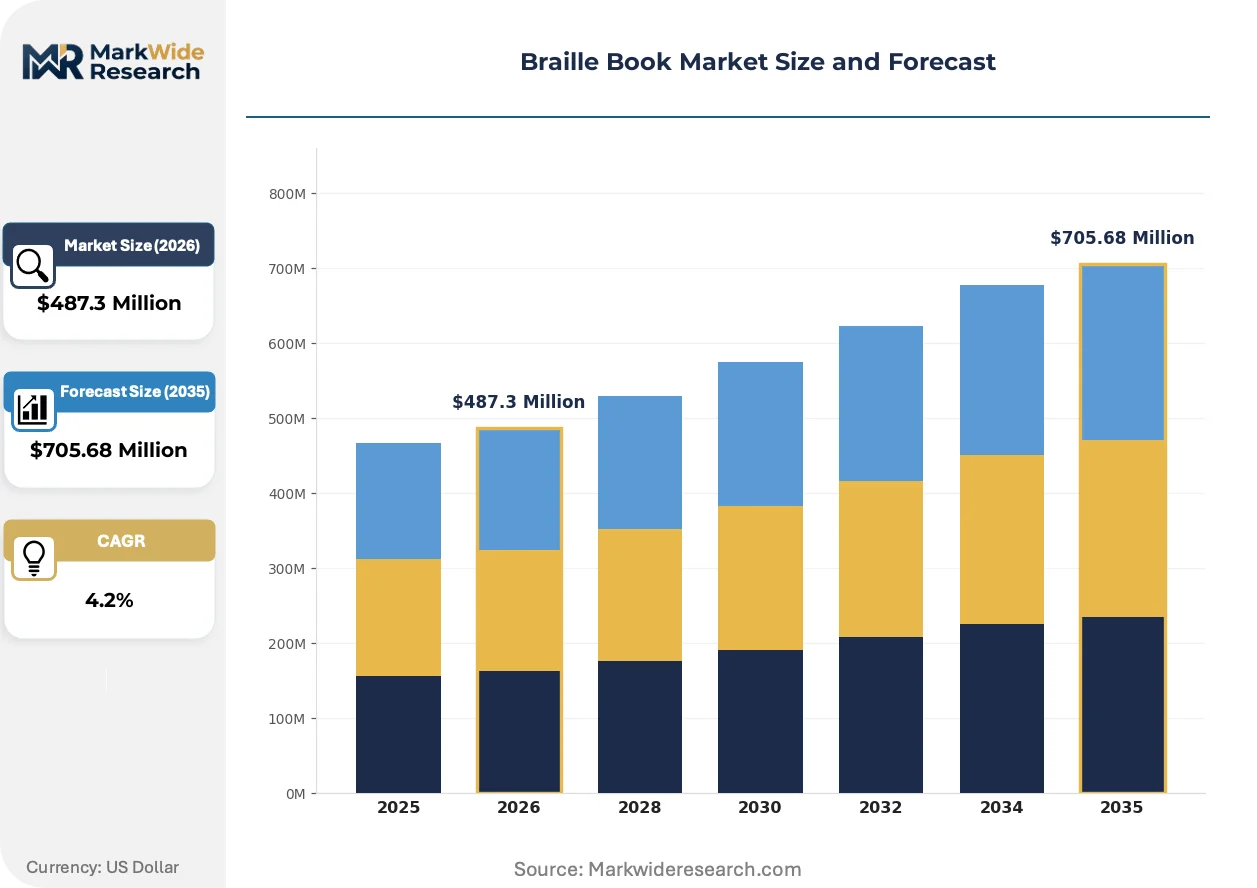
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $705.68 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Children's Books, Educational Texts, Novels, Reference Material Application: Schools, Libraries, Nonprofits, Home Learning Material: PVC, Paper, Synthetic Fabric, Durable Plastics End User: Students, Educators, Adults, Organizations |
| Companies Covered | National Braille Press, American Printing House for the Blind, HumanWare, Royal National Institute of Blind People, Perkins School for the Blind, Braille Institute, Seedlings Braille Books for Children, Clovernook Center for the Blind, Canadian National Institute for the Blind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braille Book Market Trends and Innovations
Production technology is fragmenting into modular components while regulatory pressure intensifies across North America and Europe, and institutional procurement patterns are compressing vendor selection cycles.
Automated embossing control software is modularizing pre-production workflows for educational publishers. Kentucky-based production campuses serving U.S. school districts are adopting these systems fastest, driven by IDEA-mandated delivery timelines. This modularization is compressing the gap between digital manuscript acceptance and physical book shipment from six weeks to under ten days.
The European Accessibility Act enforcement timeline is hardening production standards for any publisher distributing in EU member states. Non-compliant titles face market withdrawal penalties after the 2025 deadline. Educational imprints with cross-border distribution are absorbing certification costs earliest, while trade publishers lag in workflow adaptation.
Aggregated district-level procurement through state cooperative purchasing agreements is consolidating vendor pools for American K-12 systems. National Braille Press and regional competitors now compete through RFP response speed rather than catalog breadth alone. Texas and California education departments are piloting the most centralized buying frameworks, forcing smaller embossers to subcontract through prime vendors.
Braille Book Market Segmentation
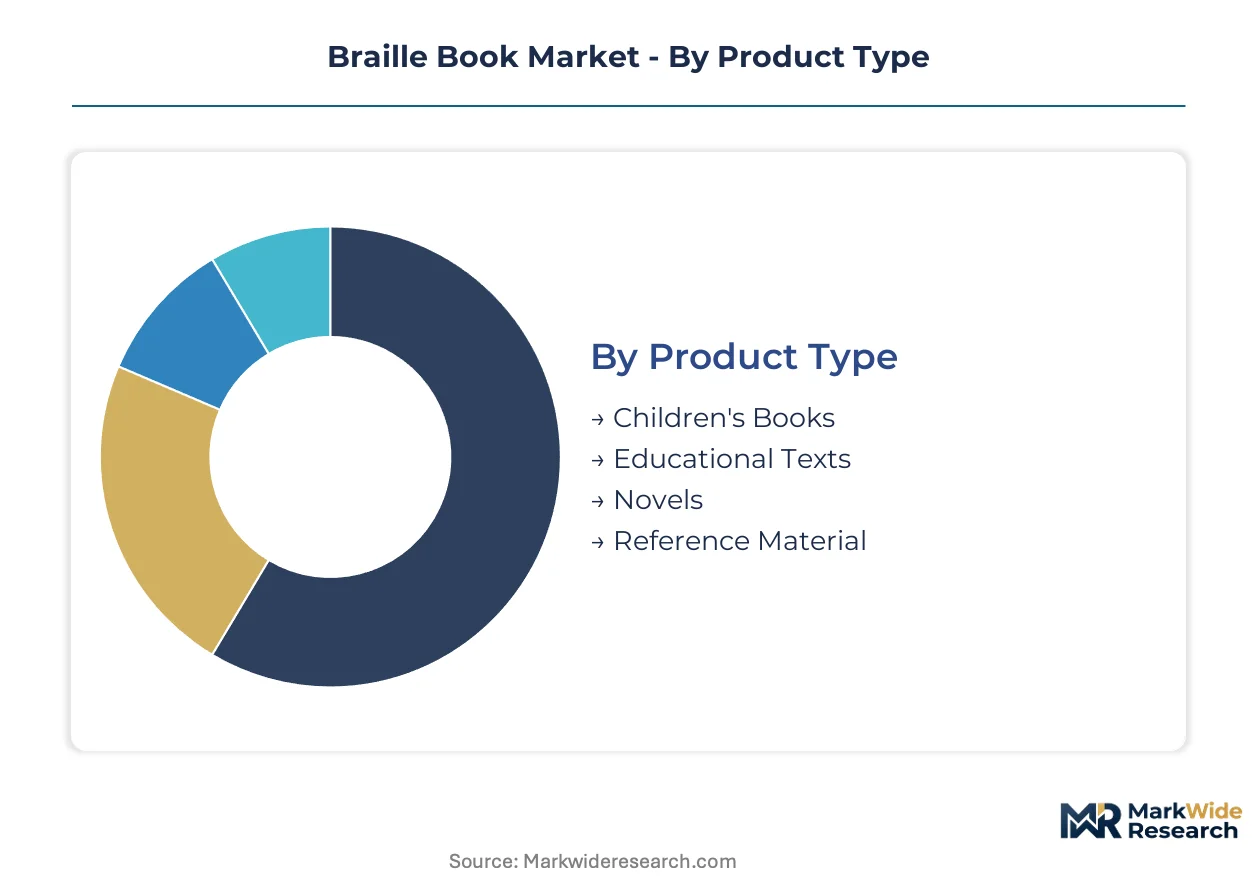
Segmentation in the Braille book market reveals how substrate durability, institutional procurement channels, and reader lifecycle stages create distinct production requirements. Publishers configure embossing workflows differently for each category, with material selection and transcription complexity driving cost structures.
Product Type:
Standardization dominates educational texts through federal procurement specifications, while children's books demand customized tactile illustrations and interactive elements that resist workflow automation.
- Educational Texts:Curriculum-aligned content follows strict formatting protocols mandated by the Individuals with Disabilities Education Act. K-12 districts in Texas and California account for concentrated volume through state cooperative purchasing agreements, with delivery timelines compressing vendor selection cycles.
- Children's Books:Tactile graphics and multisensory page elements require specialized transcription workflows that resist automation. Pediatric ophthalmology networks in Canada are expanding newborn screening protocols, creating downstream demand for early-intervention reading materials.
- Novels:Trade fiction and literary works serve adult readers through library distribution channels, with production runs typically smaller than educational contracts.
- Reference Material:Technical manuals and professional reference works demand precise Braille mathematics and scientific notation transcription.
Most installed capacity flows through Educational Texts. Expansion is steepest in Children's Books.
Application:
Volume concentration shifts from institutional buyers toward individual households as remote learning infrastructure matures and home embossing technology becomes accessible.
- Schools:Federally funded K-12 systems under the Individuals with Disabilities Education Act generate predictable baseline demand through specified accessible-format procurement quotas. Kentucky-based production campuses leverage proximity to institutional buyers for fulfillment speed.
- Libraries:Public lending collections prioritize PVC and durable plastic substrates to withstand high-circulation environments where replacement cycles directly affect total cost of ownership.
- Nonprofits:Mission-driven distributors often subsidize production costs for underserved reader populations, bridging gaps in government-funded access.
- Home Learning:Individual households purchase direct-to-consumer titles through specialized catalogs, with National Braille Press competing through teacher-training program bundling.
Schools absorb the majority of embossing output. Home Learning is climbing the fastest as assistive technology literacy spreads.
Material:
REACH compliance pathways are accelerating substrate transitions, with chemical safety standards for embossing materials favoring synthetic alternatives over traditional cellulose stocks.
- PVC:Thermoformed polyvinyl chloride sheets deliver superior durability in high-use environments, with European paper mills exiting specialty grades and forcing embossers to qualify new vendors. Industrial-grade presses for PVC processing require substantial capital commitments that concentrate supply.
- Durable Plastics:Engineered polymer substrates balance tactile feedback with longevity, gaining preference in school libraries where material lifespan determines replacement economics.
- Paper:Traditional cellulose stocks remain cost-competitive for low-circulation titles and personal collections where durability requirements are modest.
- Synthetic Fabric:Textile-based substrates serve specialized applications requiring washability or extreme flexibility, though production complexity limits scale.
Most embossing volume now flows through PVC. Durable Plastics are gaining share fastest as REACH enforcement tightens.
End User:
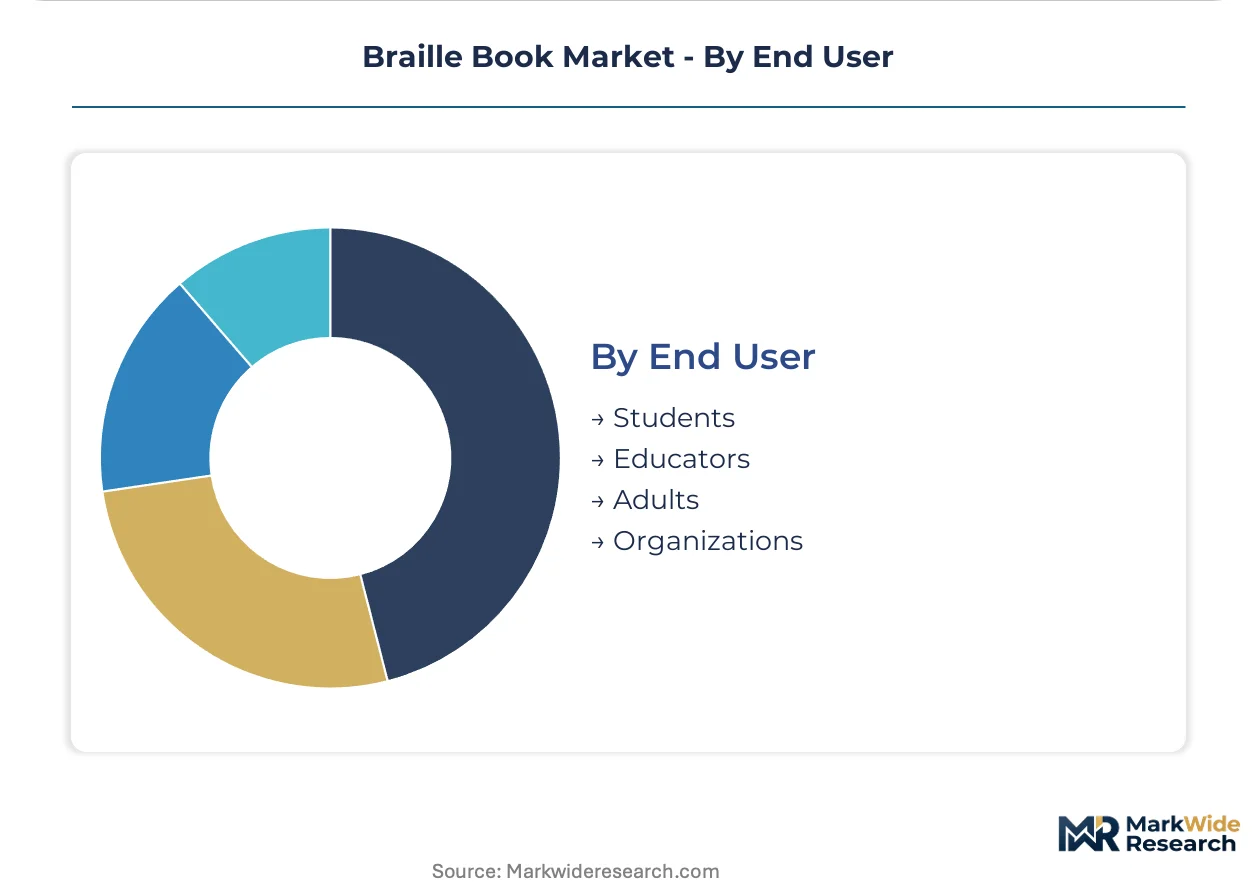
Procurement authority separates institutional buyers with mandated purchasing power from individual consumers whose acquisition decisions respond to price sensitivity and format preference.
- Students:K-12 and postsecondary learners receive materials through federally mandated accessible-format programs, with the Individuals with Disabilities Education Act locking in procurement quotas.
- Educators:Teachers and specialists require professional development materials and curriculum guides, representing attach-rate opportunities for certification bundling.
- Adults:Working-age and senior readers access leisure and professional content through library systems and direct purchase, with refreshable Braille displays competing for the same budgets.
- Organizations:Employers, rehabilitation centers, and advocacy groups acquire materials for program delivery, often through bulk contracting arrangements.
Students command the largest production allocation. Adults represent the steepest expansion trajectory as late-onset vision loss populations grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified Braille transcriptionists cluster in Kentucky, Massachusetts, and Toronto, anchoring North American production capacity. European embossing specialists concentrate around London and Paris, while Pacific Rim activity remains nascent.
United States
Federal IDEA appropriations lock in institutional procurement quotas across K-12 districts. The Department of Education enforces accessible-format specifications through state cooperative purchasing agreements. Kentucky-based production campuses leverage proximity to Midwestern school systems for fulfillment velocity.
Canada
Health Canada accessibility enforcement timelines lag American counterparts, creating first-mover windows for compliant publishers. Provincial education ministries mandate production standards comparable to U.S. federal specifications. Toronto clusters transcription expertise serving Ontario and Quebec school systems.
Germany
REACH chemical safety standards accelerate PVC substrate adoption over traditional cellulose stocks. ECHA compliance pathways reshape embossing material qualification requirements. Industrial thermoforming capacity concentrates in Baden-Württemberg for synthetic substrate processing.
United Kingdom
The European Accessibility Act mandates publishers to provide accessible formats, reshaping production standards for cross-border distribution. London anchors transcription expertise and institutional procurement coordination. Royal charter organizations maintain legacy embossing infrastructure alongside digital conversion workflows.
France
ANSM accessibility enforcement tightens production certification timelines for educational materials. Paris-based transcription networks serve francophone institutional buyers across multiple jurisdictions. Specialty paper mills in the Île-de-France region are exiting Braille-grade cellulose stocks.
Braille Book Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across institutional and consumer channels. The vendor base separates into three tiers: federally contracted embossers serving K-12 systems, mission-driven nonprofits subsidizing underserved populations, and technology integrators bridging static books with dynamic displays. Consolidation pressures concentrate supply among established producers with seven-figure capital equipment. Strategic moves center on automated workflow adoption and geographic expansion into lagging regulatory jurisdictions.
Within the federally contracted tier, American Printing House for the Blind and National Braille Press exemplify divergent positioning strategies. American Printing House for the Blind anchors Kentucky-based production capacity serving U.S. school districts through IDEA-mandated procurement channels. National Braille Press occupies a specialization position in children's literature and teacher-training program bundling. HumanWare represents the technology-integrator archetype, bridging embossed materials with refreshable display systems for institutional budget competition.
| Leading Market Players |
|---|
| National Braille Press |
| American Printing House for the Blind |
| HumanWare |
| Royal National Institute of Blind People |
| Perkins School for the Blind |
| Braille Institute |
| Seedlings Braille Books for Children |
| Clovernook Center for the Blind |
| Canadian National Institute for the Blind |
| Others |
Pricing and Supply Chain Analysis
Captive embossing capacity in Kentucky and Massachusetts anchors supply positioning and pricing power for federally contracted producers serving IDEA-mandated procurement channels. This geographic concentration of thermoforming infrastructure and certified transcription labor creates natural pricing corridors that smaller competitors cannot breach without substantial capital commitments.
Pricing Analysis
Bundled teacher-training certification packages separate National Braille Press pricing from unbundled transactional embossing rates offered by regional competitors. Three-tier pricing structure across premium PVC substrates, standard durable plastics, and economy paper grades reflects material longevity and REACH compliance certification levels. Cost compression in economy paper tiers intensifies because European mill exits are forcing vendor qualification expenses onto smaller embossers. School districts under state cooperative purchasing agreements exhibit lowest price sensitivity, while individual household buyers in the Home Learning segment drive hardest bargain.
Supply Chain Analysis
REACH and IDEA certification gating restricts qualified substrate supply to established embossers with documented compliance histories. Production concentrates in the United States, Canada, and Germany where transcriptionist certification programs and federal procurement specifications align. Raw material flows draw from PVC resin suppliers, specialty polymer compounders, and dwindling European paper mills producing Braille-grade cellulose. Single-source vulnerability runs through German thermoforming press manufacturers whose order backlogs extend equipment delivery timelines. Distribution runs through state cooperative purchasing agreements, direct institutional contracting, and specialized nonprofit catalogs serving underserved populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Braille Book Market functions as a stable compounder where federally mandated procurement quotas through IDEA and comparable international statutes generate predictable demand baselines resistant to cyclical downturn.
For Market Incumbents: Anchor defensive positioning through backward integration into PVC substrate compounding to escape European paper mill supply volatility. Lock in transcriptionist pipeline partnerships with Kentucky and Toronto certification programs to preempt skilled labor competition from refreshable display manufacturers. Prioritize automated embossing control software deployment to compress RFP response cycles below ten days, matching Texas and California procurement velocity requirements. For New Entrants and Emerging Players: Launch via provincial education ministry contracting in Canadian markets where Health Canada enforcement timelines lag American and European counterparts. Target children's tactile literature segments where specialized illustration workflows resist automation and incumbent capacity concentrates on standardized educational texts. Pursue teacher-training certification bundling as attach-rate mechanism to bypass pure price competition against established embossers. For Investors and Strategic Acquirers: Roll-up economics work for regional embossers with captive transcription networks because IDEA-mandated procurement quotas create predictable revenue baselines and customer switching costs are reinforced by certification compliance requirements. Over the medium-term horizon, acquisition targets should display established federal contracting relationships and qualified PVC substrate workflows. Monitor refreshable Braille display price-performance curves as inflection signal; terminal cost parity with embossed book production would redirect institutional budgets toward HumanWare and Orbit Research electro-mechanical systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Embossing Control Deployment | Kentucky-based production campuses compress pre-production cycles from six weeks to under ten days. |
| REACH-Compliant Substrate Qualification | European paper mill exits force embossers to certify PVC and synthetic polymer vendors under ECHA pathways. |
| Teacher-Training Certification Bundling | National Braille Press attaches professional development credits to curriculum procurement for margin protection. |
| Provincial Expansion into Canada | Health Canada enforcement lag creates first-mover windows for compliant publishers in Ontario and Quebec. |
| Refreshable Display Integration | HumanWare bridges static embossed books with dynamic reading systems for institutional budget competition. |
Research Methodology
Bottom-up institutional procurement modeling reconciled against top-down embossing capacity tracking forms the analytical core of this study. Primary interviews with Braille transcription program directors, special education procurement officers at Texas and California education departments, PVC substrate suppliers, and assistive technology distributors combined with secondary validation from IDEA funding appropriations records, Health Canada accessibility enforcement documentation, ECHA REACH compliance filings, and state cooperative purchasing agreement databases. Triangulation between demand-side quota specifications and supply-side equipment installation records ensures volume estimates align with observed production constraints.
Input-output matrices map transcriptionist labor availability, thermoforming press capacity, and substrate material flows against federally mandated delivery timelines across the projection horizon. Segmentation dimensions include product type, application channel, material substrate, and end-user category with additional modeling of certification tier and geographic regulatory cluster. CAGRs derive from compound growth trajectories anchored to IDEA funding trajectories and European Accessibility Act enforcement phase-ins. Forecast inputs incorporate REACH substrate transition timelines and refreshable display price-performance substitution thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unified Braille code revision scenarios or accelerated refreshable display cost reduction. Projections reflect documented assumptions regarding federal appropriation continuity and transcriptionist certification program throughput. A model refresh is warranted upon material change in IDEA funding levels or European Accessibility Act penalty enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Online Tutoring Software Market
Education & Training
Cloud Based Language Learning Market
Education & Training
Digital Course Recorder Market
Education & Training
Middle East and Africa Management Consulting Services Market
Education & Training
Leadership Development Program Market
Education & Training
Europe Corporate Training Market
Education & Training
Asia-Pacific Learning Management Systems Market
Education & Training
Global Digital English Language Learning Market
Education & Training
HR Professional Services Market
Education & Training
Europe Digital Education Market
Education & Training
Artificial Intelligence (AI) in Education Market
Education & Training
University Management System Market
Education & Training
Firefighter Simulator Training Services Market
Education & Training
Global Alumni Management Software Market
Education & Training
Academic Scheduling Software Market
Education & Training
Online Tutoring Services Market