
 Blockchain Technology Market | 2026-2036
Blockchain Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Technology Market Analysis
North American mining infrastructure is pivoting toward renewable-powered data centers as power costs reshape site selection economics. Core Scientific leverages its vertically integrated hosting model to sustain operational scale across multiple states. Coinbase Global anchors institutional on-ramp services through regulatory licensing depth. Block competes on consumer payment integration, while Galaxy Digital differentiates through prime brokerage and asset management specialization.
Blockchain technology constitutes a distributed ledger architecture using cryptographic hashing, consensus mechanisms, and immutable block chaining to validate transactions without centralized intermediaries. Public cloud deployment dominates enterprise adoption due to elastic compute requirements for node operations and smart contract execution. Supply chain management applications are maturing fastest as Walmart and Maersk-style provenance tracking proves ROI. Private cloud configurations capture margin pools in financial services, where Hyperledger and Corda implementations satisfy data residency mandates.
The SEC enforces securities classification for digital assets, while the EU's MiCA framework standardizes stablecoin reserves and exchange custody requirements across member states. FINRA compliance obligations shape how broker-dealers structure blockchain-based settlement products. Stakeholders must monitor evolving central bank digital currency pilots and their interoperability standards to anticipate infrastructure displacement risks.
Market Dynamics
Cross-border settlement infrastructure is forcing wholesale redesign of custody and clearing architectures as financial institutions migrate from legacy correspondent banking to distributed ledger rails.
Growth Catalysts
- MiCA Framework:The EU's Markets in Crypto-Assets regulation mandates standardized reserve requirements for stablecoin issuers, accelerating institutional participation across eurozone capital markets.
- Supply Chain Provenance:Retail and logistics operators deploy Hyperledger Fabric implementations to satisfy Walmart-style traceability mandates from upstream agricultural suppliers.
- Renewable-Powered Mining:Texas and Wyoming data center clusters leverage stranded wind assets to achieve sub-$0.04/kWh operational economics for proof-of-stake validation infrastructure.
Market Restraints
- SEC Securities Classification:The US regulator's enforcement posture against unregistered token offerings creates legal friction for DeFi protocol developers and exchange listings.
- Specialized Talent Scarcity:Smart contract auditing and zero-knowledge cryptography expertise concentrates in Tel Aviv, Berlin, and Singapore, inflating compensation costs for distributed teams.
- Interoperability Fragmentation:Competing layer-1 consensus mechanisms and bridge protocols expose users to technical risk without dominant cross-chain standards emerging.
Strategic Opportunities
- Central Bank Digital Currency Pilots:The European Central Bank's digital euro experimentation creates infrastructure displacement potential for wholesale payment incumbents.
- Tokenized Real Assets:Singapore and Dubai regulatory sandboxes permit fractionalized commodity and real estate instruments, opening retail access to previously illiquid categories.
- Zero-Knowledge Convergence:Integration of zk-SNARKs with enterprise Ethereum implementations enables privacy-preserving compliance for healthcare and financial data sharing.
Industry Challenges
- Legacy System Integration:Core banking platforms from the 1990s require expensive middleware development to connect with blockchain settlement layers without operational disruption.
- Certification Timeline Compression:FINRA broker-dealer licensing for digital asset custody extends 18-24 months, delaying product launches against faster-moving unregulated competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Technology Market |
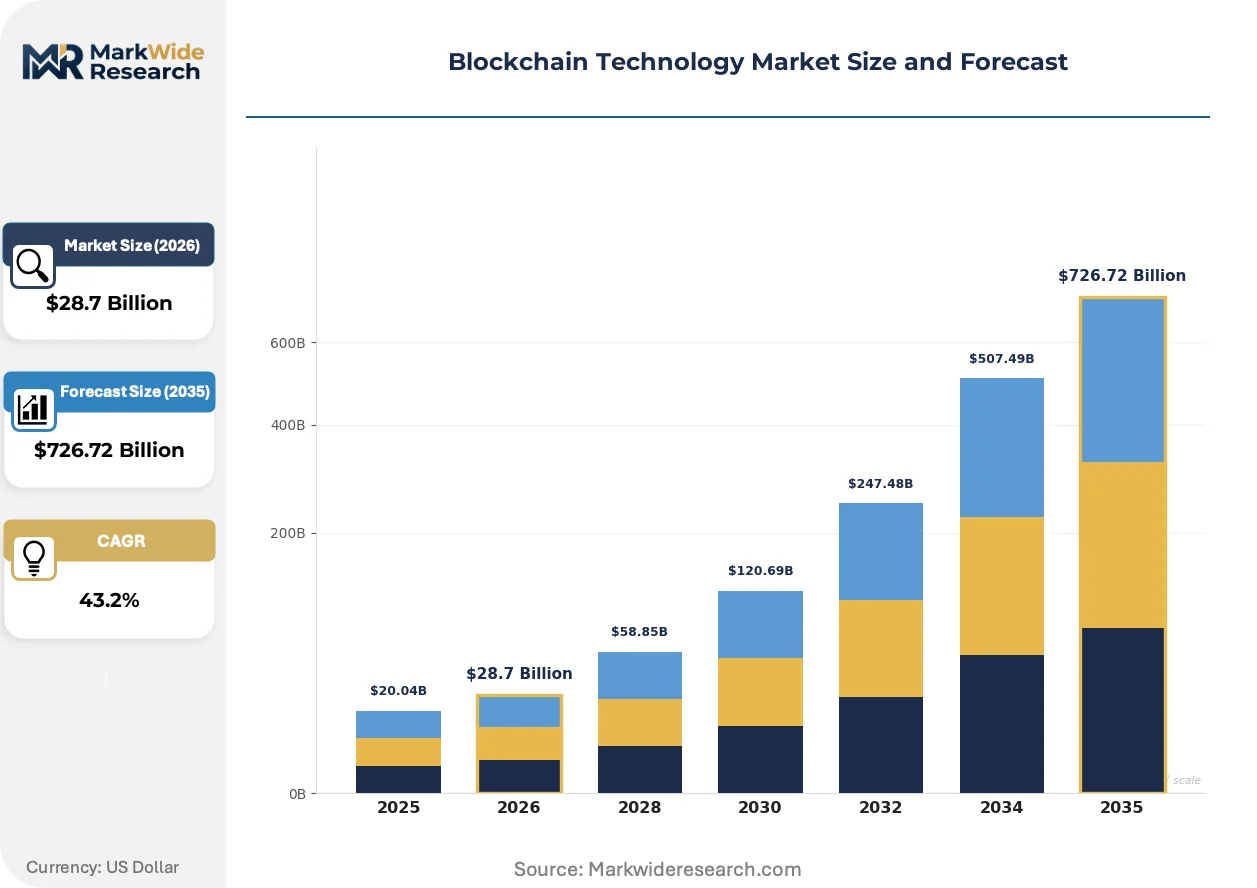
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $726.72 Billion |
| CAGR (2026 – 2036) | 43.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cryptocurrency, Smart Contracts, Supply Chain Management, Identity Verification End User: Financial Services, Healthcare, Government, Retail Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: Ethereum, Hyperledger, Corda, Ripple |
| Companies Covered | Core Scientific, ScienceSoft, Coinbase Global, PixelPlex, LeewayHertz, Block, Galaxy Digital, Blockstream, Ripple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Technology Market Emerging Trajectories
Modular blockchain architectures are fragmenting monolithic layer-1 dominance as specialized execution, data availability, and settlement layers recombine into optimized stacks.
Zero-knowledge rollup technology is consolidating transaction execution away from base layer congestion. Ethereum mainnet fees above $20 per swap during peak demand drive DeFi protocols toward Arbitrum and Optimism deployments. This compression is consolidating liquidity into fewer high-throughput environments while fragmenting composability across execution domains.
The EU's AI Act introduces algorithmic audit requirements for automated smart contract systems deployed at scale. Financial services firms must document decision logic for lending and trading protocols. German and French banks are responding by segregating high-risk algorithmic functions from core blockchain infrastructure to limit liability exposure.
Institutional procurement of blockchain infrastructure is rotating toward managed service contracts with explicit SLA guarantees. Asset managers and pension funds reject self-custody operational risk, instead contracting Coinbase Prime and Anchorage Digital for institutional-grade cold storage. This shift is most visible in United States retirement plan administrators seeking SEC-qualified custodian protections.
Blockchain Technology Market Segmentation
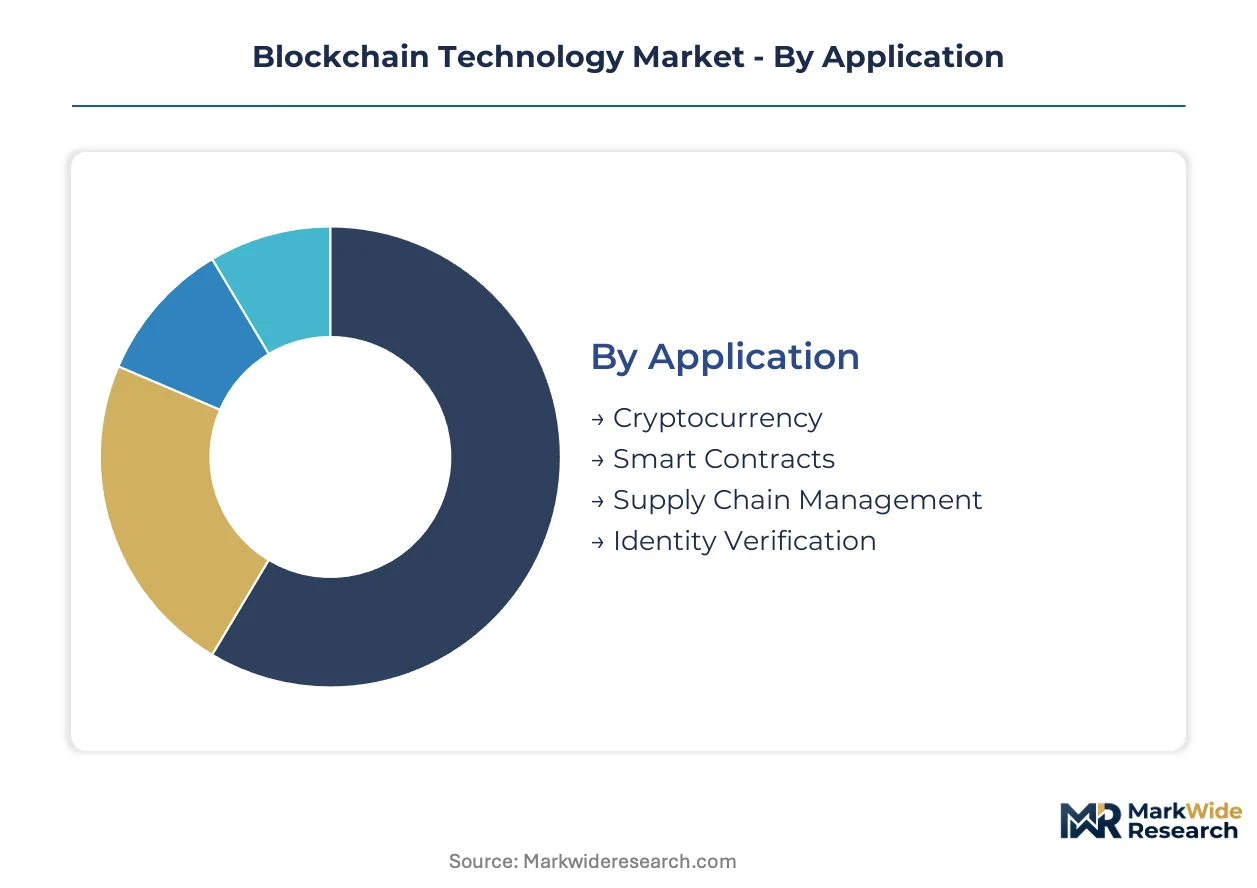
Blockchain technology exhibits heterogeneous deployment patterns across application domains, with infrastructure choices tightly coupled to regulatory exposure and data sovereignty requirements. Segmentation reveals how consensus mechanisms, cloud architectures, and vertical use cases partition addressable value pools.
Application:
Cryptographic validation methods and ledger immutability requirements vary substantially across functional use cases, driving divergent platform selection and integration complexity.
- Cryptocurrency:Native digital asset issuance and peer-to-peer transfer rely on proof-of-stake or proof-of-work consensus with settlement finality measured in block confirmations. Demand concentrates in United States exchange infrastructure and El Salvador's sovereign adoption framework, constrained by SEC securities classification enforcement and treasury reserve accounting standards.
- Smart Contracts:Self-executing code deployed on Ethereum Virtual Machine-compatible chains automates escrow, lending, and derivatives settlement without intermediary intervention. Financial services firms in Singapore and Switzerland are deploying these for automated compliance in structured products, though oracle reliability and code audit costs limit institutional scale.
- Supply Chain Management:Hyperledger Fabric implementations dominate Walmart-style agricultural provenance and Maersk container tracking, with sensor-to-ledger data pipelines verifying custody handoffs.
- Identity Verification:Decentralized identifier standards enable self-sovereign credential management for KYC/AML workflows, with pilot programs active in Estonia's e-Residency and India's Aadhaar-linked verifiable credentials.
Cryptocurrency leads on scale; Smart Contracts lead on momentum.
End User:
Vertical-specific compliance architectures and transaction velocity requirements shape procurement criteria and vendor selection timelines.
- Financial Services:Cross-border correspondent banking replacement and tokenized securities settlement drive wholesale infrastructure investment. FINRA-licensed custodians in the United States and ECB-supervised institutions in Germany are migrating repo and syndicated loan workflows to permissioned ledgers, facing 18-24 month certification delays.
- Healthcare:HIPAA-compliant data sharing and clinical trial provenance tracking utilize permissioned networks with granular access controls. United States hospital systems and NHS England pilot programs are prioritizing patient consent management and supply chain integrity for temperature-sensitive biologics.
- Government:Central bank digital currency pilots and land registry digitization dominate sovereign blockchain procurement. Brazil's Central Bank and the Eastern Caribbean Currency Union have deployed live retail CBDCs, while Dubai's land department executes property transfers on Ethereum-based infrastructure.
- Retail:Loyalty program interoperability and payment acceptance integration motivate merchant adoption. Block's Cash App and similar consumer-facing platforms in Japan and South Korea are embedding blockchain settlement rails for remittance and micropayment use cases.
Financial Services leads on scale; Government leads on momentum.
Deployment:
Data residency mandates and operational control requirements fragment infrastructure procurement between elastic cloud resources and captive data center capacity.
- Public Cloud:Elastic compute provisioning for node operations and smart contract execution leverages AWS, Azure, and Google Cloud's distributed regions. Startups and DeFi protocols in the United States and United Kingdom favor this model for rapid scaling without capital expenditure, though concentration risk in cloud provider outages has prompted multi-region failover architectures.
- Private Cloud:Isolated infrastructure satisfying financial services data sovereignty requirements captures premium pricing for Hyperledger and Corda implementations. Swiss and German banks mandate private cloud configurations for client asset custody, with explicit SLA guarantees for settlement finality and disaster recovery.
- Hybrid Cloud:Sensitive transaction validation on private nodes with public chain anchoring for notarization balances confidentiality and interoperability. Singaporean trade finance consortia and Australian agricultural cooperatives deploy this architecture for selective data disclosure to counterparties.
- On-Premises:Captive hardware in sovereign data centers serves defense and intelligence community requirements with air-gapped operational security. Israel and United Arab Emirates government blockchain initiatives specify on-premises deployment for classified supply chain and identity applications.
Public Cloud leads on scale; Private Cloud leads on momentum.
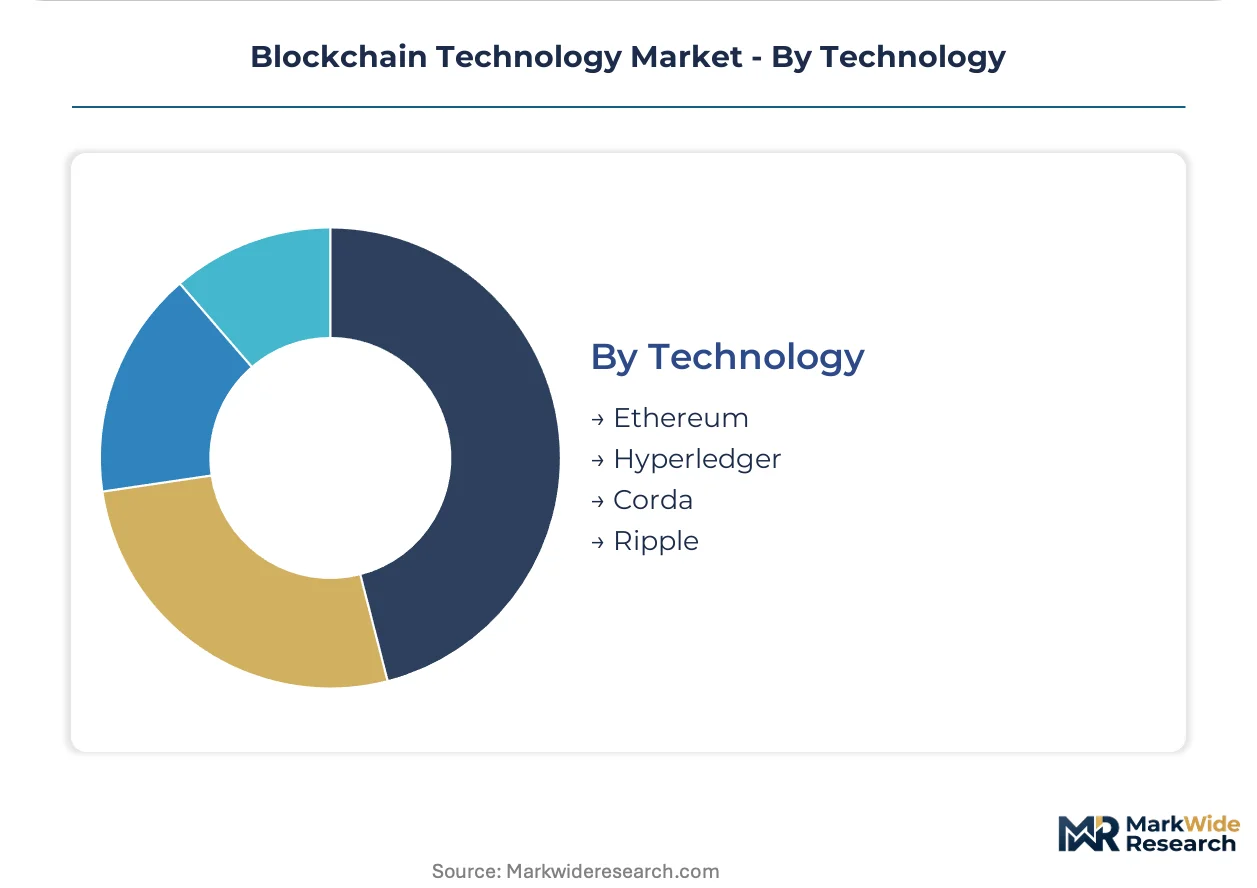
Technology:
Consensus mechanism design and programming language ecosystems create durable competitive moats with distinct tradeoffs between decentralization, throughput, and finality speed.
- Ethereum:Turing-complete smart contract platform with the deepest developer ecosystem and liquid staking derivatives supporting proof-of-stake validation. United States-based asset managers and European DeFi protocols anchor on Ethereum mainnet for composability, with layer-2 rollups on Arbitrum and Optimism addressing fee congestion during peak demand.
- Hyperledger:Modular permissioned framework governed by the Linux Foundation, optimized for enterprise consortium networks with pluggable consensus. IBM and Walmart anchor agricultural and pharmaceutical supply chain deployments on Hyperledger Fabric, with the Linux Foundation's governance model reducing vendor lock-in concerns for multi-party networks.
- Corda:Transaction privacy by design with point-to-point messaging rather than global broadcast, developed for financial services interbank workflows. R3's consortium of over 300 banks and regulators has standardized Corda for syndicated lending and trade finance, with the UK's Financial Conduct Authority recognizing its regulatory reporting capabilities.
- Ripple:Consensus ledger optimized for real-time gross settlement and cross-border remittance with pre-funded liquidity pools. Southeast Asian corridor markets including the Philippines and Mexico leverage RippleNet for migrant worker remittances, though United States SEC enforcement actions have constrained domestic bank adoption.
Ethereum leads on scale; Hyperledger leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing blockchain infrastructure investment toward jurisdictions with clearer compliance frameworks and lower operational friction. The United States, Germany, Singapore, Switzerland, and the United Arab Emirates have emerged as primary destinations for enterprise capital seeking regulatory predictability.
United States
Institutional custody demand and exchange infrastructure investment dominate deployment patterns. FINRA licensing requirements for digital asset broker-dealers extend certification timelines to 18-24 months. Texas data center clusters leverage stranded wind assets to achieve sub-$0.04/kWh operational economics for validation infrastructure.
Germany
ECB-supervised institutions are migrating repo and syndicated loan workflows to permissioned ledgers with stringent data residency mandates. BaFin's crypto custody licensing framework provides regulatory clarity absent in neighboring jurisdictions. Frankfurt's financial services cluster anchors Hyperledger and Corda implementations for interbank settlement.
Singapore
Regulatory sandboxes permit fractionalized commodity and real estate tokenization instruments for retail access. The Monetary Authority of Singapore's payment services licensing creates compliance infrastructure for regional fintech expansion. The Marina Bay financial district concentrates prime brokerage and asset management specialization.
Switzerland
Private banking clients demand segregated cold storage with explicit SLA guarantees for settlement finality. FINMA's distributed ledger technology guidelines reduce legal uncertainty for tokenized securities issuance. Zug's "Crypto Valley" cluster hosts protocol development and smart contract auditing expertise.
United Arab Emirates
Dubai's virtual asset regulatory authority permits property transfer execution on Ethereum-based infrastructure with streamlined licensing. VARA's framework for exchange operations attracts regional trading volume from less regulated markets. The Dubai International Financial Centre anchors institutional on-ramp services for Gulf capital.
Blockchain Technology Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular infrastructure specialization and zero-knowledge privacy integration. The vendor base stratifies across vertically integrated mining operators, regulated exchange-custodians, and enterprise software integrators. Three archetypes dominate: renewable-powered infrastructure operators, licensed financial services gateways, and consortium framework specialists. Competitive moves concentrate on strategic partnerships with cloud providers and geographic licensing expansion into regulatory sandboxes.
Within the infrastructure-operator archetype, Core Scientific exemplifies vertically integrated hosting scale across multiple states. Among regulated financial gateways, Coinbase Global occupies a position defined by institutional licensing depth. On the consumer payment vector, Block represents integration-focused positioning for retail remittance and micropayment use cases.
| Leading Market Players |
|---|
| Core Scientific |
| ScienceSoft |
| Coinbase Global |
| PixelPlex |
| LeewayHertz |
| Block |
| Galaxy Digital |
| Blockstream |
| Ripple |
| Others |
Supply Flow & Price Mechanics
Vertically integrated infrastructure operators anchor both supply position and pricing power in blockchain markets. Core Scientific's multi-state hosting model and captive renewable energy sourcing create cost structures that undercut modular competitors while securing long-term contract pricing with institutional clients.
Pricing Analysis
Direct-to-enterprise licensing commands premium positioning against retail SaaS tiers. Project-based implementation fees for Hyperledger and Corda deployments stratify across certification-grade vendor tiers, with FINRA-licensed custodians extracting 40-60% markups over unregulated alternatives. Pricing pressure stems from public cloud compute commoditization eroding proprietary infrastructure premiums. Financial services buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while retail-facing DeFi protocols compete aggressively on transaction fee minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale enterprise demand for permissioned ledger implementations. Hardware concentration in Taiwan and South Korea dominates specialized ASIC and GPU sourcing for validation infrastructure. Raw material dependencies span silicon wafers, rare earth magnets for cooling systems, and lithium-ion battery arrays for backup power. Supply chain risk centers on single-source vulnerability in advanced semiconductor fabrication. Distribution runs through systems integrators like IBM and Accenture for enterprise deployments, with cloud marketplaces capturing developer-centric workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain technology functions as a regulatory compounder where MiCA implementation across EU member states is accelerating institutional procurement timelines. The framework's reserve requirements and custody standards create demand visibility for compliant infrastructure providers.
For Market Incumbents: To counter modular blockchain fragmentation threatening monolithic platform dominance, deepen certification investments in zero-knowledge cryptography capabilities and expand private cloud capacity in Frankfurt and Singapore data centers. Channel control through exclusive systems integrator partnerships protects enterprise pricing power against public cloud commoditization.
For New Entrants and Emerging Players: VARA in Dubai opens a window for specialized custody infrastructure targeting Gulf sovereign wealth deployment. White-space opportunities concentrate in healthcare data sharing protocols and Australian agricultural provenance tracking. A go-to-market angle anchored in explicit SLA guarantees for settlement finality differentiates against incumbent cloud providers.
For Investors and Strategic Acquirers: Roll-up economics work for regional custody specialists because FINRA licensing timelines create artificial scarcity that disciplined acquirers can arbitrage. Long-term viability hinges on interoperability protocol standardization rather than single-chain concentration. The signal to watch is European Central Bank digital euro pilot expansion displacing correspondent banking infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Licensing Expansion | MiCA compliance in Germany and France accelerates institutional client onboarding velocity. |
| Zero-Knowledge Integration | zk-SNARK deployment enables HIPAA-compliant healthcare data sharing without ledger exposure. |
| Renewable Energy Sourcing | Texas wind-powered data centers achieve sub-$0.04/kWh validation economics. |
| Consortium Framework Partnership | Hyperledger Fabric governance reduces vendor lock-in for Walmart-scale supply chain networks. |
| Cross-Chain Bridge Development | Interoperability protocols address fragmentation risk across Ethereum and layer-2 rollups. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with blockchain infrastructure operators, regulatory affairs specialists at financial institutions, and enterprise IT procurement officers. Secondary validation draws from SEC enforcement filings, ECB payment system reports, and Linux Foundation governance disclosures. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include consensus mechanism type, deployment architecture, vertical application, and regulatory jurisdiction cluster. CAGRs derive from historical adoption curve analysis and institutional procurement pipeline visibility. Forecast inputs incorporate central bank digital currency pilot announcements and renewable energy cost trajectories for validation infrastructure.
Revisions become necessary when regulatory enforcement postures shift materially or interoperability standards achieve dominant adoption. Forecasts reflect documented assumptions regarding certification timeline stability and cloud provider concentration risk. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Blockchain in Energy Utilities Market