
 Biodegradable Face Towels Market | 2026-2036
Biodegradable Face Towels Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Face Towels Market Insights
The gap between premium lyocell towels and commodity cotton blends is realigning procurement strategies across hospitality supply chains. Kimberly-Clark leverages its North American retail footprint to dominate mass-market boxed formats. Xiantao Dingcheng Non-woven Products Co., Ltd. anchors export volumes through cost-optimized bamboo fiber production for European private-label buyers. EcolLink Nonwoven Co., Ltd. differentiates via compostable bag packaging that meets home-composting certification thresholds.
Biodegradable face towels are nonwoven or woven personal cleansing fabrics engineered to decompose under aerobic composting or marine biodegradation conditions within specified timeframes, typically constructed from cellulose fibers with tensile strength above 15 N per 5 cm width for wet-use integrity. Their primary commercial purpose is to replace petroleum-based synthetic wipes in skincare, hospitality, and medical cleansing applications where disposal pathways favor organic breakdown. The disposable segment leads absolute volume but carries thinner margins as supermarket and online retail channels drive price compression. Bamboo material grades command premium positioning in specialty stores and health shops due to antimicrobial fiber properties and supply scarcity relative to cotton. Lyocell formulations represent the fastest-growing material category, absorbing share from hemp as production scales and softness benchmarks improve.
REACH chemical safety standards and the EU F-Gas Regulation indirectly shape material choices by restricting fluorinated water-repellent coatings once common in wet-wipe substitutes. FDA cosmetic product labeling rules in the United States require biodegradability claims to substantiate decomposition conditions, filtering greenwashed entrants from legitimate compostable suppliers. China's GB standards for disposable hygiene products impose microbial limit testing that adds compliance cost but protects domestic manufacturers from low-quality imports. Stakeholders must monitor whether emerging state-level extended producer responsibility laws in California and New York shift cost burdens toward brand owners rather than downstream waste managers.
Market Dynamics
The EU Single-Use Plastics Directive is compressing synthetic wipe volumes while redirecting procurement budgets toward cellulose-based alternatives, forcing material substitution decisions across hospitality supply chains before compliance deadlines.
Growth Catalysts
- EU Green Deal mandates:The EU Single-Use Plastics Directive bans petroleum-based wet wipes from marine environments, redirecting institutional procurement toward compostable cellulose alternatives in Germany, France, and the Netherlands.
- Spa and wellness amenity upgrades:Premium hospitality chains now specify bamboo fiber towels as standard bathroom offerings, creating pull-through demand for certified biodegradable grades.
- Lyocell production scaling:Closed-loop solvent recovery systems are reducing unit costs for wood-pulp-based lyocell, enabling price parity with cotton blends in mid-market retail channels.
Market Restraints
- Bamboo fiber supply scarcity:Limited plantation acreage in Sichuan and Zhejiang provinces concentrates raw material sourcing, exposing converters to harvest-season price volatility.
- REACH compliance costs:ECHA registration requirements for novel fiber finishes add EUR 15,000-50,000 per substance, filtering small entrants from European private-label supply.
- Cotton blend substitution:Conventional cotton remains entrenched in price-sensitive supermarket channels where biodegradability certification carries no retail premium.
Strategic Opportunities
- Medical cleansing applications:FDA cosmetic labeling rules create compliance moats for verified compostable suppliers seeking entry into outpatient clinic and long-term care facility supply chains.
- Home-composting certification:TÜV OK Compost HOME and BPI home-compostable standards unlock direct-to-consumer subscription channels where disposal convenience drives repurchase rates.
- Extended producer responsibility laws:California and New York state-level EPR frameworks shift waste management cost burdens toward brand owners, favoring vertically integrated producers with captive composting partnerships.
Industry Challenges
- Aerobic composting infrastructure gaps:Municipal composting facilities in mid-sized US metropolitan areas lack industrial-scale capacity, creating disposal friction for certified biodegradable products.
- Microbial limit testing timelines:China's GB standards for disposable hygiene products impose 45-90 day laboratory validation cycles, delaying export shipments to Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Face Towels Market |
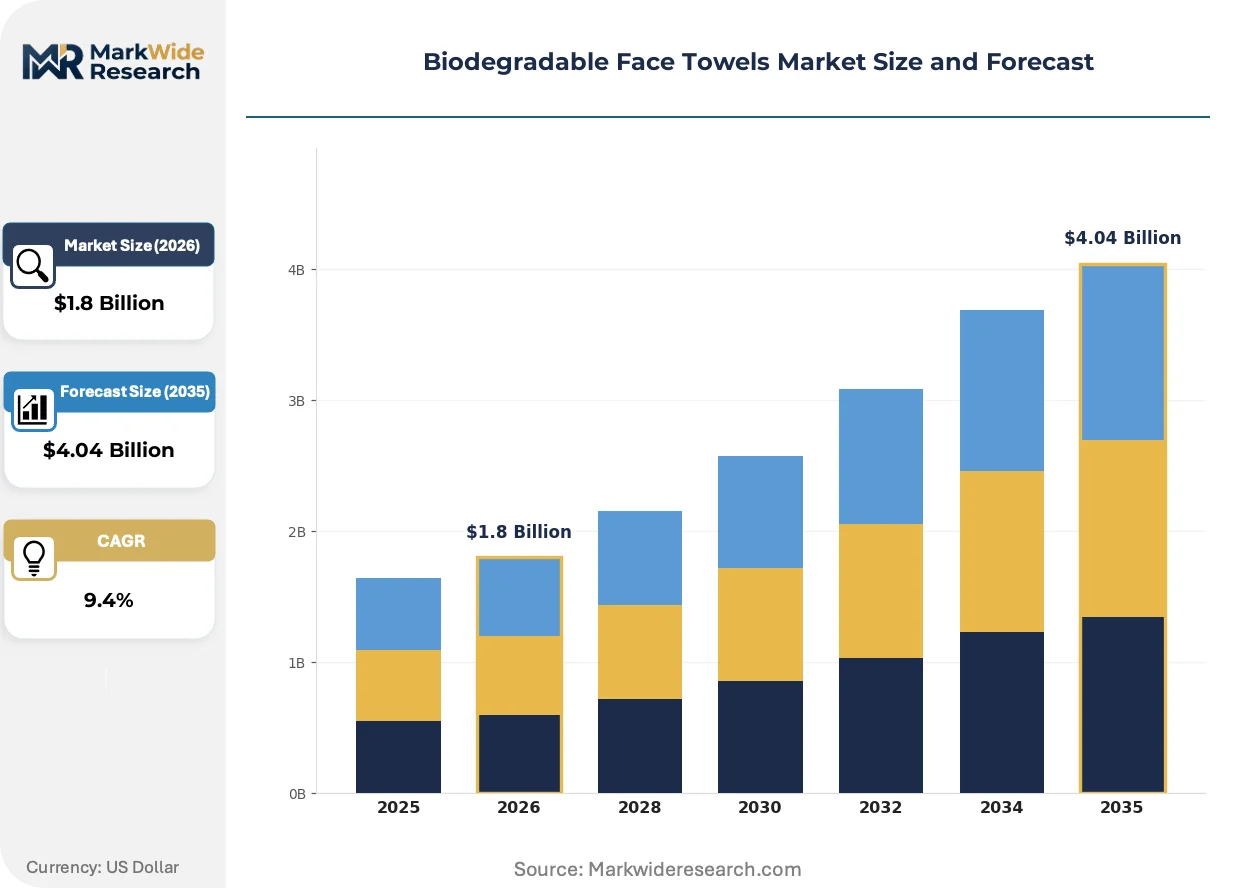
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Compostable, Biobased Material: Cotton, Bamboo, Hemp, Lyocell Packaging Type: Boxed, Plastic Wrapped, Biodegradable Bag, Bulk Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Shops |
| Companies Covered | KOKUBO, Jiangsu Huanyi, HS Non Woven, Xiantao Dingcheng Non-woven Products Co., Ltd., Unihope, Bonyee, Kimberly-Clark, Nice-Pak Products, EcolLink Nonwoven Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Face Towels Market Trends and Innovations
Material science advances and regulatory enforcement are compressing development cycles for next-generation cellulose fibers, while procurement teams reweight supplier scorecards toward verifiable end-of-life credentials.
Lyocell fiber technology is converging with antimicrobial finishing processes to produce dual-function towels that meet both softness benchmarks and hygiene requirements for medical settings. German hospital procurement consortiums are piloting these grades for patient bathing protocols. The structural consequence is compressing demand for separate antimicrobial additive treatments that previously required synthetic binders.
REACH chemical safety standards and the EU F-Gas Regulation are restricting fluorinated water-repellent coatings once standard in wet-wipe substitutes, forcing reformulation toward plant-based alternatives. Manufacturers serving European markets are accelerating R&D partnerships with bio-based coating suppliers. Personal care disposables with residual fluorinated content face import barriers at Rotterdam and Hamburg ports.
Green hotel certification programs in Germany now mandate biodegradable guest amenities as a scored criterion, rotating procurement authority from purchasing managers to sustainability officers. Specialty distributors serving Bavarian and Baden-Württemberg hospitality clusters report contract values shifting toward multi-year supply agreements with composting service bundling. This behavioral pivot is most visible in boutique properties seeking Green Key or EU Ecolabel differentiation.
Biodegradable Face Towels Market Segmentation
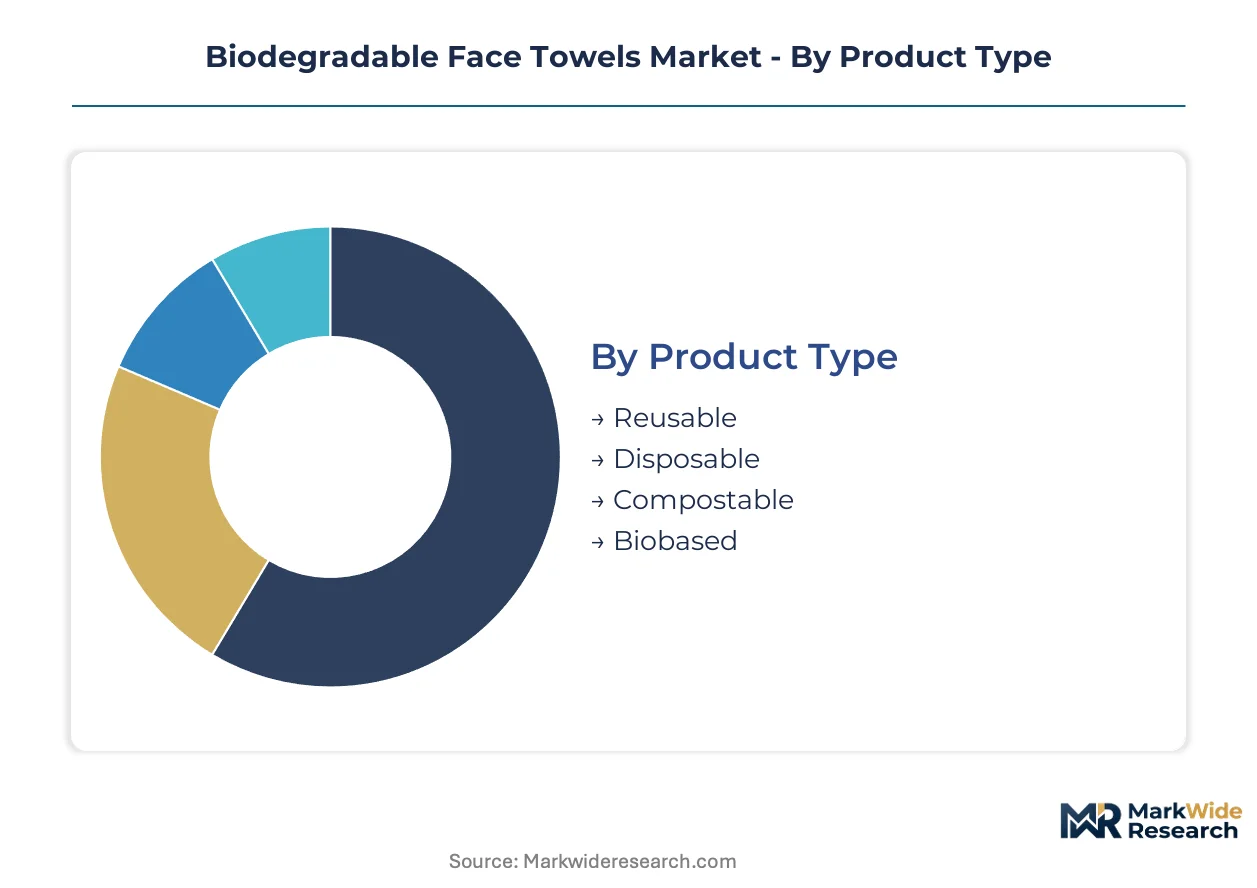
Material specifications and disposal pathways create distinct procurement clusters across hospitality, retail, and medical channels. Each segmentation axis reveals tension points between certification costs, consumer convenience, and regulatory compliance that reshape supplier selection criteria.
Product Type:
Technical performance under wet-use conditions and end-of-life certification status differentiate procurement budgets across institutional and consumer segments.
- Disposable:Nonwoven cellulose constructions engineered for single-use integrity dominate absolute volume through supermarket and online retail channels. Price compression in mass-market formats squeezes converter margins despite regulatory tailwinds from EU Single-Use Plastics Directive substitution mandates.
- Compostable:Certified grades meeting TÜV OK Compost HOME or BPI industrial standards command premium positioning in German green hotel programs and Dutch wellness chains where disposal infrastructure supports organic breakdown. Procurement contracts increasingly bundle composting service partnerships.
- Reusable:Woven constructions with tensile recovery above 80% after 50 wash cycles target eco-conscious consumer segments willing to absorb higher upfront cost for lifecycle economy.
- Biobased:Products with minimum renewable content thresholds certified under USDA BioPreferred or equivalent schemes access federal procurement preferences in the United States and public tender advantages in France.
Disposable leads on scale; compostable leads on momentum.
Material:
Fiber sourcing geography and processing chemistry determine cost structures and sustainability credentials that procurement teams weight differently across premium and commodity channels.
- Lyocell:Closed-loop solvent-spun wood pulp fibers achieve softness benchmarks above 3.0 on the Kawabata evaluation system, enabling substitution for cotton in mid-market retail. Austrian and Czech production facilities are expanding capacity to serve German private-label demand.
- Bamboo:Bast fibers from Sichuan and Zhejiang plantations carry natural antimicrobial properties valued in spa and medical cleansing applications. Limited plantation acreage concentrates supply risk during harvest seasons.
- Cotton:Conventional and organic grades retain entrenched position in price-sensitive supermarket channels where biodegradability certification commands no retail premium.
- Hemp:Coarser fiber morphology limits application to industrial cleansing and agricultural hygiene where durability outweighs softness requirements; processing infrastructure lags lyocell scaling.
Lyocell climbs the fastest; cotton retains the largest installed base.
Packaging Type:
Packaging format selection reflects channel-specific requirements for shelf presence, shipping economics, and disposal friction reduction.
- Biodegradable Bag:Home-compostable film structures certified to EN 13432 or ASTM D6400 unlock direct-to-consumer subscription channels in California and New York where municipal composting access varies by municipality.
- Boxed:Rigid paperboard formats dominate North American mass retail through Kimberly-Clark's shelf-space leverage and Costco pallet-display optimization.
- Plastic Wrapped:Conventional polyolefin films face regulatory pressure under extended producer responsibility frameworks and consumer backlash in European premium channels.
- Bulk:Unpackaged or minimal-wrap formats serve hospitality procurement at scale, reducing per-unit packaging cost for properties with on-site linen management or centralized composting.
Boxed controls retail throughput; biodegradable bag shows steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, brand positioning, and consumer education requirements for composting protocol communication.
- Specialty Stores:Curated assortments in health and wellness retailers enable premium pricing for certified bamboo and lyocell grades with staff-trained disposal guidance. German dm-drogerie markt and Holland & Barrett in the United Kingdom anchor European distribution.
- Online Retail:Amazon and direct-to-consumer platforms absorb growing share through subscription mechanics and review-driven discovery, though return rates exceed physical retail for texture-sensitive purchases.
- Supermarkets:Carrefour, Tesco, and Kroger shelf-space competition favors private-label boxed formats with price points compressed by cotton blend substitution.
- Health Shops:Independent pharmacies and organic retailers in France and Italy stock antimicrobial-finished grades for medical-adjacent positioning with pharmacist endorsement.
Supermarkets move the most units; specialty stores capture the highest margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nonwoven engineering talent clusters in Germany, China, and the United States anchor regional production capabilities for cellulose-based disposables. Technical expertise in closed-loop solvent systems and compostable packaging design concentrates procurement authority in these markets.
Germany
Green hotel certification programs in Bavaria and Baden-Württemberg mandate biodegradable guest amenities, rotating procurement authority from purchasing managers to sustainability officers. The EU Single-Use Plastics Directive accelerates material substitution timelines for hospitality supply chains. Specialty distributors in Munich and Stuttgart report multi-year supply agreements bundling composting services.
China
Bamboo fiber sourcing concentrates in Sichuan and Zhejiang provinces, exposing converters to harvest-season price volatility for bast fiber supply. GB standards for disposable hygiene products impose microbial limit testing that adds compliance cost but protects domestic manufacturers. Xiantao-based nonwoven clusters anchor export volumes for European private-label buyers.
United States
FDA cosmetic product labeling rules require biodegradability claims to substantiate decomposition conditions, filtering greenwashed entrants from legitimate compostable suppliers. California and New York state-level extended producer responsibility frameworks shift waste management cost burdens toward brand owners. Kimberly-Clark leverages North American retail footprint to dominate mass-market boxed formats.
France
Public tender advantages for USDA BioPreferred-equivalent certified products create procurement preferences for biobased grades in institutional channels. ANSM cosmetic safety oversight reinforces compliance moats for verified compostable suppliers. Paris-based hospitality procurement consortiums pilot lyocell-antimicrobial dual-function towels for patient bathing protocols.
Netherlands
Rotterdam and Hamburg port authorities enforce import barriers on personal care disposables with residual fluorinated content under REACH chemical safety standards. Dutch wellness chains specify certified compostable grades where municipal composting infrastructure supports organic breakdown. Amsterdam-headquartered distributors specialize in home-compostable packaging formats for direct-to-consumer channels.
Biodegradable Face Towels Market Competitive Landscape
Top-tier vendors anchor mass-market retail through shelf-space dominance and pallet-display optimization, while mid-tier specialists occupy private-label and hospitality contract niches. The vendor base stratifies across three functional tiers: multinational consumer goods conglomerates with North American retail leverage, Asia-Pacific fabricators with cost-optimized cellulose production, and European specialists with compostable certification expertise. Two dominant competitive moves define current positioning: backward integration into captive fiber sourcing to secure bamboo and lyocell supply, and strategic bundling of composting service partnerships with multi-year hospitality contracts.
Within the Asia-Pacific fabricator tier, Xiantao Dingcheng Non-woven Products Co., Ltd. exemplifies cost-optimized production positioning for export-oriented supply. EcolLink Nonwoven Co., Ltd. occupies a specialist position centered on home-compostable packaging certification. Kimberly-Clark represents the multinational conglomerate archetype with mass-market retail channel dominance. These three anchors illustrate the structural segmentation between scale-driven retail penetration, export-focused manufacturing efficiency, and premium-tier certification differentiation.
| Leading Market Players |
|---|
| KOKUBO |
| Jiangsu Huanyi |
| HS Non Woven |
| Xiantao Dingcheng Non-woven Products Co., Ltd. |
| Unihope |
| Bonyee |
| Kimberly-Clark |
| Nice-Pak Products |
| EcolLink Nonwoven Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Closed-loop lyocell solvent recovery systems are compressing unit production costs while simultaneously concentrating manufacturing authority in Austrian and Czech production facilities, creating asymmetric pricing power for fiber converters with captive access to scaled wood-pulp processing. This dual effect rewards early movers who secured long-term pulp supply agreements before capacity constraints tightened.
Pricing Analysis
Bundled composting service contracts versus unbundled product-only supply splits procurement economics across German hospitality and North American retail channels. Three-tier pricing structure across premium certified compostable, standard cellulose disposable, and economy cotton-blend levels reflects certification cost pass-through and fiber grade differentiation. Price differentiation hinges on TÜV OK Compost HOME certification status and volume scale, with supermarket private-label tiers experiencing cost compression from cotton substitution. Pricing pressure stems from REACH compliance cost absorption, while boutique hospitality buyers show lowest price sensitivity due to Green Key certification requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Los Angeles anchor hub-and-spoke patterns for European and North American fulfillment, with Xiantao-based clusters feeding containerized export volumes through Shanghai and Ningbo ports. Raw material sourcing draws from Sichuan bamboo plantations, Austrian wood-pulp mills, and Indian cotton ginning operations. Single-source vulnerability concentrates in bast fiber harvest seasons, exposing converters to Zhejiang province weather disruptions. Distribution runs through specialty hospitality distributors in Bavaria, mass retail brokerage networks in North America, and direct-to-consumer subscription platforms in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in lyocell scaling and home-compostable certification tiers, with closed-loop solvent recovery and TÜV OK Compost HOME validation driving cost-down trajectories and premium positioning simultaneously.
For Market Incumbents: Lock in multi-year bamboo fiber offtake agreements with Sichuan plantation cooperatives before harvest-season price volatility intensifies. Secure captive composting partnerships with Dutch and German municipal waste operators to defend service-bundled contract structures against pure-product competitors. Prioritize lyocell capacity expansion in Czech facilities to capture mid-market retail substitution demand as softness benchmarks achieve cotton parity. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable entry vector, with California and New York EPR frameworks creating disposal-friction advantages for home-compostable packaging specialists. Target medical cleansing applications where FDA cosmetic labeling rules filter greenwashed competitors and verified compostable suppliers command procurement preference. Deploy antimicrobial lyocell formulations through outpatient clinic supply chains as German hospital consortiums pilot patient bathing protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among Asia-Pacific fabricators with cost-optimized cellulose production and limited certification infrastructure, presenting consolidation targets for European specialists seeking backward integration into bamboo fiber supply. Long-term viability favors vertically integrated producers with captive composting partnerships and closed-loop lyocell solvent systems. Watch California and New York EPR implementation timelines as inflection indicators for waste-management cost burden shifts toward brand owners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Fiber Sourcing | Sichuan plantation offtake agreements secure raw material supply against harvest-season volatility. |
| Home-Compostable Packaging Certification | TÜV OK Compost HOME validation unlocks direct-to-consumer subscription channels in EPR-regulated states. |
| Lyocell Production Scale-Up | Czech facility expansion captures mid-market retail demand as solvent recovery achieves cotton cost parity. |
| Composting Service Partnership Bundling | German hospitality multi-year contracts integrate waste management with product supply for differentiation. |
| Antimicrobial Finish R&D Partnership | Bio-based coating suppliers replace fluorinated treatments restricted under EU F-Gas Regulation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospitality procurement managers, sustainability officers at German hotel chains, nonwoven production engineers at Xiantao-based converters, and specialty retail category buyers with secondary validation against EU Single-Use Plastics Directive implementation documents, REACH chemical safety registration databases, FDA cosmetic labeling guidance, and Chinese GB standards for disposable hygiene products. Bottom-up fiber production estimates and top-down hospitality amenity spend analysis were triangulated against trade flow data through Rotterdam and Hamburg ports.
Segment-weighting approaches modeled material-grade splits, product-type volumes, packaging format adoption curves, and distribution channel economics across the projection horizon. CAGRs were derived from fiber capacity expansion timelines, regulatory compliance deadline impacts, and substitution elasticity estimates for petroleum-based wet wipes. Forecast inputs incorporated lyocell solvent recovery cost curves, bamboo plantation acreage constraints, and municipal composting infrastructure buildout rates in target metropolitan areas.
Raw material price volatility, regulatory enforcement variance across EU member states, and aerobic composting facility deployment delays are the dominant revision risks to volume and value outputs. Forecasts reflect documented assumptions on fiber substitution rates and certification adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Australia Kids Scooter Market
Consumer Goods
Foundation Cream Market
Consumer Goods
Cosmetic Palettes Market
Consumer Goods
United States Pet Care and Services Market
Consumer Goods
Smart Pet Wearable Product Market
Consumer Goods
Diving Regulator Market
Consumer Goods
Hair Tonic Market
Consumer Goods
Low Tar Cigarette Paper Market
Consumer Goods
Italy Luxury Jewelry Market
Consumer Goods
Memory Foam Market
Consumer Goods
Baby Stroller Market
Consumer Goods
Germany Home Appliances Market
Consumer Goods
Insulated Tumblers Market
Consumer Goods
Self-Lacing Shoes Market
Consumer Goods
Argentina Home Appliances Market
Consumer Goods
Flip Flops Market