
 Bilingual Education for Children Market | 2026-2036
Bilingual Education for Children Market Size, Share, and Industry Trends Forecast 2026-2036
Bilingual Education for Children Market Insights
CELTA and DELTA certification cycles is rotating the competitive landscape for bilingual curriculum providers, filtering out underqualified entrants. Pearson Education leverages its assessment infrastructure to anchor standardized bilingual testing across multiple continents. EF Education First sustains direct-to-consumer language camps that compete with traditional school-based programs. Duolingo differentiates through gamified mobile delivery that extends reach beyond institutional channels.
Bilingual education for children denotes structured pedagogical programs delivering academic content through two languages to learners aged two through eighteen, typically maintaining a 50/50 or 60/40 language distribution ratio across subjects. Immersion Programs dominate revenue generation by commanding premium tuition, while Dual Language Classes represent the fastest-expanding segment as public school districts adopt two-way models. Project-Based Learning occupies the highest-margin teaching methodology tier due to its intensive facilitator training requirements and scalable curriculum licensing potential.
China's Ministry of Education sets Mandarin-English ratio requirements, while the UK's Ofsted inspects bilingual provision quality in state-funded schools. France's Ministry of National Education regulates foreign language hours in primary curricula, shaping where providers can operate. Stakeholders must monitor regulatory shifts in curriculum language ratios and teacher qualification mandates to anticipate which delivery models retain market access.
Market Dynamics
CELTA and DELTA certification cycles are filtering the competitive landscape for bilingual curriculum providers, raising entry barriers and consolidating quality supply around credentialed institutions. This structural force compresses margins for underqualified entrants while rewarding standardized assessment infrastructure.
Growth Catalysts
- China's Ministry of Education Mandate:English instruction from Grade Three creates institutional demand for Mandarin-English program providers across urban school districts.
- Urban Megacity Concentration:Shanghai's expatriate families and affluent households seek immersive dual-language programs, concentrating premium tuition revenue in tier-one cities.
- Project-Based Learning Methodology:Intensive facilitator training requirements and scalable curriculum licensing generate high-margin recurring revenue for certified providers.
Market Restraints
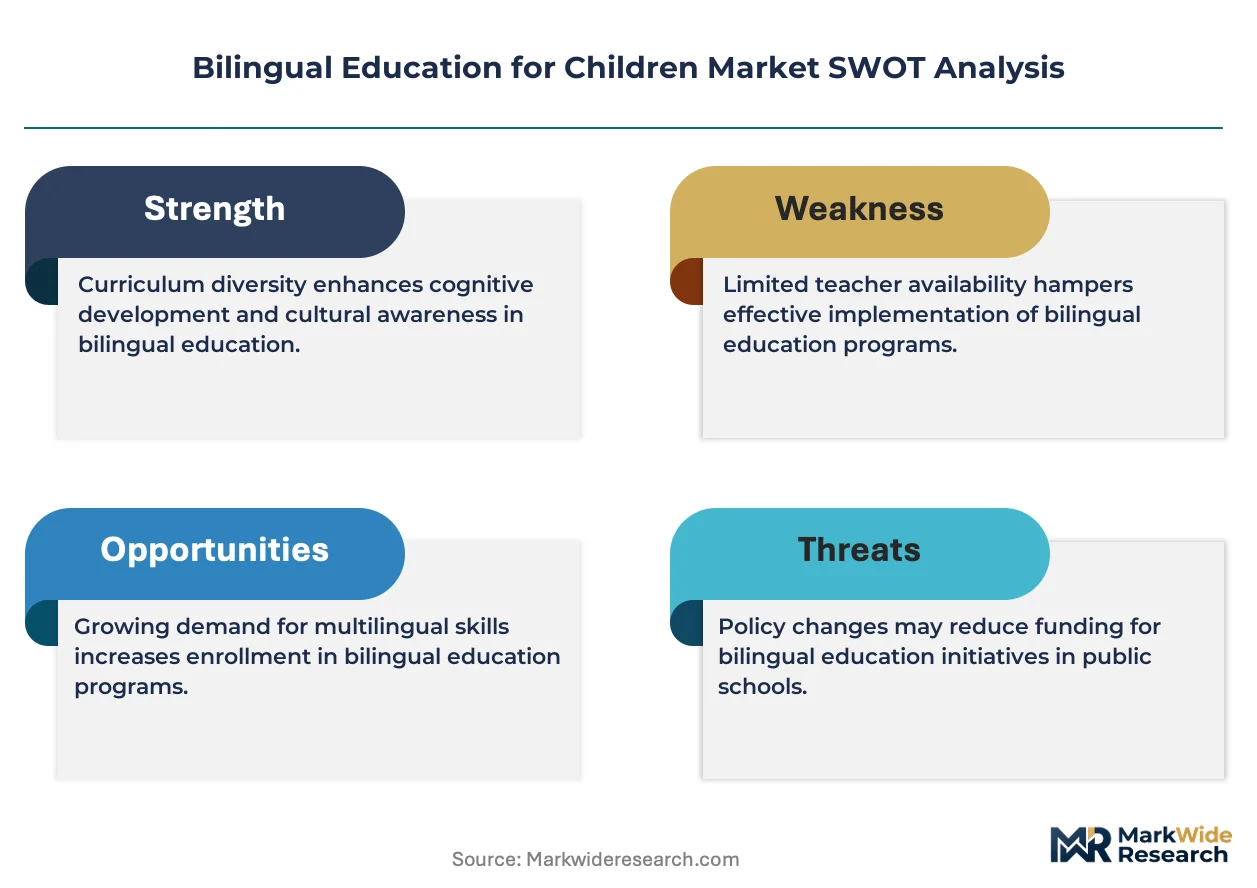
- Teacher Certification Bottleneck:CELTA and DELTA completion cycles limit qualified instructor supply, constraining program expansion velocity.
- Curriculum Language Ratio Compliance:China's Ministry of Education mandates specific Mandarin-English distributions, restricting pedagogical flexibility for foreign entrants.
- Assessment Infrastructure Capital Requirements:Standardized bilingual testing platforms demand substantial upfront investment in technology and psychometric validation.
Strategic Opportunities
- Southeast Asia Private International School Expansion:Dual-language curricula adoption in regional private institutions creates white space for curriculum licensors.
- Public School District Two-Way Model Adoption:Dual Language Classes represent accelerating demand as state-funded systems implement bilingual programming.
- Mobile-First Delivery Convergence:Gamified platform integration with institutional channels extends reach beyond traditional school-based enrollment.
Industry Challenges
- Qualified Bilingual Educator Pipeline:CELTA and DELTA certification timelines create eighteen-to-twenty-four month hiring cycles for program launch.
- Cross-Border Curriculum Localization:China's GB standards and the UK's Ofsted inspection frameworks impose divergent compliance requirements on multi-jurisdiction operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bilingual Education for Children Market |
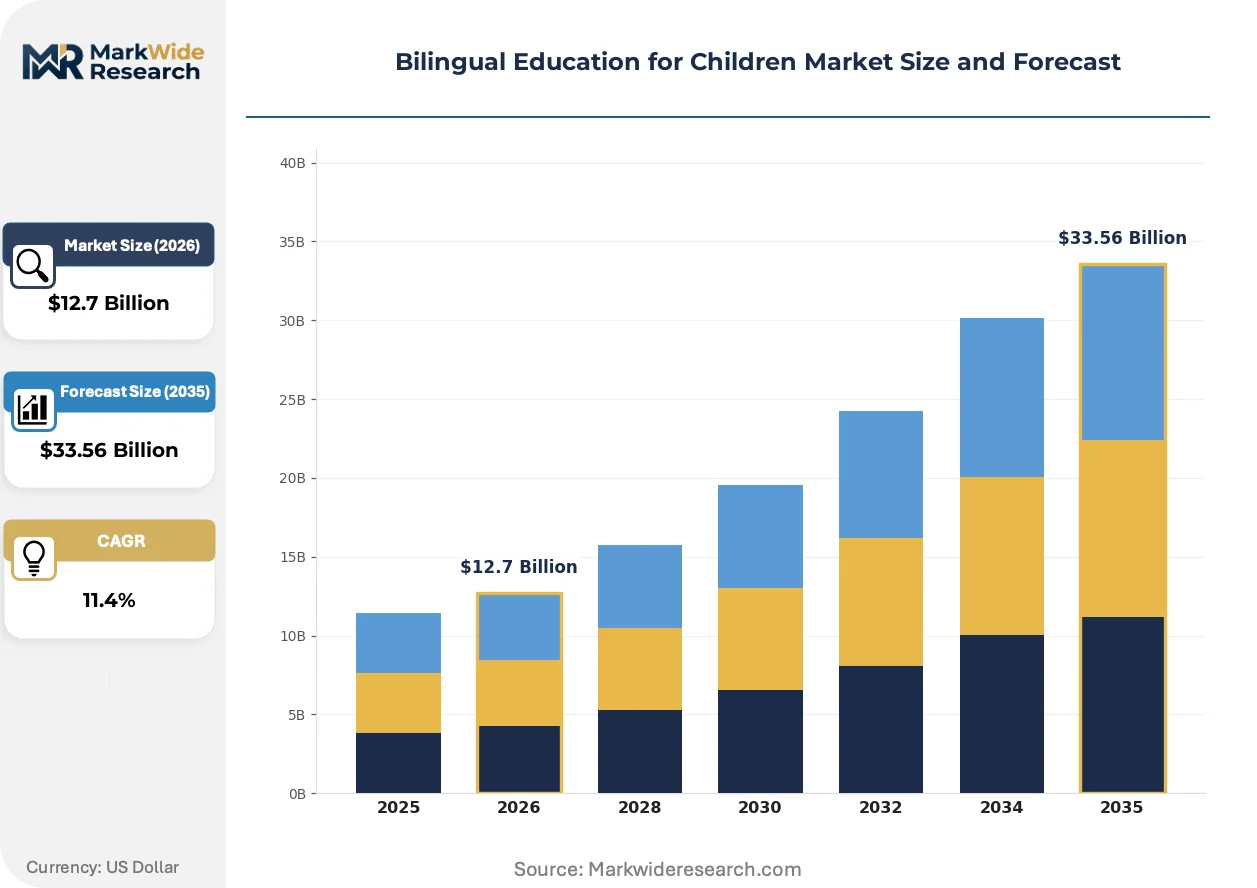
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Immersion Programs, Dual Language Classes, Transitional Programs, Heritage Language Programs Teaching Methodology: Project-Based Learning, Structured Immersion, Content-Based Instruction, Total Physical Response Age Group: Preschool, Primary School, Secondary School, Early Childhood Class Size: Small Group, One-on-One, Whole Class, Large Group |
| Companies Covered | Nord Anglia, Pearson Education, EF Education First, Duolingo, McGraw-Hill Education, Huijia Education, Cogdel Education Group, New Oriental, Macmillan Education, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bilingual Education for Children Market Trends and Innovations
Gamified mobile delivery platforms are actively reshaping how bilingual education reaches learners outside institutional channels. This shift compresses traditional enrollment cycles and fragments demand across device-native consumption patterns.
Adaptive learning algorithms are supplanting static curriculum sequencing in premium program tiers. International school chains in Southeast Asia are deploying these systems across Mandarin-English immersion tracks. The technology is supplanting conventional facilitator-led pacing models with real-time proficiency-adjusted content delivery, compressing instructor-to-student ratios and enabling scaled enrollment without proportional staffing growth.
France's Ministry of National Education has tightened foreign language hour requirements in primary curricula, reshaping where European providers can operate profitably. The regulation restricts English immersion intensity in state-funded settings below age thresholds. Private bilingual institutions in Paris and Lyon are responding by shifting programming to after-school and weekend formats to retain market access.
Parental preference is rotating toward immersive Mandarin-English programs over traditional single-language enrichment. Urban households in Shanghai and Beijing are disintermediating conventional tutoring centers in favor of school-integrated dual-language tracks. This behavioral pivot is most visible among expatriate families and affluent local households seeking credential portability for secondary admissions.
Bilingual Education for Children Market Segmentation
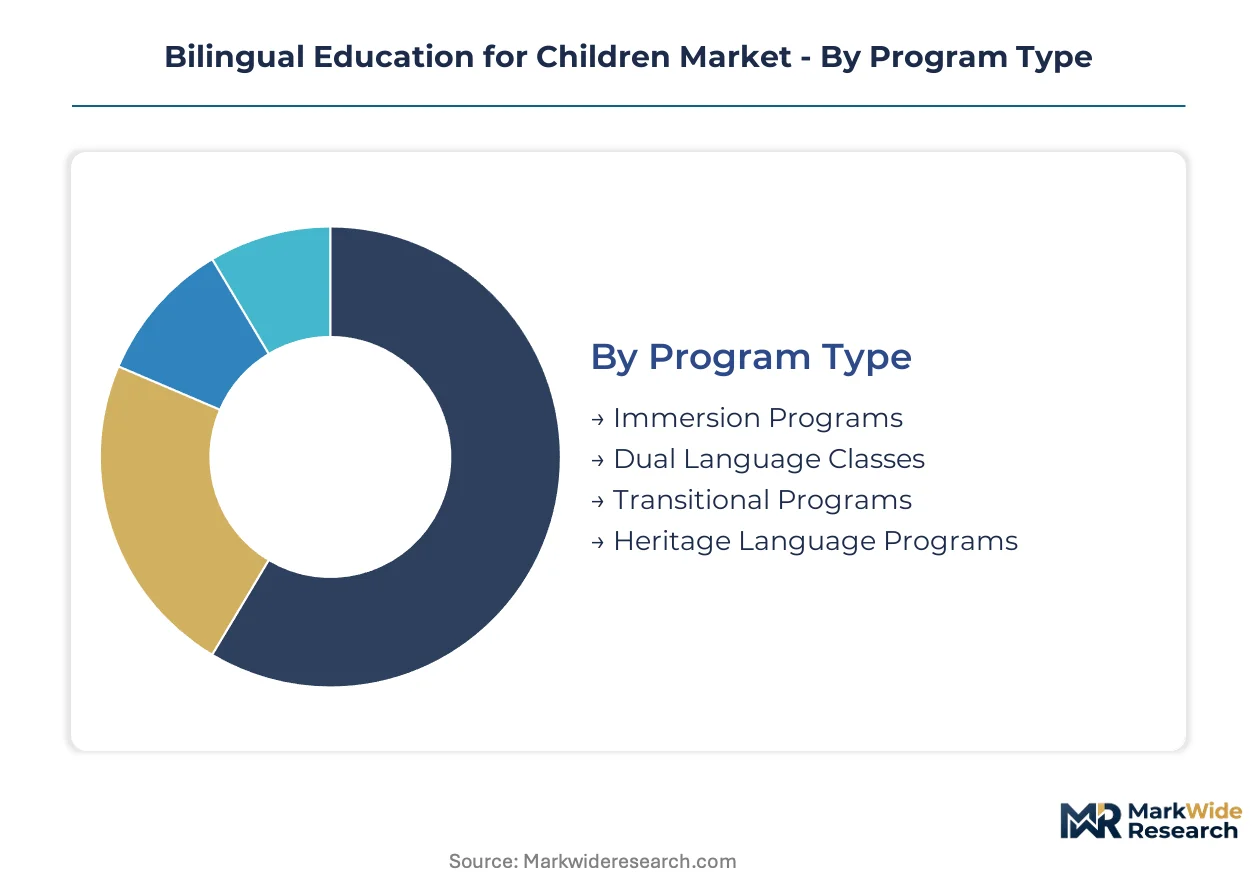
Bilingual education for children fragments across program architecture, pedagogical approach, developmental stage, and instructor-to-learner ratios. Each dimension shapes capital intensity, regulatory compliance burden, and addressable household income tiers differently.
Program Type:
Substitute pressure from single-language enrichment tutoring and informal immersion travel programs threatens lower-commitment program formats most severely.
- Immersion Programs:Deliver 50/50 or 60/40 language distribution across all academic subjects through extended daily exposure. Demand concentrates in Shanghai and Beijing among expatriate families and affluent local households seeking credential portability for secondary admissions. Premium tuition positioning and intensive facilitator requirements compress margins for underqualified entrants.
- Dual Language Classes:Two-way models integrate native speakers of both target languages within shared classrooms, accelerating mutual acquisition. Public school districts across the United States and urban China are adopting this format fastest, generating institutional procurement volume beyond private household spend. Regulatory alignment with state bilingual education mandates determines market access.
- Transitional Programs:Short-term bridge formats shift learners from native-language instruction toward target-language dominance. Federal Title III funding eligibility shapes deployment in US districts with high English-learner concentrations.
- Heritage Language Programs:Community-based models preserve immigrant family languages for second- and third-generation children. Weekend scheduling and volunteer instructor dependence limit scalability.
Immersion Programs retain volume leadership; Dual Language Classes hold the steepest expansion curve.
Teaching Methodology:
Cost tier stratification separates capital-intensive technology-enabled methods from labor-dependent facilitator models.
- Project-Based Learning:Learners construct knowledge through extended interdisciplinary investigations requiring intensive facilitator training. Curriculum licensing generates recurring high-margin revenue for certified providers. Southeast Asian international school chains deploy this methodology across Mandarin-English tracks to differentiate premium positioning.
- Structured Immersion:Systematic sheltering of academic content with graduated complexity reduction dominates early-primary implementation. China's Ministry of Education mandates align with this approach for Grade Three English instruction commencement.
- Content-Based Instruction:Subject matter drives language acquisition rather than explicit grammar sequencing. Science and mathematics modules attract STEM-focused households in tier-one Chinese cities.
- Total Physical Response:Kinesthetic command-response patterns suit preschool and early childhood motor-development stages. Instructor certification requirements remain minimal, enabling rapid program launch.
Project-Based Learning commands premium pricing; Total Physical Response scales most rapidly into emerging markets.
Age Group:
Customer type segmentation separates institutional procurement from direct household expenditure across developmental windows.
- Preschool:Full-day immersion for ages two through five capitalizes on critical period plasticity. Urban Chinese households disintermediate tutoring centers in favor of school-integrated tracks.
- Primary School:Grades one through six represent peak enrollment concentration where China's Ministry of Education mandates formal English instruction commencement. Compliance-driven demand shapes provider selection criteria.
- Secondary School:International baccalaureate and advanced placement tracks require bilingual delivery for university admission competitiveness. Expatriate family mobility drives program switching costs.
- Early Childhood:Parent-accompanied or partial-day formats for ages zero through three occupy the lowest capital intensity tier. France's Ministry of National Education restrictions on state-funded foreign language hours below primary age redirect demand toward private weekend formats.
Primary School anchors enrollment volume; Preschool exhibits the steepest household expenditure growth.
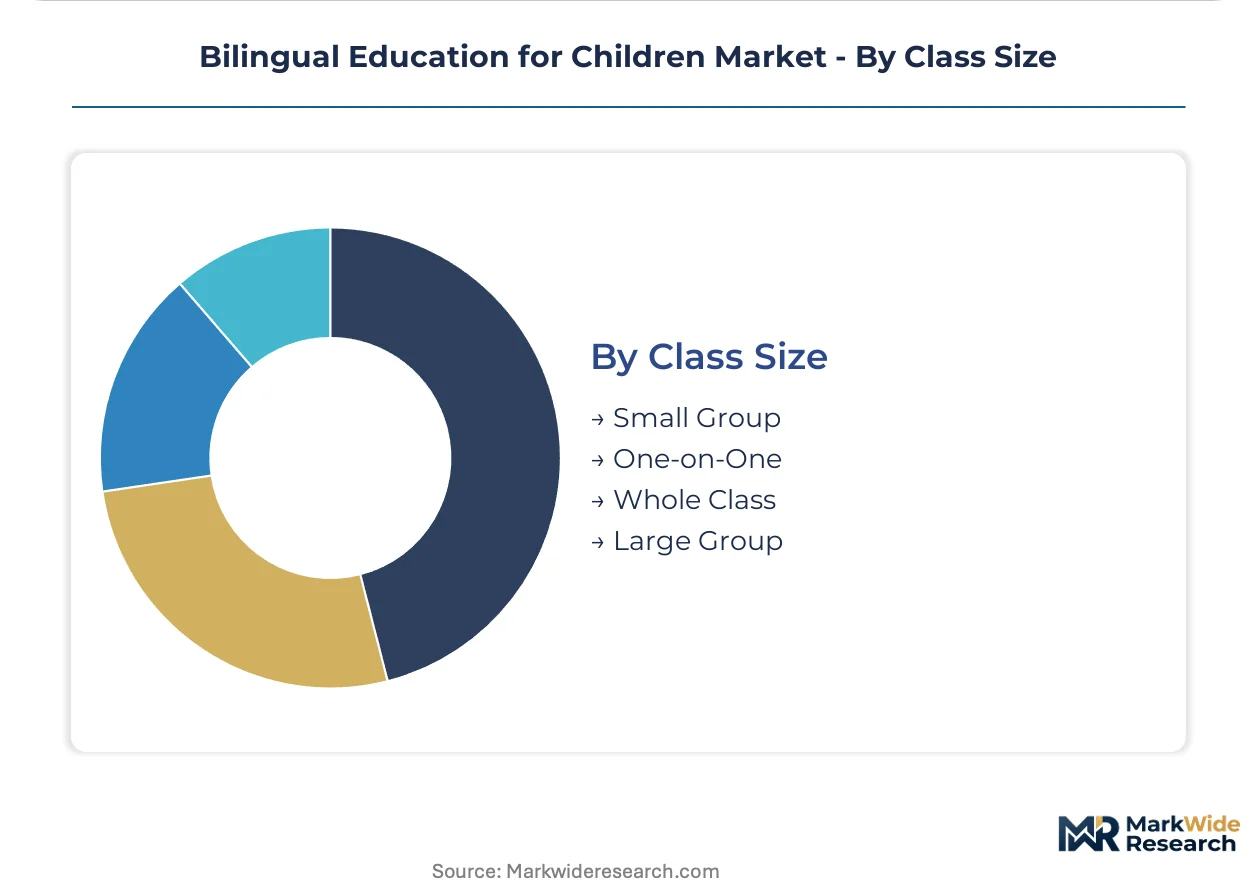
Class Size:
Supply concentration in qualified bilingual educators dictates which formats achieve scalable deployment.
- Small Group:Six-to-twelve learner cohorts balance personalized attention with unit economics viable for middle-income households. After-school programs in Paris and Lyon adopt this structure to circumvent French state funding restrictions.
- One-on-One:Individual tutoring commands the highest hourly rates but faces displacement from adaptive learning algorithms in premium tiers. Duolingo's gamified mobile delivery extends downward price pressure.
- Whole Class:Standard twenty-to-thirty student configurations dominate public school district adoption. CELTA and DELTA certification bottlenecks constrain qualified instructor supply for scaled implementation.
- Large Group:Auditorium or camp-format delivery achieves lowest per-learner cost through facilitator-to-student ratio compression. EF Education First sustains direct-to-consumer language camps competing with institutional channels.
Whole Class retains institutional procurement dominance; Small Group captures fastest household segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expatriate families and affluent urban households concentrate demand in tier-one cities where credential portability drives program selection. Institutional procurement from public school districts supplements direct household expenditure. Regulatory mandates on language ratios and teacher qualifications shape provider market access across jurisdictions.
China
Shanghai and Beijing anchor demand for immersive Mandarin-English tracks among expatriate families seeking secondary admission credentials. The Ministry of Education mandates English instruction commencement from Grade Three, creating compliance-driven procurement across urban districts. Yangtze River Delta international school chains deploy project-based learning methodologies to differentiate premium positioning.
United States
Public school districts in California and Texas accelerate two-way dual language model adoption, generating institutional procurement volume. Federal Title III funding eligibility shapes transitional program deployment in high English-learner concentration districts. Los Angeles and Houston metropolitan areas concentrate heritage language program activity among immigrant communities.
France
Paris and Lyon households shift demand toward after-school and weekend formats following Ministry of National Education restrictions on state-funded foreign language hours below primary age. Private bilingual institutions circumvent regulatory constraints through scheduling adaptation. Île-de-France maintains the densest concentration of Mandarin-English immersion programs among European capitals.
United Kingdom
Ofsted inspection frameworks for bilingual provision quality in state-funded schools determine provider eligibility. London and Southeast England concentrate premium international school enrollment among mobile professional families. Cambridge and Oxford proximity clusters attract curriculum licensors seeking proximity to assessment validation infrastructure.
Singapore
Private international school expansion across the island-state creates white space for dual-language curriculum providers. The Ministry of Education bilingual policy framework mandates English-Mandarin instruction, institutionalizing demand. Expatriate family corridors in the central region sustain premium tuition pricing for immersive tracks.
Bilingual Education for Children Market Competitive Landscape
Player mix skews toward diversified education conglomerates with assessment infrastructure and direct-to-consumer language platforms. Market structure exhibits moderate consolidation around credential-bearing institutions with regulatory compliance capabilities. Two strategic archetypes dominate: curriculum licensors with scalable assessment platforms and immersive program operators with premium physical footprints. Competitive moves center on geographic expansion into Southeast Asian private school markets and technology licensing for adaptive learning algorithm deployment.
Among diversified education groups, Pearson Education and EF Education First occupy positions spanning assessment infrastructure and direct delivery channels. Pearson exemplifies the standardized testing platform archetype, anchoring bilingual proficiency validation across multiple continents. EF Education First represents the immersive experience operator model, sustaining camp-format delivery that competes with institutional enrollment. Duolingo sits within the mobile-native challenger tier, extending gamified reach beyond traditional school-based channels through device-native consumption patterns.
| Leading Market Players |
|---|
| Nord Anglia |
| Pearson Education |
| EF Education First |
| Duolingo |
| McGraw-Hill Education |
| Huijia Education |
| Cogdel Education Group |
| New Oriental |
| Macmillan Education |
| Others |
Pricing and Supply Chain Analysis
Adaptive learning algorithm adoption in Southeast Asian international schools is displacing conventional facilitator-led instruction, simultaneously compressing instructor-to-student ratios and redistributing value capture toward curriculum licensors with scalable technology platforms. This substitution dynamic concentrates pricing power among certified providers with proprietary assessment infrastructure while fragmenting revenue across device-native delivery channels.
Pricing Analysis
Cost-plus contracts with CELTA/DELTA certification indexation dominate institutional procurement between public school districts and bilingual program providers. Three-tier pricing structure across premium immersion, standard dual-language, and economy transitional tiers separates credential-bearing international schools from district-contracted operators. Price differentiation rests on facilitator certification grade and adaptive technology integration depth. Cost compression in economy tiers is intensifying because Duolingo's gamified mobile delivery extends downward price pressure. Public school districts exhibit highest price sensitivity; expatriate families in Shanghai and Beijing demonstrate lowest sensitivity due to credential portability requirements.
Supply Chain Analysis
Just-in-time instructor deployment prevails among camp-format operators, while strategic stockpiling of certified bilingual educators characterizes premium international school chains preparing for multi-year expansion cycles. Geographic supply concentrates in the United Kingdom, Australia, and Canada as source markets for CELTA/DELTA-credentialed instructors. Raw material dependencies include proprietary curriculum licensing, psychometric assessment validation, and adaptive learning algorithm development. Single-source vulnerability around qualified educator pipelines creates structural risk when certification completion cycles extend beyond eighteen months. Distribution runs through direct institutional procurement for public school districts and household-direct enrollment for premium immersion tracks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Curriculum licensing and recurring assessment validation revenue layers are expanding faster than physical program delivery, transforming bilingual education into a service-attach business where technology platforms capture margin from institutional relationships.
For Market Incumbents: Secure exclusive CELTA/DELTA certification partnerships with established providers to constrain competitor access to qualified instructor pipelines. Consolidate adaptive learning algorithm capabilities through targeted capability acquisition, defending against Duolingo's mobile-native displacement of traditional enrollment channels. For New Entrants and Emerging Players: Accelerated CELTA/DELTA fast-track programs through regional training partnerships in Vietnam and Indonesia offer the most penetrable entry path. Target Southeast Asian private international school expansion corridors where dual-language curriculum demand outstrips certified supply. Pursue white-label curriculum licensing to established school chains rather than building proprietary physical footprints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed international school operators seeking technology platform integration to sustain premium tuition positioning. Long-term viability hinges on recurring assessment revenue streams with institutional lock-in across multi-year contracts. Monitor CELTA/DELTA certification completion rates as the critical inflection indicator; sustained compression signals margin pressure for labor-dependent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Learning Platform Integration | Pearson Education's assessment infrastructure anchors bilingual proficiency validation across multiple continents. |
| Certification Pipeline Partnership | CELTA/DELTA fast-track agreements in Vietnam constrain competitor access to qualified instructor supply. |
| Curriculum Licensing Expansion | Project-based learning methodology licensing generates recurring high-margin revenue for certified Southeast Asian providers. |
| Mobile-First Delivery Convergence | Duolingo's gamified platform extends reach beyond institutional channels through device-native consumption patterns. |
| Regional Regulatory Compliance Investment | China's Ministry of Education Mandarin-English ratio mandates determine market access for foreign curriculum providers. |
Research Methodology
Initial hypotheses were tested against primary input from bilingual program directors, curriculum development leads, international school operations executives, and public school district procurement officers, then refined through secondary validation. Primary research combined structured interviews with institutional decision-makers and household expenditure surveys across Shanghai, Beijing, and Singapore. Secondary sources included China's Ministry of Education policy filings, Ofsted inspection frameworks, France's Ministry of National Education curriculum regulations, and international school enrollment databases. Bottom-up segment sizing triangulated against top-down market reconstruction from assessment platform revenue disclosures.
Variance decomposition across program type, teaching methodology, age group, and class size dimensions isolated growth contribution by segment. CAGRs were derived from enrollment trajectory modeling and tuition pricing elasticity estimates across the projection horizon. Forecast inputs incorporated CELTA/DELTA certification completion cycle data, regulatory mandate implementation timelines, and adaptive learning technology adoption curves in Southeast Asian international schools.
Decision-makers should treat outputs as directional under assumptions of sustained urban household demand concentration and stable certification pipeline throughput; material deviation would warrant model refresh. Revision becomes warranted when regulatory language ratio mandates or teacher qualification requirements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
Online Language Learning Market
Language Learning and Training
English Learning for Children Market
Language Learning and Training
Vocational English Course Counselling Solution Market
Language Learning and Training
English Learning App Market
Language Learning and Training
Global Language Service Market
Language Learning and Training
Language Learning Games Market
Language Learning and Training
Digital English Learning Market
Language Learning and Training
Language Learning Software Market
Language Learning and Training
Cloud Based Language Learning Market
Language Learning and Training
Global Digital English Language Learning Market