
 Bag-In-Tube Market | 2026-2036
Bag-In-Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-In-Tube Market Analysis
Premium barrier-grade specifications is redrawing competitive boundaries in bag-in-tube packaging. Smurfit Kappa leverages its European fiber-based infrastructure to anchor composite tube supply for food and cosmetic brands. Mondi Group specializes in high-barrier foil-laminate constructions that sustain shelf-life claims for pharmaceutical clients. Amcor competes through global scale in flexible bag extrusion, extending its reach across multiple closure and material configurations.
A bag-in-tube system combines an inner collapsible flexible pouch with an outer rigid or semi-rigid cylindrical shell, typically employing multi-layer coextruded films with oxygen transmission rates below 0.1 cc per square meter per day to preserve product integrity across viscous creams, gels, and liquid formulations. The design evacuates over 95 percent of contents through progressive collapse, eliminating waste in high-value pharmaceutical and cosmetic applications. Composite tubes lead in unit volume due to established converting infrastructure, while foil bags command superior margin pools where ultra-low permeability is non-negotiable for oxygen-sensitive drug formulations. Flexible bags represent the fastest-expanding category as personal care brands seek lightweight, ship-efficient alternatives to conventional rigid packaging.
FDA regulations on pharmaceutical container closure integrity and EMA standards for extractables and leachables testing shape material selection and validation protocols for bag-in-tube suppliers serving regulated drug markets. REACH restrictions on certain plasticizers and the EU Packaging and Packaging Waste Directive drive converters toward mono-material and recyclable barrier structures. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to prioritize regional compliance specialization or pursue cross-certification strategies that span multiple regulatory jurisdictions.
Market Dynamics
REACH compliance across the European Union is accelerating material substitutions away from conventional plastics, forcing converters to revalidate multi-layer barrier constructions and recertify pharmaceutical container closure systems. This regulatory compression is redrawing supplier capabilities and segment access rules.
Growth Catalysts
- Pharmaceutical serialization mandates:Track-and-trace requirements in the EU and US are driving demand for integrated bag-in-tube systems with embedded authentication features and tamper-evident closures.
- South Korea's K-beauty export engine:Premium skincare brands in Seoul are converting rigid bottle lines to bag-in-tube formats to achieve airless dispensing and extended shelf-life claims for export markets.
- Mono-material recyclability:Advances in polyethylene-based barrier films are enabling converters to meet EU Packaging and Packaging Waste Directive targets without sacrificing oxygen transmission performance.
Market Restraints
- Specialized resin supply concentration:Ethylene vinyl alcohol copolymer production clusters in Japan and the US create vulnerability for European converters dependent on just-in-time barrier film supply.
- Extractables validation timelines:EMA standards for leachables testing extend pharmaceutical qualification cycles by 12-18 months, freezing supplier switches mid-contract.
- Rigid bottle substitution economics:Polypropylene and glass alternatives retain cost advantages at volume for mid-tier cosmetic brands unwilling to absorb bag-in-tube conversion premiums.
Strategic Opportunities
- India's pharmaceutical packaging corridor:CDSCO's alignment with ICH guidelines is opening pathways for EU-certified bag-in-tube suppliers to serve domestic injectables and ophthalmic formulations.
- Connected packaging convergence:Integration of near-field communication tags with bag-in-tube closures enables cold-chain verification and patient adherence monitoring for biologics.
- Direct-to-consumer refill systems:Personal care brands are piloting mail-flexible bag-in-tube cartridges that slash shipping cube and enable subscription-based replenishment models.
Industry Challenges
- Multi-layer coextrusion expertise scarcity:Qualified technicians capable of calibrating nine-layer barrier film lines command premium wages in Germany and Switzerland, constraining capacity expansion.
- Legacy filling line incompatibility:Cosmetic and pharmaceutical contract manufacturers face seven-figure retooling costs to accommodate bag-in-tube web handling and crimp-seal verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-In-Tube Market |
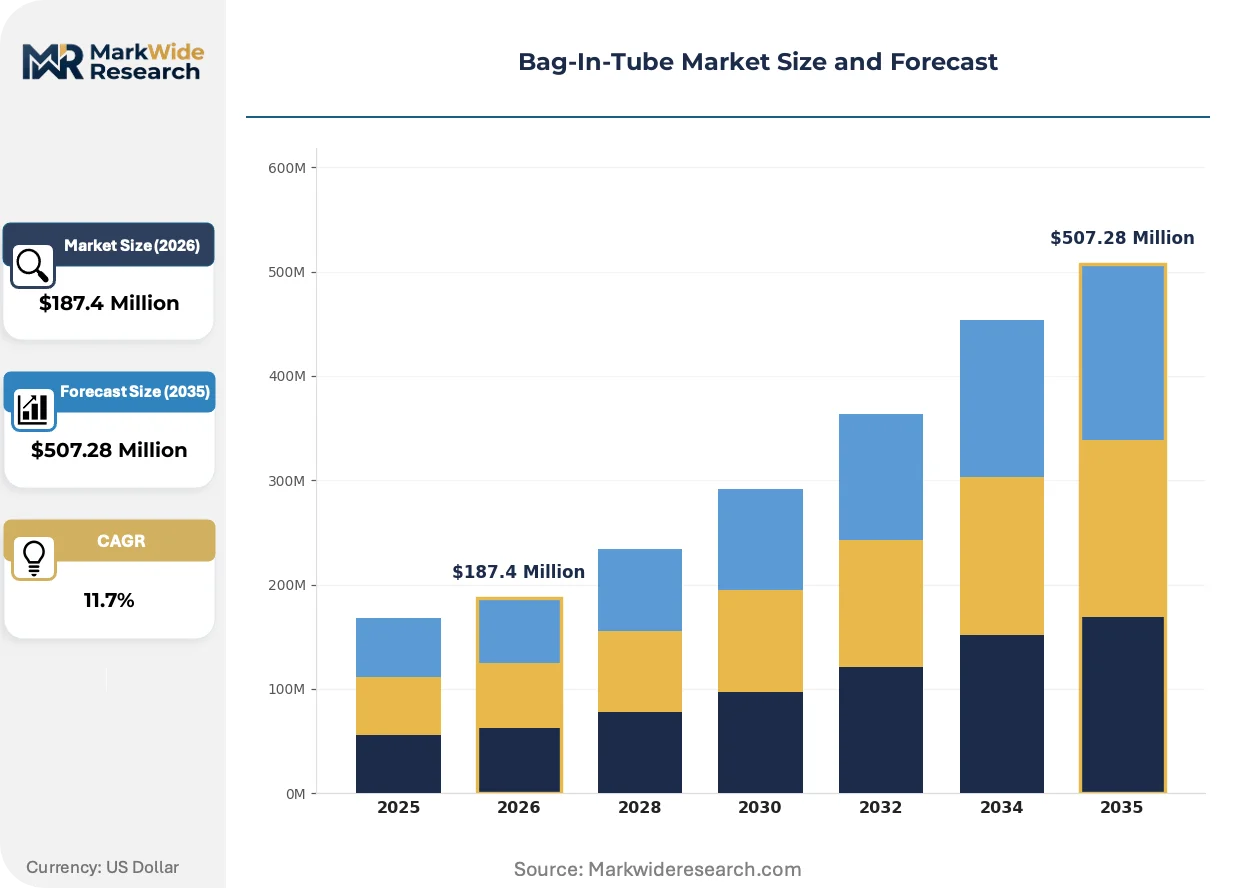
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Plastic Tubes, Composite Tubes, Foil Bags End Use Industry: Cosmetics, Pharmaceuticals, Food Packaging, Household Products Material: LDPE, HDPE, Polypropylene, Aluminium Closure Type: Screw Caps, Spout Caps, Peel-off Caps, Others |
| Companies Covered | Smurfit Kappa, DS Smith, Amcor, Mondi Group, Liqui-Box, Industri-Bag, Tecnicam S.r.l., Gualapack, FrontPac AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-In-Tube Market Emerging Trajectories
Barrier material science and regulatory compliance protocols are diverging simultaneously, creating parallel innovation tracks for premium pharmaceutical specifications and mass-market recyclable alternatives. Converters must now maintain dual qualification pathways.
Biodegradable barrier films incorporating polyhydroxyalkanoate layers are fragmenting the traditional fossil-based film market. Early adopters in French organic cosmetics are validating compostable bag-in-tube systems for premium positioning. This material shift is compressing conventional multi-layer structures into commodity-margin segments while opening certification-gated premium tiers.
EMA's revised guidelines on elemental impurities in pharmaceutical packaging are forcing converters to document raw material provenance and eliminate specific catalyst residues from ethylene polymerization processes. Suppliers serving the German pharmaceutical corridor are investing in dedicated clean-room extrusion lines to preempt audit failures. The compliance burden falls heaviest on mid-tier converters lacking in-house analytical chemistry capabilities.
Brand procurement teams are consolidating supplier relationships around full-service packaging partners capable of delivering tube, bag, closure, and decoration from single-source accountability. This bundling preference is displacing component-specialist vendors in the cosmetics segment. The shift is most visible in South Korea, where Amorepacific and LG H&H have reduced their qualified bag-in-tube supplier bases by 40 percent since 2022.
Bag-In-Tube Market Segmentation
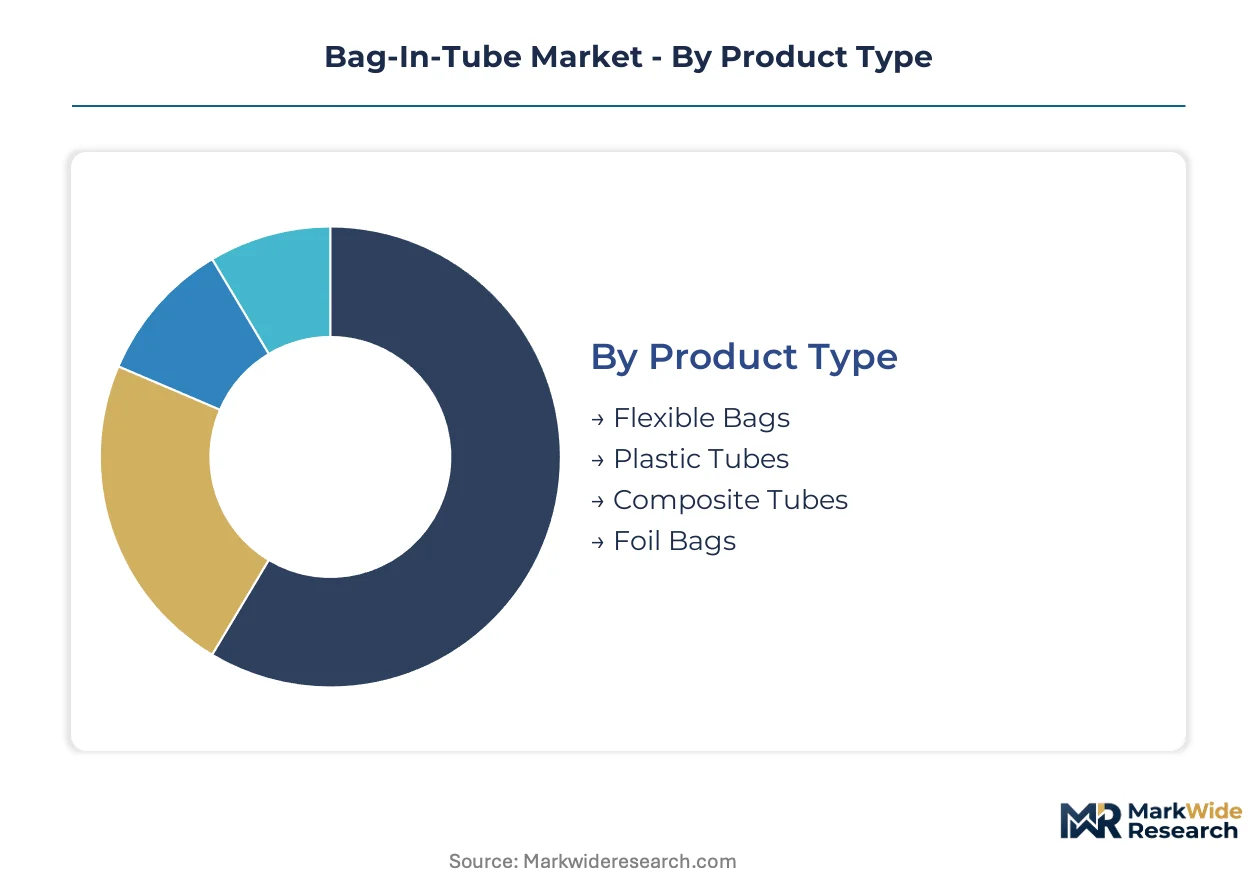
Bag-in-tube packaging serves divergent performance requirements across pharmaceutical sterility claims, cosmetic shelf-life extension, and food oxygen barrier needs. Segmentation reveals where converters must maintain dual qualification pathways for premium barrier specifications versus recyclable mono-material alternatives.
Product Type:
Channel mix varies sharply: pharmaceutical and cosmetic brands source composite tubes and foil bags through designated packaging distributors with clean-room handling capabilities, while flexible bags flow direct-to-brand for personal care refill systems.
- Composite Tubes:Multi-layer paperboard-foil-plastic laminates form the outer cylindrical shell, with established converting infrastructure concentrated in Germany and France. Cosmetic brands in Seoul and Paris specify these for premium skincare lines requiring structural rigidity with collapsible inner pouches.
- Flexible Bags:Coextruded films with sub-0.1 cc oxygen transmission rates enable progressive collapse evacuating over 95 percent of viscous contents. Personal care brands piloting direct-to-consumer refill systems in South Korea and France are driving specification shifts toward lightweight, ship-efficient formats.
- Plastic Tubes:Mono-material polyethylene constructions address EU Packaging and Packaging Waste Directive recyclability targets.
- Foil Bags:Aluminium-laminate constructions serve oxygen-sensitive pharmaceutical formulations where ultra-low permeability commands specification premiums.
Composite tubes dominate installed base. Flexible bags are where expansion concentrates.
End Use Industry:
Cost tier stratification separates validated pharmaceutical systems from mass-market cosmetic and food applications.
- Pharmaceuticals:EMA extractables and leachables testing requirements, plus FDA container closure integrity mandates, create certification-gated supply relationships. German packaging corridors anchor demand for barrier-grade foil-laminate systems serving injectables and ophthalmic formulations.
- Cosmetics:Premium skincare brands in France and South Korea convert rigid bottle lines to bag-in-tube formats for airless dispensing claims. REACH compliance accelerates material substitutions toward mono-material recyclable structures for mass-market lines.
- Food Packaging:Oxygen barrier specifications for sensitive formulations drive foil-laminate adoption.
- Household Products:Cost-sensitive applications favor standard composite tube constructions.
Pharmaceuticals command margin premiums. Cosmetics are climbing the fastest.
Material:
Volume concentration sits with polyethylene resins, while margin pools accrue to aluminium barrier layers and specialized copolymers.
- LDPE:Low-density polyethylene enables flexible film extrusion for collapsible inner pouches, with converters in Germany and Switzerland calibrating multi-layer coextrusion lines to meet pharmaceutical oxygen barrier specifications.
- Aluminium:Foil laminates provide sub-0.01 cc oxygen transmission rates essential for biologics and oxygen-sensitive drug formulations, with supply concentration in Japanese and US ethylene vinyl alcohol copolymer production creating vulnerability for European converters.
- HDPE:High-density variants serve rigid outer tube applications requiring structural integrity.
- Polypropylene:Alternative for cost-optimized cosmetic applications where barrier requirements permit.
LDPE dominates unit volume. Aluminium captures premium tier positioning.
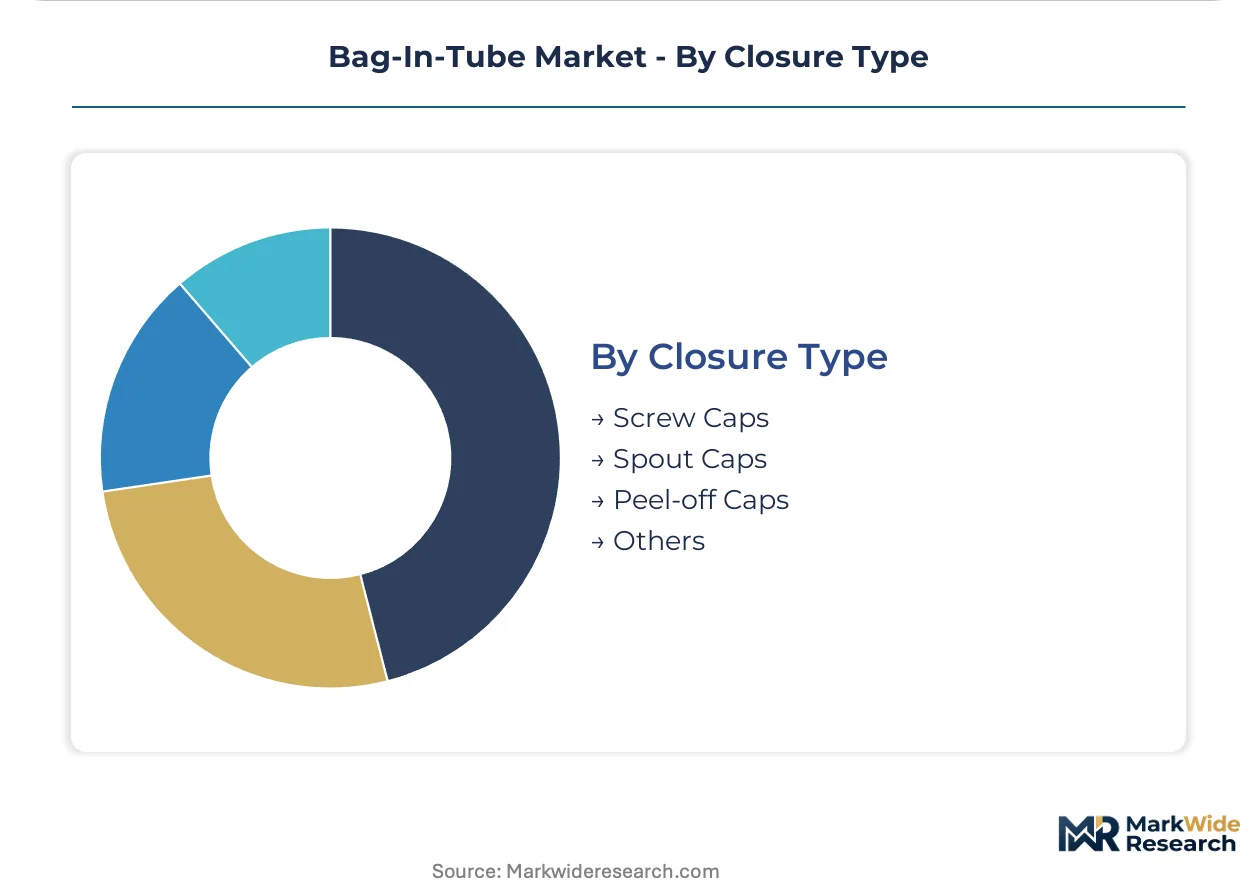
Closure Type:
Application requirements dictate closure selection: tamper-evident and authentication-integrated systems for pharmaceuticals, precision dispensing for cosmetics, convenience features for household products.
- Screw Caps:Standard threaded closures dominate cosmetic and food applications, with South Korean brands specifying precision-molded variants for premium skincare positioning.
- Spout Caps:Directional dispensing designs serve viscous pharmaceutical creams and gels, with integrated authentication features addressing EU and US track-and-trace serialization mandates.
- Peel-off Caps:Single-use tamper-evident systems for sterile pharmaceutical applications.
- Others:Specialty closure configurations including crimp-seal pharmaceutical systems.
Screw caps anchor mass-market supply. Spout caps are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical packaging corridor exports barrier-grade foil-laminate systems to French cosmetic laboratories and South Korean skincare manufacturers, creating a transcontinental trade-flow triangle anchored by REACH-compliant material specifications.
Germany
EMA extractables and leachables testing requirements drive demand for validated container closure systems in the Rhine-Main pharmaceutical cluster. REACH restrictions on plasticizers force converters in Baden-Württemberg to revalidate multi-layer barrier constructions. The Stuttgart-Tübingen corridor anchors clean-room extrusion capacity for oxygen-sensitive drug formulations.
France
ANSM pharmaceutical packaging standards and premium organic cosmetic positioning create dual demand tracks for barrier and compostable formats. The EU Packaging and Packaging Waste Directive accelerates mono-material adoption in Île-de-France formulation facilities. Lyon-based converters supply airless dispensing systems to Parisian skincare brands.
South Korea
MFDS alignment with ICH guidelines opens export pathways for K-beauty brands adopting bag-in-tube airless technology. Seoul Capital Area formulation labs specify sub-0.1 cc oxygen transmission rates for shelf-life extension claims. Busan-Ulsan polymer processing clusters feed collapsible film supply to Gyeonggi-do cosmetic contract manufacturers.
United States
FDA container closure integrity mandates and pharmaceutical serialization requirements drive specification premiums for track-and-trace integrated systems. The New Jersey-Pennsylvania pharmaceutical corridor demands tamper-evident closure validation. California personal care brands pilot direct-to-consumer refill formats with lightweight flexible bag configurations.
India
CDSCO's ICH guideline alignment creates regulatory pathways for EU-certified suppliers entering domestic injectables markets. Maharashtra's pharmaceutical formulation belt in Mumbai-Pune generates demand for barrier-grade primary packaging. Gujarat polymer processing hubs supply coextruded films meeting oxygen barrier specifications for ophthalmic applications.
Bag-In-Tube Market Vendor Landscape
Listed leaders compete with private specialists across barrier film technology and regional certification access. The supplier base organizes around three tiers: multinational converters with global extrusion networks, mid-cap composite tube specialists with European fiber infrastructure, and regional flexible packaging players with pharmaceutical clean-room capabilities. Dominant competitive moves include capacity expansion in nine-layer coextrusion lines and strategic partnerships bridging tube, bag, and closure integration.
Among publicly traded packaging conglomerates, Smurfit Kappa and Mondi Group exemplify scale-driven archetypes leveraging European manufacturing footprints, while Amcor occupies a position spanning flexible film extrusion across multiple closure configurations. Private specialists including Tecnicam S.r.l. and FrontPac AB represent regional fabrication expertise concentrated in Italian and Nordic markets respectively. The competitive terrain rewards full-service accountability bundling tube, bag, and decoration from single-source relationships, compressing margins for component-specialist vendors unable to offer integrated qualification pathways.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| Amcor |
| Mondi Group |
| Liqui-Box |
| Industri-Bag |
| Tecnicam S.r.l. |
| Gualapack |
| FrontPac AB |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between German pharmaceutical formulators and Baden-Württemberg converters lock in ethylene vinyl alcohol copolymer supply access while freezing price visibility across the nine-layer coextrusion value chain. These bilateral agreements tether barrier film pricing to resin index movements and clean-room certification maintenance costs.
Pricing Analysis
Next-generation mono-material polyethylene barrier constructions command 15-25% premiums over legacy multi-layer foil-laminate systems. Three-tier pricing structure across premium pharmaceutical-grade, standard cosmetic-grade, and economy household-grade specifications separates validated EMA-compliant systems from mass-market alternatives. Cost compression in standard cosmetic tiers is intensifying because South Korean brands are consolidating supplier relationships around full-service bundling. Mid-tier cosmetic contract manufacturers exhibit highest price sensitivity, while German pharmaceutical corridors show lowest sensitivity due to non-negotiable barrier performance requirements.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for ethylene feedstock shipments from the Middle East to European polymer processors creates periodic resin price volatility that cascades through German extrusion lines. Supply concentrates in Germany, France, and South Korea for finished bag-in-tube systems, while ethylene vinyl alcohol copolymer production draws from Japan and the US. Single-source vulnerability sits with Japanese resin suppliers serving European barrier film converters. Distribution runs through designated pharmaceutical packaging distributors with clean-room handling capabilities for regulated segments, while personal care refill systems flow direct-to-brand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a regulatory compliance investment cycle as REACH-aligned material substitutions mature, positioning converters to capture margin recovery through next-generation mono-material barrier qualifications.
For Market Incumbents: Consolidate supplier relationships around full-service packaging partnerships capable of delivering tube, bag, closure, and decoration from single-source accountability. Acquire clean-room extrusion capacity in the Stuttgart-Tübingen corridor to preempt EMA audit failures. Biodegradable barrier film specialists represent the primary emerging entrant threat to fossil-based margin pools. For New Entrants and Emerging Players: Anchor in India's Maharashtra pharmaceutical formulation belt where CDSCO's ICH alignment creates regulatory pathways for EU-certified suppliers. Target ophthalmic and injectable applications where barrier-grade foil-laminate supply remains concentrated among incumbent specialists. Pursue joint qualification pathways with Gujarat polymer processors to establish domestic coextrusion credibility. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-service converters with integrated tube-bag-closure capabilities over component-specialist vendors. Five-to-ten year viability hinges on mono-material recyclability certification access and clean-room extrusion asset ownership. Watch South Korean K-beauty export volumes as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Room Extrusion Capacity Expansion | EMA extractables testing requirements in Germany demand validated container closure manufacturing environments. |
| Mono-Material Barrier Film Qualification | EU Packaging and Packaging Waste Directive compliance opens premium positioning for recyclable polyethylene systems. |
| Integrated Authentication Feature Development | FDA pharmaceutical serialization mandates require tamper-evident closure integration with track-and-trace systems. |
| Direct-to-Consumer Refill System Partnerships | South Korean personal care brands pilot lightweight flexible bag configurations for subscription replenishment models. |
| Biodegradable Film Certification Investment | French organic cosmetic positioning validates compostable polyhydroxyalkanoate layer systems for premium tier access. |
Methodological Framework
A spread of perspectives from pharmaceutical packaging procurement managers, cosmetic brand supply chain directors, barrier film extrusion technicians, and EMA regulatory consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA container closure integrity guidance, EMA extractables and leachables protocols, REACH substance restriction databases, and EU Packaging and Packaging Waste Directive implementation timelines. Bottom-up unit economics from German and South Korean converter operations were triangulated against top-down demand modeling from pharmaceutical and cosmetic end-use segments.
Segmentation dimensions modeled include product type, end-use industry, material composition, closure configuration, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base growth rates, substitution elasticity between rigid bottle and bag-in-tube formats, and barrier film capacity expansion pipelines. Forecast inputs incorporated pharmaceutical serialization mandate implementation schedules and K-beauty export volume trajectories without year-specific anchoring.
Decision-makers should treat outputs as directional under assumptions of sustained REACH compliance timelines and stable ethylene vinyl alcohol copolymer supply flows from Japanese producers; material deviation in resin availability or regulatory acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as biodegradable barrier film certification pathways and extended producer responsibility framework evolutions unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Counter Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Woven Bags Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Mesh Bags Market