
 Backup Power Systems Market | 2026-2036
Backup Power Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Backup Power Systems Market Outlook
Data center operators are unwinding traditional reliance on diesel-only standby configurations. Generac anchors the North American residential standby segment through extensive dealer networks and automated transfer switch integration. Tesla Energy differentiates with battery-based backup systems that pair with solar generation and grid services. Cummins sustains industrial leadership through in-house engine manufacturing and global service infrastructure.
Backup power systems encompass generators, uninterruptible power supplies, inverters, and fuel cells designed to maintain electrical continuity during grid interruption, with diesel units typically providing full-load runtime measured in hours while battery systems deliver seamless transition measured in milliseconds. The product mix spans generators, UPS systems, inverters, and fuel cells, with diesel generators retaining the largest installed base though lithium-ion battery systems capture the fastest expansion in data center and telecom applications. Application demand distributes across residential, commercial, industrial, and telecom verticals, with industrial and data center segments commanding premium pricing due to zero-tolerance uptime requirements.
The EPA regulates stationary engine emissions under Tier 4 standards, while NFPA 110 and NEC Article 700 mandate installation and testing protocols for emergency and legally required standby systems. OSHA workplace safety requirements and state-level building codes further shape product certification and deployment specifications. Stakeholders must monitor the pace of battery cost decline relative to natural gas infrastructure availability when sizing capital commitments for new backup power capacity.
Market Dynamics
The backup power systems market is undergoing a fundamental reconfiguration as diesel generator architectures confront EPA Tier 4 emissions compliance costs while lithium-ion battery economics achieve grid-competitive total cost of ownership in stationary applications.
Growth Catalysts
- Data Center Compute Density:AI training clusters are driving emergency power specifications toward 10-50 MW per facility, mandating modular generator-battery hybrid architectures that can scale with rack power draw.
- NFPA 110 Testing Mandates:Monthly load-bank testing requirements for Level 1 emergency systems are accelerating replacement cycles for aging diesel units that cannot meet runtime or emissions thresholds.
- Natural Gas Infrastructure Expansion:Pipeline network buildouts in Texas, Pennsylvania, and North Dakota are enabling gas-fired reciprocating engines as lower-emission alternatives to diesel in baseload standby applications.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet synchronous generators and power electronics depend on neodymium and copper windings, with price swings compressing margins on fixed-price infrastructure contracts.
- Engine Block Casting Concentration:Foundry capacity for large-bore diesel and gas engine blocks concentrates in India and China, creating single-source vulnerability for OEMs without captive casting operations.
- Battery Degradation in Temperature Extremes:Lithium-ion capacity fade accelerates above 35°C ambient, limiting deployment in unconditioned outdoor enclosures across the Gulf Coast and Southwest without active thermal management.
Strategic Opportunities
- Telecom Tower Electrification:Rural cell sites in sub-Saharan Africa and Southeast Asia remain diesel-dependent, creating white space for solar-hybrid microgrids with 72-hour battery autonomy.
- Inflation Reduction Act Storage Credits:The standalone storage ITC is enabling battery-only backup configurations for commercial buildings that previously required generator redundancy.
- Grid-Interactive UPS Convergence:Double-conversion UPS systems with bi-directional inverters can provide frequency regulation and peak shaving, unlocking revenue streams beyond outage protection.
Industry Challenges
- Commissioning Engineer Scarcity:Parallel synchronization of multiple generators and protective relay programming require specialized field technicians, with training pipelines lagging deployment timelines by 18-24 months.
- Legacy Fuel System Retrofit Complexity:Underground storage tank replacement and fuel polishing system upgrades for EPA spill prevention compliance are extending project durations and triggering scope creep on brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backup Power Systems Market |
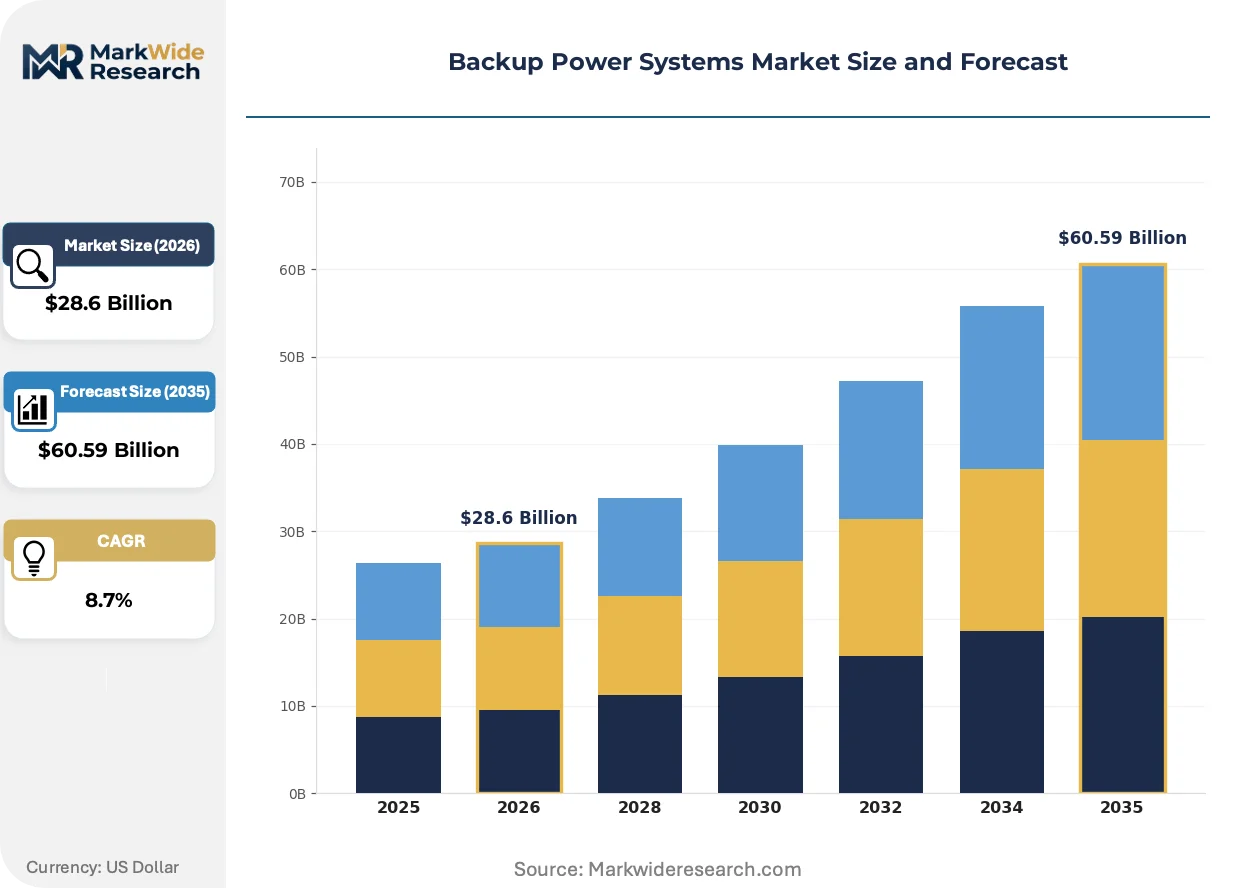
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, UPS Systems, Inverters, Fuel Cells Application: Residential, Commercial, Industrial, Telecom End User: Healthcare, Data Centers, Manufacturing, Retail Technology: DIESEL, Gas, Solar, Hybrid |
| Companies Covered | Briggs & Stratton, Tesla Energy, Generac, BYD Energy Storage, CATL, Kohler, Winco, Sungrow, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backup Power Systems Market Strategic Shifts
Stationary power backup is fragmenting into two distinct technology stacks: high-duration diesel and gas systems for industrial resilience, and fast-response batteries for seamless power quality. This divergence is reshaping R&D allocation, manufacturing footprints, and service network requirements across the value chain.
Solid-state battery chemistry is bifurcating the data center UPS segment. Lithium iron phosphate cells now dominate 15-minute to 4-hour runtime applications, displacing valve-regulated lead-acid in new builds. Hyperscale operators in Northern Virginia and Dallas-Fort Worth are specifying containerized battery systems with 10-year performance guarantees, compressing the addressable market for traditional static switchgear and flywheel alternatives. The technology is bifurcating vendor relationships—battery integrators now compete directly with generator OEMs for prime power contracts.
EPA's 2024 reconsideration of particulate matter standards for stationary engines is tightening compliance windows for diesel operators. The industrial consequence is accelerated capital planning for selective catalytic reduction and diesel particulate filter retrofits, with some operators advancing replacement timelines by 3-5 years. Data center and healthcare segments in California, Texas, and New York are most affected, with many facilities now modeling total cost of ownership for natural gas conversions against Tier 4 Final diesel with aftertreatment.
Asset-light power-as-a-service contracts are displacing capital purchase models in commercial and light industrial segments. Third-party providers own, operate, and maintain backup systems, charging monthly availability fees and energy-only rates for runtime. This shift concentrates procurement authority with energy service companies and away from traditional electrical contractors. The model is most visible in retail, hospitality, and multi-tenant office buildings in Florida and California, where hurricane and wildfire risk premiums make operational transfer attractive to CFOs seeking balance sheet efficiency.
Backup Power Systems Market Segmentation
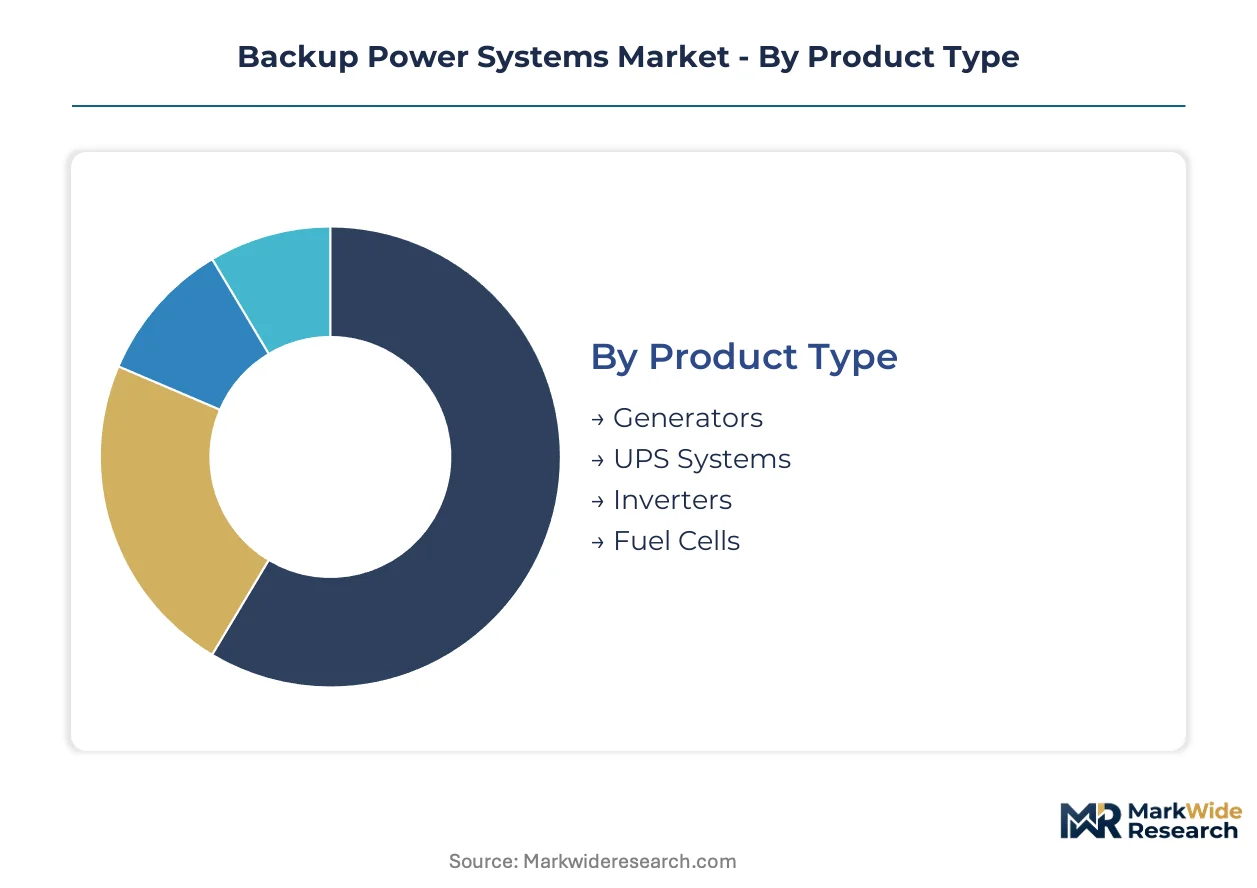
Backup power architectures fragment across four distinct classification schemes, each revealing substitution threats and margin pressure points. Product type and technology dimensions expose the diesel-to-battery transition, while application and end-user splits illuminate where uptime premiums command pricing power.
Product Type:
Diesel generator substitution pressure is most acute in segments where lithium-ion economics have crossed total-cost parity thresholds.
- Generators:Reciprocating engines burning diesel or natural gas deliver full-load runtime measured in hours. Data centers in Texas and Virginia specify 10-50 MW modular arrays to match AI cluster density, though EPA Tier 4 compliance costs accelerate replacement timelines.
- UPS Systems:Double-conversion and line-interactive topologies provide millisecond-scale transfer with power conditioning. Northern Virginia hyperscale operators now demand containerized lithium iron phosphate configurations with 10-year performance guarantees, displacing valve-regulated lead-acid in new construction.
- Inverters:Bi-directional power electronics enable grid-interactive functionality for solar-hybrid microgrids.
- Fuel Cells:Solid oxide and proton exchange membrane systems offer zero-emission backup for California healthcare facilities facing air quality mandates.
Generators anchor the volume base while UPS systems gain share at the steepest rate.
Application:
Cost tier stratification separates price-sensitive residential installations from industrial segments where downtime costs justify premium configurations.
- Residential:Single-family and multi-family installations prioritize automated transfer switch integration with 8-20 kW natural gas or propane standby units. Florida hurricane-season outages and California PSPS events drive replacement cycles for aging portable generator stock.
- Commercial:Retail, hospitality, and office buildings balance capital efficiency against code-mandated emergency lighting and elevator power. Power-as-a-service contracts concentrate procurement authority with energy service companies in Florida and California markets.
- Industrial:Continuous-process manufacturing and petrochemical facilities specify N+1 redundancy with 72-hour fuel autonomy.
- Telecom:Rural cell sites in sub-Saharan Africa and Southeast Asia remain diesel-dependent, creating white space for solar-hybrid microgrids.
Industrial applications command the highest per-kilowatt pricing while telecom infrastructure shows the most rapid technology turnover.
End User:
Customer type determines procurement authority structure, with healthcare and data center buyers centralizing specifications at the corporate engineering level.
- Healthcare:Hospitals and outpatient surgery centers face NFPA 99 and Joint Commission mandates for Level 1 emergency power with monthly load-bank testing. California, Texas, and New York facilities model natural gas conversions against Tier 4 Final diesel with aftertreatment.
- Data Centers:Hyperscale and colocation operators specify modular architectures that scale with rack power draw. Northern Virginia and Dallas-Fort Worth clusters now require battery-gas hybrid configurations for 10-50 MW facilities.
- Manufacturing:Automotive and semiconductor fabs demand voltage sag ride-through and seamless transfer to protect batch processes.
- Retail:Grocery and big-box chains prioritize refrigeration continuity during multi-hour outages, favoring rental generator programs over capital purchase.
Healthcare anchors regulatory-driven replacement demand while data centers set the pace for technology adoption.
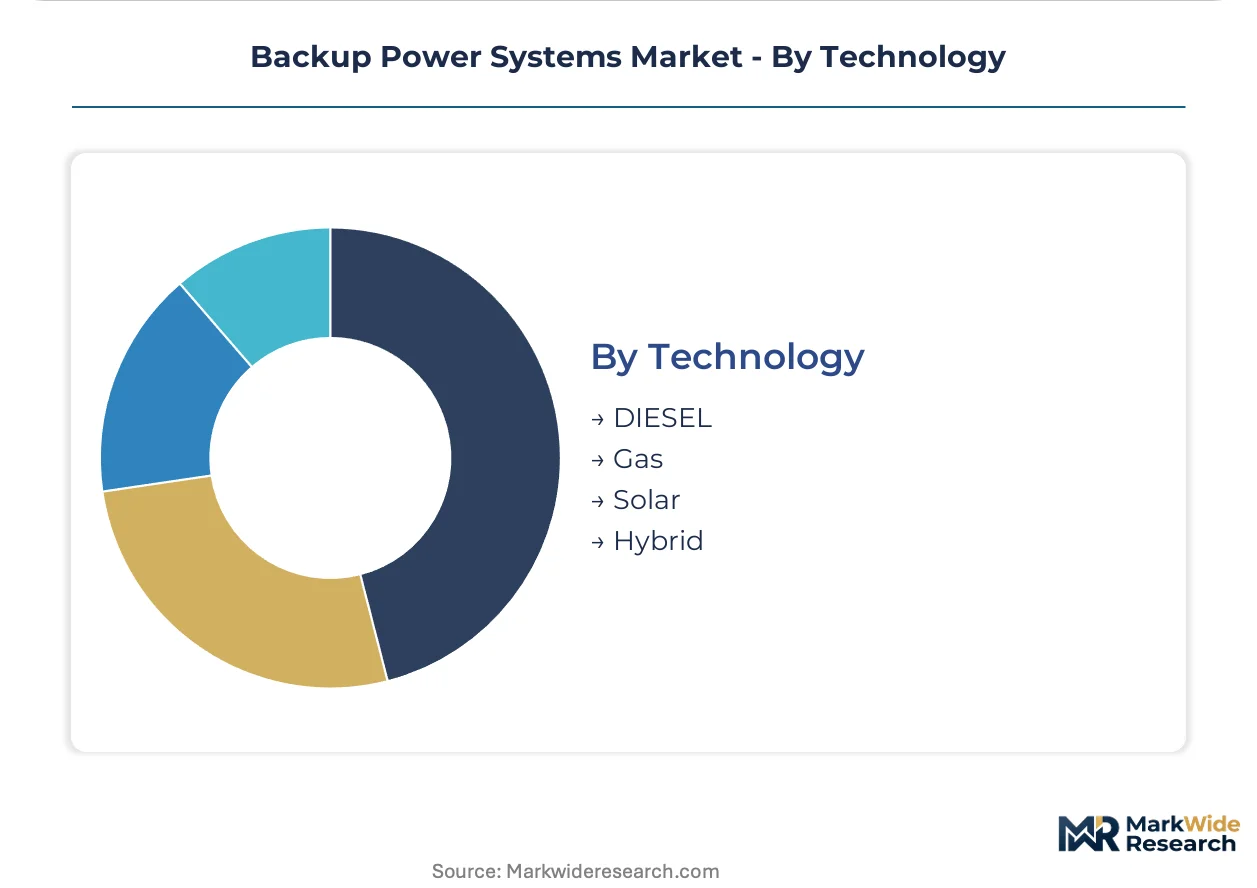
Technology:
Supply concentration in engine block casting and power electronics manufacturing shapes competitive dynamics across fuel types.
- DIESEL:Compression-ignition engines retain the largest installed base though face EPA particulate matter standard tightening. Foundry capacity for large-bore blocks concentrates in India and China, creating single-source vulnerability for OEMs without captive casting.
- Gas:Spark-ignited reciprocating engines burn pipeline natural gas or propane with lower emissions profiles. Texas, Pennsylvania, and North Dakota pipeline buildouts enable baseload standby applications previously diesel-dependent.
- Solar:Photovoltaic arrays paired with battery storage serve off-grid and weak-grid telecom towers in emerging markets.
- Hybrid:Generator-battery architectures combine diesel or gas runtime with lithium-ion seamless transfer and peak shaving capability.
Diesel technology retains the largest installed footprint while hybrid configurations are climbing the fastest as data centers unwind single-fuel dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports diesel generator components and power electronics to data center operators across Northern Virginia and Dallas-Fort Worth. Chinese battery manufacturers supply lithium iron phosphate cells to European and North American integrators. Japanese engineering firms license generator synchronization technology to Southeast Asian project developers.
United States
Grid reliability concerns and hurricane-season outages drive residential and commercial installations across Florida and Gulf Coast states. EPA Tier 4 emissions standards push diesel operators toward hybrid and natural gas alternatives. Northern Virginia data center clusters now specify 10-50 MW modular generator-battery arrays to match AI compute loads.
Germany
Industrial manufacturing and chemical processing facilities demand N+1 redundancy with extended fuel autonomy. The EU Green Deal and national climate targets accelerate natural gas reciprocating engine adoption against diesel baseload. Bavaria and North Rhine-Westphalia host the densest concentration of combined heat and power backup installations.
China
Domestic data center buildouts and semiconductor fab construction create demand for megawatt-scale UPS and generator systems. MIIT energy efficiency standards and dual carbon goals mandate cleaner backup configurations. Yangtze River Delta and Pearl River Delta regions concentrate manufacturing of lithium-ion battery racks and power conversion equipment.
India
Unreliable grid infrastructure and industrial expansion sustain diesel generator demand despite air quality regulations. CEA mandates and state-level pollution control board directives tighten emissions compliance windows. Maharashtra and Gujarat manufacturing corridors deploy hybrid microgrids combining gas engines with solar-battery storage.
Japan
Earthquake preparedness and grid stability requirements sustain premium backup power specifications. METI efficiency standards and building code amendments favor natural gas and fuel cell configurations. Kanto and Kansai metropolitan areas concentrate demand from semiconductor fabs and pharmaceutical manufacturing.
Backup Power Systems Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The market structure stratifies between integrated engine manufacturers, battery system integrators, and power electronics specialists. Three archetypes dominate: legacy generator OEMs with captive foundry operations, solar-battery hybrid providers leveraging IRA credits, and power-as-a-service platforms consolidating commercial procurement. M&A activity concentrates on battery management software acquisitions and regional service network expansion.
Within the residential standby tier, Generac and Briggs & Stratton exemplify North American distribution density through dealer network models. Tesla Energy occupies a position bridging automotive battery scale with stationary storage applications. Cummins anchors industrial leadership through in-house engine manufacturing and global service infrastructure.
| Leading Market Players |
|---|
| Briggs & Stratton |
| Tesla Energy |
| Generac |
| BYD Energy Storage |
| CATL |
| Kohler |
| Winco |
| Sungrow |
| Cummins |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 certification gates supplier qualification and price differentiation simultaneously, with compliant diesel units commanding premiums over non-certified alternatives while battery integrators bypass the regulatory burden entirely through chemistry substitution. This bifurcation concentrates pricing power with OEMs possessing captive aftertreatment manufacturing or lithium iron phosphate cell supply agreements.
Pricing Analysis
Next-generation lithium iron phosphate systems price at 15-25% premiums over legacy valve-regulated lead-acid configurations, while prior-generation diesel generators face accelerated depreciation from EPA compliance retrofit mandates. Project-based contracting dominates industrial and data center segments, with price differentiation resting on NFPA 110 certification tier and geographic delivery logistics. Cost compression in residential standby units intensifies as Generac and Briggs & Stratton dealer networks compete on installation bundling. Telecom tower operators in emerging markets exhibit highest price sensitivity, while Northern Virginia hyperscale data centers prioritize performance guarantees over capital outlay.
Supply Chain Analysis
Strategic stockpiling of copper windings and neodymium permanent magnets characterizes procurement behavior among generator OEMs, contrasting with just-in-time battery cell delivery from Chinese and South Korean manufacturers. Foundry capacity for large-bore engine blocks concentrates in India and China, while power electronics fabrication centers on Taiwan and Germany. Raw material dependencies span copper, rare earth elements, and lithium carbonate, with single-source vulnerability in permanent magnet synchronous generator supply. Tariff exposure on Chinese battery cells and Indian castings compresses margins on fixed-price infrastructure contracts. Distribution runs through authorized dealer networks for residential units and direct OEM relationships for industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as lithium-ion battery economics displace diesel runtime specifications across sub-50 MW installations. Incumbents must navigate chemistry transition while preserving service revenue from the installed generator base.
For Market Incumbents: Shield installed base profitability through captive foundry investments in India or backward integration into permanent magnet supply chains. Accelerate hybrid architecture certification to capture data center demand for seamless transfer plus extended runtime. Prioritize battery management software acquisitions that lock in long-term service contracts beyond hardware replacement cycles.
For New Entrants and Emerging Players: Commissioning engineer scarcity creates immediate service-layer opportunity for specialized field technician training programs targeting parallel synchronization and protective relay programming gaps. Rural telecom tower electrification in sub-Saharan Africa and Southeast Asia offers the most penetrable geography, with solar-hybrid microgrids displacing diesel-dependent legacy infrastructure. Pursue power-as-a-service contracting models that transfer operational risk from balance-sheet-constrained commercial buyers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-only backup configurations as standalone storage ITC reduces upfront capital requirements. Long-term viability favors asset-light platforms with recurring revenue streams over manufacturing-heavy generator OEMs. Target acquisition archetypes include battery management software specialists and regional service networks with EPA-certified technician pools. Watch battery cell cost trajectories against natural gas pipeline buildout pace as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Certification | Captures AI data center demand for seamless transfer plus extended runtime capability. |
| Backward Integration into Foundry Capacity | Secures engine block supply against India-China concentration risk for large-bore manufacturing. |
| Power-as-a-Service Platform Launch | Transfers operational risk from Florida and California commercial buyers seeking balance sheet efficiency. |
| Battery Management Software Acquisition | Locks recurring service revenue beyond hardware replacement in lithium-ion transition. |
| Telecom Tower Electrification Partnership | Opens sub-Saharan Africa and Southeast Asia white space for solar-hybrid microgrid deployment. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EIA grid reliability data, FERC interconnection queues, and hyperscaler capex disclosures. Primary interviews engaged data center engineering directors, generator OEM procurement heads, battery integrator technical leads, and commercial electrical contractors across Florida, Texas, Virginia, and California markets. Secondary validation drew from NFPA code revision dockets, state-level building code amendments, and customs records for diesel generator and lithium-ion battery trade flows. Bottom-up unit economics triangulate against top-down market sizing from infrastructure investment tracking.
Segmentation dimensions modeled span product type, application vertical, end-user category, and technology fuel source across the projection horizon. The analytical framework incorporates AI compute load density trajectories, EPA emissions compliance cost curves, and battery degradation curves under temperature stress. CAGRs derive from capacity expansion announcements, replacement cycle analysis for aging diesel units, and IRA credit uptake rates in commercial building deployments. Forecast inputs include natural gas pipeline buildout timelines and foundry capacity utilization rates for large-bore engine block casting.
Underlying assumptions cover grid reliability deterioration rates, battery cell cost decline curves, and EPA enforcement intensity, with deviation risk concentrated in copper and rare earth price volatility. Forecasts reflect these assumptions without guarantee of realization. Revision becomes warranted when battery pack pricing crosses diesel total-cost-of-ownership thresholds in unconditioned outdoor installations or when EPA particulate matter standards tighten beyond current Tier 4 Final specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy & Power
Modular Battery Market
Energy & Power
Global Lithium Titanate (LTO) Batteries Market
Energy & Power
Solar Boat Market
Energy & Power
Wind Turbine Scrap Market
Energy & Power
Bio-Methane Market
Energy & Power
India Gensets Market
Energy & Power
Europe Electric Vehicle VRLA Batteries Market
Energy & Power
South Korea Electric Vehicle Charging Equipment Market
Energy & Power
Smart Grid Technology Market
Energy & Power
Float Traps Market
Energy & Power
Oilwell Spacer Fluids Market
Energy & Power
Mixed Flow Pump Market
Energy & Power
Global Ultra Efficient Solar Power Market
Energy & Power
Air Preheater Market
Energy & Power
Heat Pipe Market
Energy & Power
South-East Asia DC Distribution Network Market