
 Baby Products Detergents Market | 2026-2036
Baby Products Detergents Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Products Detergents Market Analysis
Specialty store distribution is rewriting competitive access in baby detergents as curated retail environments command premium shelf positioning and parent trust. Procter & Gamble leverages its manufacturing scale to dominate mainstream liquid formulations across mass retail channels. Seventh Generation anchors the organic segment through transparent ingredient sourcing and eco-certified supply chains. The Honest Company differentiates via direct-to-consumer subscription models that sustain recurring revenue and reduce customer acquisition costs.
Baby products detergents comprise surfactant-based cleaning formulations engineered for infant textiles and accessories, typically maintaining pH levels between 5.5 and 7.0 to prevent skin irritation while eliminating protein-based stains from formula, food, and bodily fluids. These products serve the essential commercial purpose of removing contaminants from fabrics that contact immature epidermal barriers without depositing optical brighteners, enzymes, or synthetic fragrances that trigger dermatological reactions. Liquid detergents lead absolute volume due to their dissolution efficiency in cold-water washing cycles preferred for delicate infant garments, though hypoallergenic formulations command disproportionate margin pools as parents pay premiums for dermatologist-tested certification. Pods represent the fastest-growing configuration despite safety concerns, driven by precise dosing convenience and concentrated active chemistry that reduces packaging waste.
FDA oversight of cosmetic and drug claims intersects with EPA Safer Choice certification to shape permissible marketing language and ingredient disclosure requirements for products targeting infants in the United States. The EU ECHA enforces REACH restrictions on quaternary ammonium compounds and certain ethoxylated surfactants, forcing reformulation of legacy products sold across European markets. Stakeholders must monitor evolving state-level chemical transparency laws in California and New York that mandate expanded ingredient labeling beyond federal minimums, as these jurisdictions often presage broader national standards.
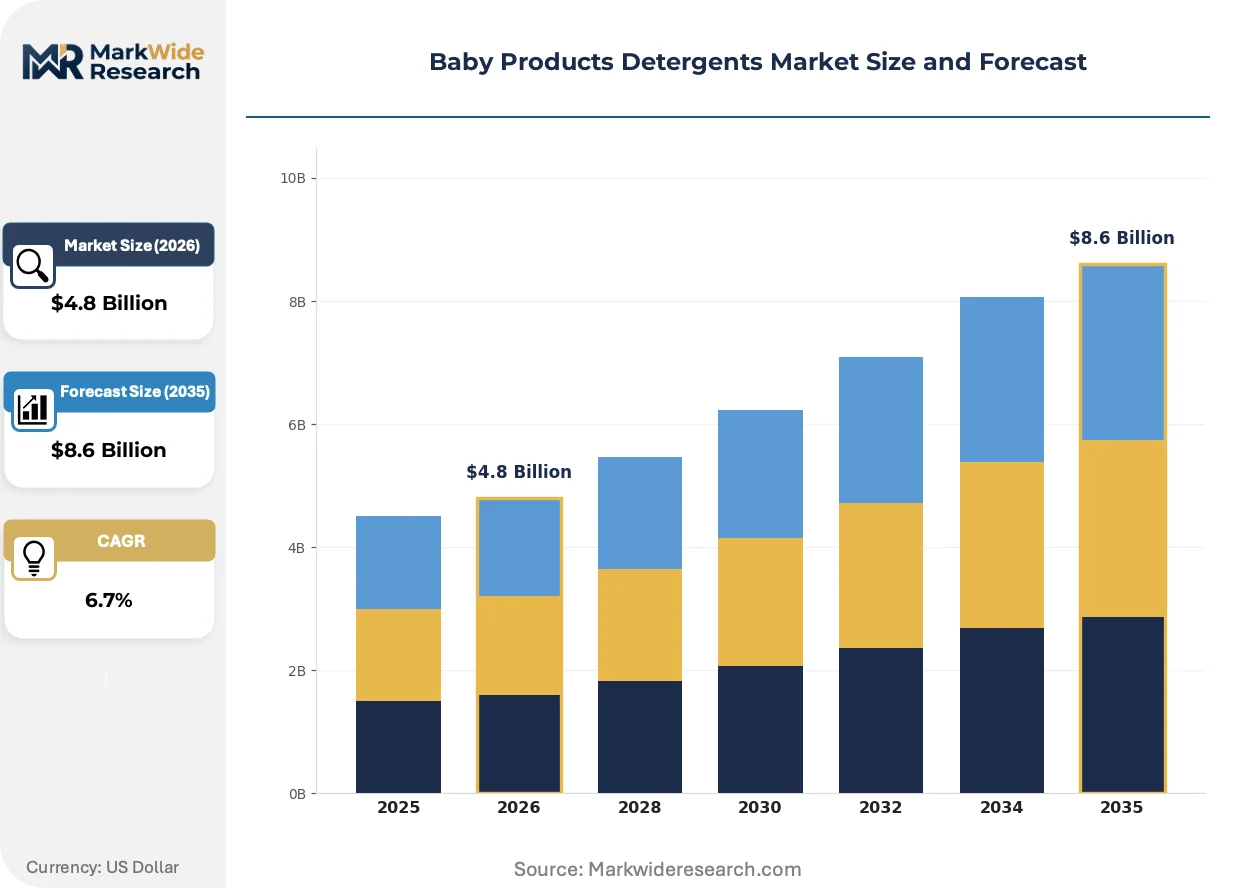
Market Dynamics
EU REACH restrictions on quaternary ammonium compounds and ethoxylated surfactants are forcing systemic reformulation across legacy product portfolios, compressing margin structures while accelerating R&D cycles for compliant alternatives.
Growth Catalysts
- Parents of infants under two years:This buyer segment prioritizes residue-free cleaning for immature epidermal barriers, creating sustained pull for hypoallergenic certification and dermatologist-tested formulations.
- REACH regulation:The EU's chemical restrictions are eliminating harsh surfactants from competing products, creating first-mover advantage for brands with pre-compliant supply chains.
- Precise dosing convenience:Pod configurations reduce packaging waste and dosing errors, aligning with parental preferences for concentrated active chemistry in compact formats.
Market Restraints
- Surfactant input volatility:Plant-derived alternatives to restricted petrochemical surfactants face agricultural commodity price swings and crop yield uncertainty.
- China supply concentration:Domestic brands expanding premium hypoallergenic lines source concentrated actives from a narrowing base of compliant chemical manufacturers.
- Cold-water dissolution limits:Enzyme-free formulations required for sensitive skin certification sacrifice stain removal efficacy in sub-30°C washing cycles.
Strategic Opportunities
- Subscription distribution models:Direct-to-consumer platforms reduce customer acquisition costs and sustain recurring revenue through automated replenishment cycles.
- Eco-certified supply chains:Transparent ingredient sourcing aligned with EPA Safer Choice certification opens premium positioning in mass retail channels previously closed to organic entrants.
- State-level chemical transparency laws:California and New York mandates for expanded ingredient labeling create competitive differentiation for brands with pre-existing disclosure infrastructure.
Industry Challenges
- Dermatological testing timelines:Pediatric patch study protocols and allergen screening extend product development cycles by 8-14 months versus conventional detergent launches.
- Legacy manufacturing reconfiguration:Dedicated production lines required to prevent cross-contamination with enzyme-containing adult detergents demand capital deployment at sub-scale volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Products Detergents Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Detergents, Powder Detergents, Pods, Bar Soaps Formulation: Organic, Hypoallergenic, Scented, Unscented Packaging Type: Bottles, Pouches, Boxes, Tubes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Kimberly-Clark, Seventh Generation, Procter & Gamble, Dongguan UFine Daily Chemical, Babyganics, Johnson & Johnson Services, The Honest Company, Pigeon Corporation, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Products Detergents Market Emerging Trajectories
Formulation chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure and parental purchasing behavior converge on transparency and convenience.
Cold-water optimized surfactant systems are migrating from niche organic portfolios toward mainstream liquid formulations. Parents operating energy-efficient home appliances increasingly demand dissolution efficiency below 30°C without sacrificing protein-based stain removal. This migration is compressing the performance gap between mass-market and specialty detergents.
EPA Safer Choice certification intersects with FDA cosmetic claim oversight to reshape permissible marketing language for infant-targeted products. The dual framework forces brands to substantiate hypoallergenic claims through documented testing while restricting implied therapeutic benefits. Pediatric dermatology clinics in the United States now screen product recommendations against both databases.
Specialty store curation is displacing mass retail aisle dominance as parents seek guided selection environments. Independent retailers in urban clusters command premium shelf positioning through staff training on epidermal barrier science. This channel rotation is most visible in Germany and South Korea where pharmacy-adjacent baby boutiques aggregate trust-based purchasing decisions.
Baby Products Detergents Market Segmentation
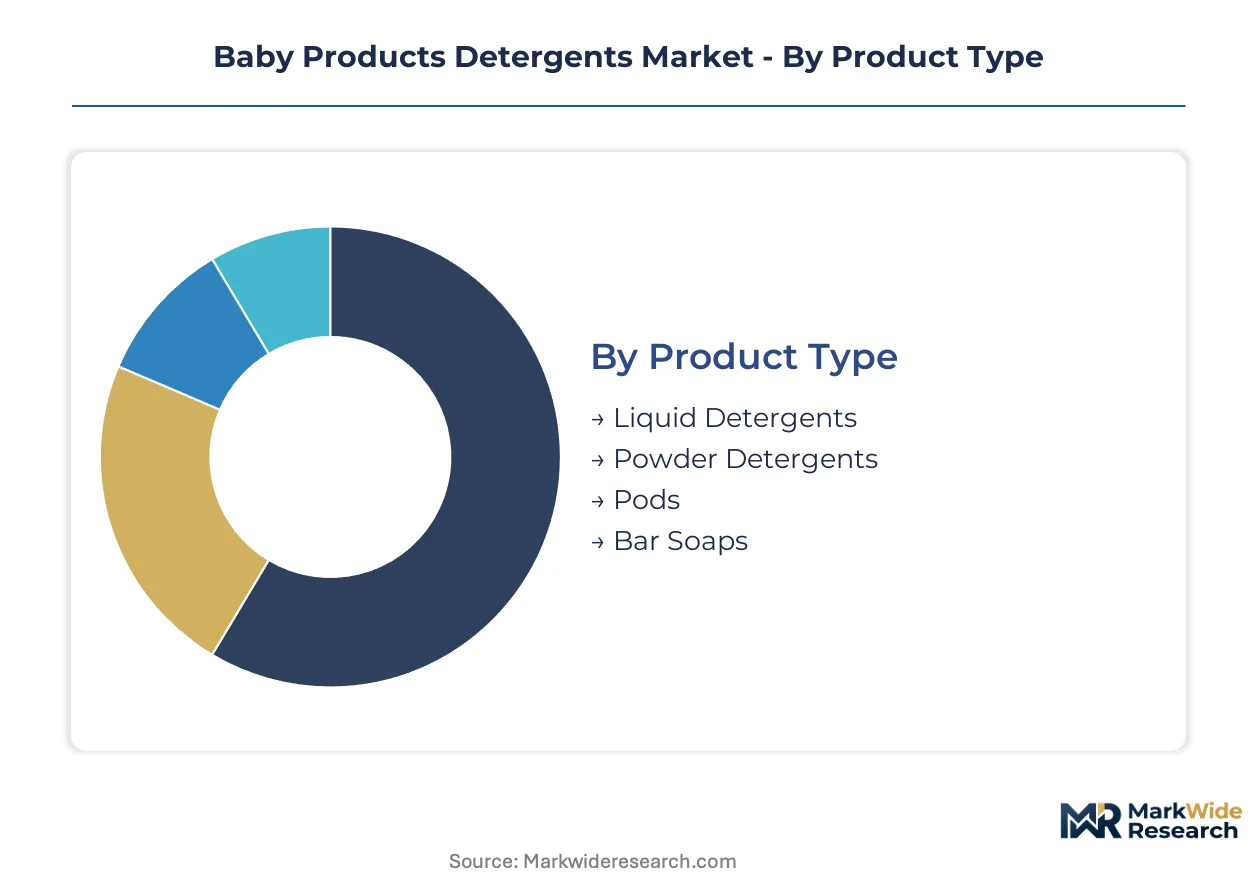
Baby products detergents fragment across four structural dimensions that determine margin capture and shelf positioning. Formulation chemistry and packaging format drive replenishment frequency, while distribution channel selection locks in customer lifetime value through either convenience or trust-based curation.
Product Type:
Liquid detergents turn inventory fastest through weekly wash cycles, while bar soaps linger in household cabinets for months. Pods and powders occupy intermediate velocity tiers tied to washing machine penetration and water hardness.
- Liquid Detergents:Surfactant-based formulations engineered for cold-water dissolution below 30°C, maintaining pH 5.5-7.0 to protect immature epidermal barriers. Demand clusters in Germany and South Korea where energy-efficient appliances dominate, driven by parental preference for residue-free rinsing on delicate infant garments.
- Pods:Concentrated active chemistry in water-soluble film delivering precise single-dose convenience. Expansion concentrates in China and the United States as dual-income households prioritize dosing accuracy and reduced packaging waste over unit cost.
- Powder Detergents:Enzyme-containing granular formulations with extended shelf stability, prevalent in regions with hard water mineral content and lower washing machine penetration.
- Bar Soaps:Solid surfactant blocks for hand-washing applications and travel formats, retaining niche positioning in price-sensitive segments and manual laundering contexts.
Liquid detergents dominate installed base. Pods are where expansion concentrates.
Formulation:
Cost tier stratification separates premium-certified formulations from commodity alternatives, with certification overhead creating margin pools that sustain specialized supply chains.
- Hypoallergenic:Dermatologist-tested formulations excluding enzymes, optical brighteners, and synthetic fragrances, validated through pediatric patch study protocols. Demand concentrates among parents of infants under two years in California and New York where state-level chemical transparency laws mandate expanded ingredient labeling.
- Organic:Plant-derived surfactant systems with EPA Safer Choice certification and transparent supply chain documentation. Premium positioning in Germany and France leverages ECHA REACH compliance as a competitive differentiator against legacy petrochemical formulations.
- Unscented:Fragrance-free variants for documented fragrance sensitivities and eczema-prone infant populations, common in pharmacy-adjacent retail channels.
- Scented:Mild essential oil or synthetic fragrance formulations targeting parental preference for freshness signaling, concentrated in mass retail and emerging market segments.
Hypoallergenic formulations command premium shelf positioning. Organic certification is climbing the fastest as regulatory pressure eliminates conventional alternatives.
Packaging Type:
Volume economics and sustainability credentials reshape procurement patterns, with refill formats gaining share against primary rigid containers.
- Bottles:Rigid HDPE or PET containers with child-resistant closures, dominant in liquid detergent segments across United States mass retail and pharmacy channels.
- Pouches:Flexible laminated films for concentrated refills, expanding in China and South Korea through direct-to-consumer subscription models that reduce per-shipment packaging mass.
- Boxes:Corrugated or paperboard containers for powder detergents and pod assortments, prevalent in European markets with extended producer responsibility regulations.
- Tubes:Collapsible aluminum or laminate structures for travel-size and specialty formats, concentrated in urban boutique retail and sampling programs.
Bottles retain installed base dominance. Pouches are gaining share fastest through e-commerce replenishment channels.
Distribution Channel:
Customer acquisition cost and trust transfer mechanisms differentiate channel economics, with curated environments commanding margin premiums over transactional efficiency.
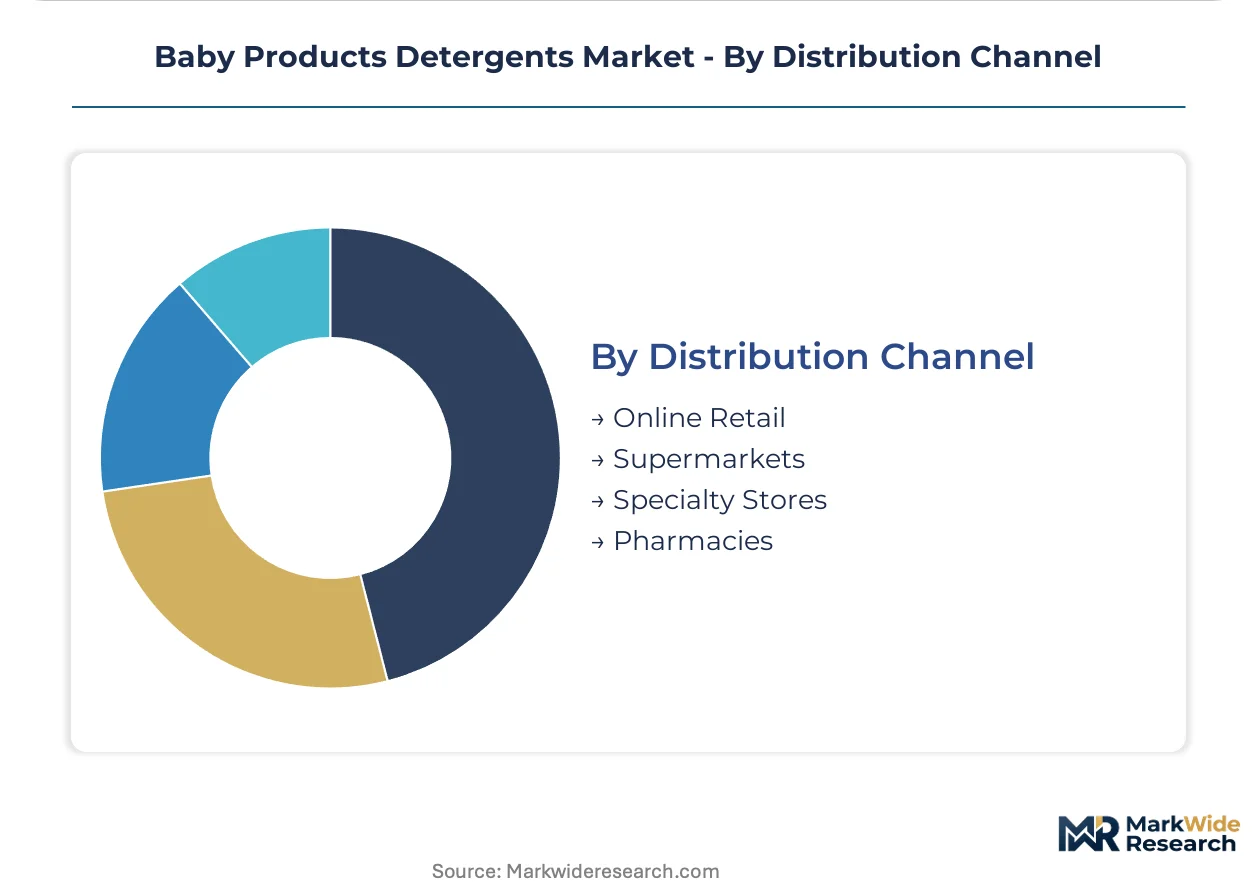
- Specialty Stores:Curated retail environments with trained staff on epidermal barrier science, commanding premium shelf positioning in Germany and South Korea through pharmacy-adjacent baby boutiques that aggregate trust-based purchasing decisions.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription automation and reduced customer acquisition costs, expanding most quickly in China and the United States through automated replenishment cycles.
- Supermarkets:Mass retail aisle dominance with high-velocity turnover and promotional pricing, retaining volume concentration in conventional liquid and powder segments.
- Pharmacies:Healthcare-adjacent retail with pharmacist endorsement leverage, concentrated in France and Germany where dermocosmetic positioning intersects with infant care recommendations.
Supermarkets dominate transaction volume. Online retail is where customer lifetime value expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European distribution for REACH-compliant surfactant imports, while China's Yangtze River Delta manufacturing clusters concentrate global pod production capacity.
United States
Parents of infants under two years in California and New York drive hypoallergenic formulation demand through state-level chemical transparency mandates. EPA Safer Choice certification intersects with FDA cosmetic claim oversight to reshape permissible marketing language. Pediatric dermatology clusters in Boston and Los Angeles now screen product recommendations against both regulatory databases.
China
Dual-income households in Shanghai and Shenzhen prioritize pod configurations for dosing convenience and reduced packaging waste. The Ministry of Ecology and Environment enforces GB standards on surfactant discharge that eliminate legacy petrochemical formulations. Domestic brands expanding premium hypoallergenic lines concentrate manufacturing in the Yangtze River Delta chemical corridor.
Germany
Energy-efficient appliance penetration drives cold-water dissolution requirements for liquid detergents across Bavaria and North Rhine-Westphalia. ECHA REACH restrictions on quaternary ammonium compounds force systemic reformulation of legacy portfolios. Pharmacy-adjacent baby boutiques in Berlin and Munich aggregate trust-based purchasing decisions through staff training on epidermal barrier science.
South Korea
Urban parents in Seoul and Busan favor flexible pouch refills through direct-to-consumer subscription platforms. The Ministry of Food and Drug Safety aligns cosmetic safety assessments with MFDS pediatric product guidelines. Manufacturing concentration in the Seoul Capital Area supports rapid formulation iteration for sensitive-skin certification.
France
Healthcare-adjacent retail channels in Paris and Lyon leverage pharmacist endorsement for dermocosmetic positioning. ANSM cosmetic surveillance intersects with EU ECHA enforcement to eliminate ethoxylated surfactants from infant-targeted products. Premium organic formulations certified through ECOGARANTIE and COSMOS standards command shelf positioning in Île-de-France pharmacy networks.
Baby Products Detergents Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation chemistry. The vendor base stratifies between multinational consumer goods conglomerates with dedicated infant care divisions and mid-scale organic specialists with captive supply chains. Three archetypes dominate: mass-market liquid formulators leveraging manufacturing scale, subscription-native direct-to-consumer brands, and eco-certified organic specialists with transparent ingredient sourcing. Competitive moves concentrate on geographic expansion through localized formulation compliance and portfolio diversification into adjacent baby care categories.
Among North American platform integrators, Procter & Gamble and Kimberly-Clark occupy positions anchored by mass retail channel dominance and manufacturing scale. Seventh Generation represents the eco-certified specialist archetype with EPA Safer Choice positioning. The Honest Company exemplifies subscription-native distribution architecture. Dongguan UFine Daily Chemical sits within China's domestic brand expansion wave. Pigeon Corporation anchors Japanese-origin dermocosmetic positioning across Asian pharmacy channels.
| Leading Market Players |
|---|
| Kimberly-Clark |
| Seventh Generation |
| Procter & Gamble |
| Dongguan UFine Daily Chemical |
| Babyganics |
| Johnson & Johnson Services |
| The Honest Company |
| Pigeon Corporation |
| Unilever |
| Others |
Supply Flow & Price Mechanics
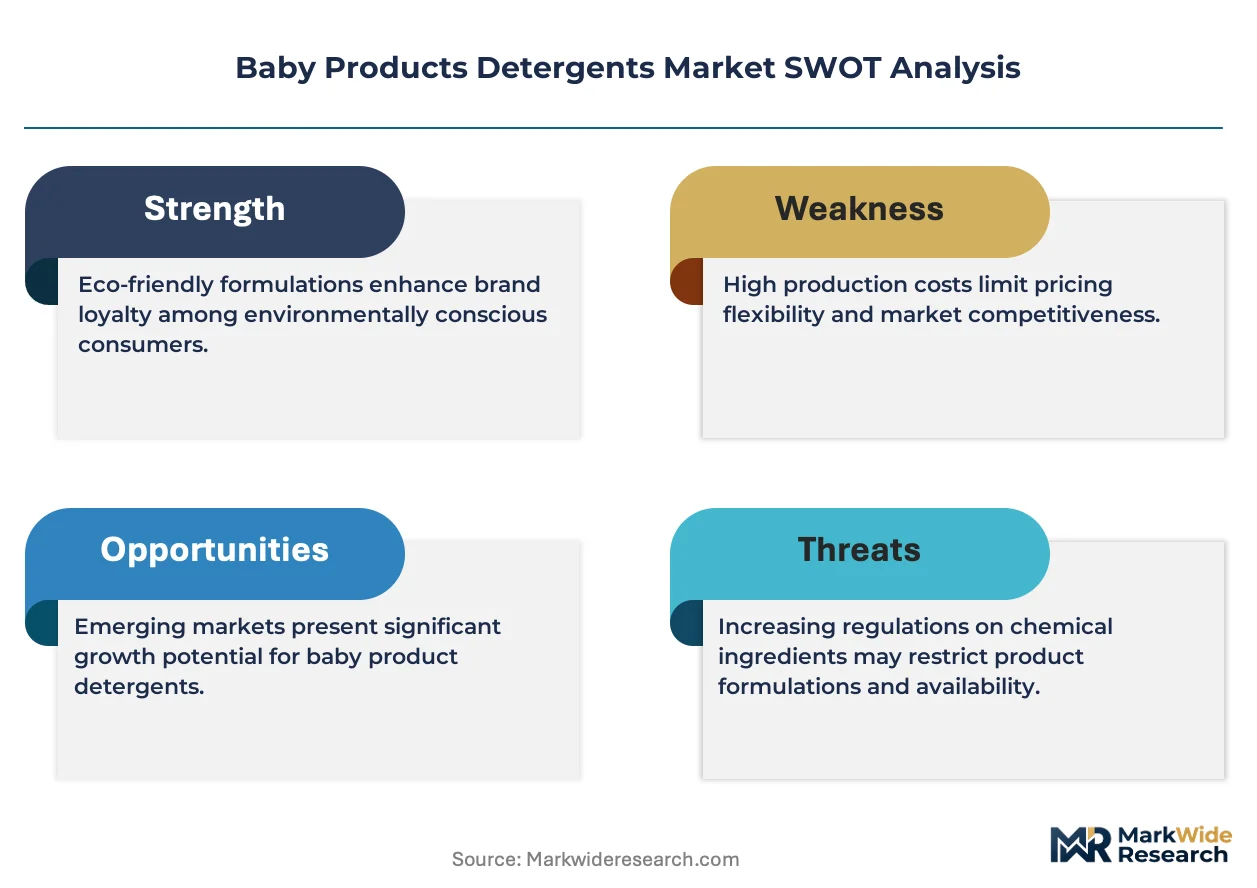
EU REACH regulatory chokepoints on quaternary ammonium compounds and ethoxylated surfactants determine both the premium-to-economy pricing tier spreads and the geographic reconfiguration of compliant chemical sourcing. This regulatory compression forces brands to absorb certification overhead or pass through reformulation costs, reshaping margin capture across hypoallergenic and organic product tiers.
Pricing Analysis
Volume-discount tiering structures separate subscription-native direct-to-consumer platforms from transactional mass retail channels, with automated replenishment cycles capturing 15-20% per-unit premiums over supermarket aisle pricing. Price differentiation hinges on dermatologist-tested certification grade and EPA Safer Choice eco-label status, with organic formulations commanding shelf positioning premiums. Cost compression in the standard liquid tier is intensifying because domestic Chinese brands are expanding premium hypoallergenic lines at intermediate price points. Parents of infants under two years in California and New York show least price sensitivity due to state-level chemical transparency mandates, while emerging market mass retail segments remain most cost-conscious.
Supply Chain Analysis
Supplier-financing facilities extended by Yangtze River Delta chemical manufacturers enable domestic Chinese brands to scale premium hypoallergenic production without immediate capital deployment. Geographic supply concentration centers on China for pod manufacturing and concentrated actives, Germany for REACH-compliant surfactant intermediates, and the United States for EPA Safer Choice-certified packaging. Raw material dependencies include plant-derived alkyl polyglucosides, coconut-based fatty alcohol sulfates, and water-soluble pod films. Single-source vulnerability runs through the narrowing base of EU-compliant quaternary ammonium compound manufacturers. Distribution runs through direct-to-consumer subscription platforms in China and the United States, specialty pharmacy-adjacent boutiques in Germany and South Korea, and mass retail supermarkets retaining volume concentration in conventional liquid segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription platform economics are displacing transactional retail as the dominant value-capture mechanism, with automated replenishment interoperability creating winner-take-most dynamics in customer lifetime value aggregation.
For Market Incumbents: Entrench manufacturing scale advantages through dedicated production lines that prevent cross-contamination with enzyme-containing adult detergents, locking in hypoallergenic certification credibility. Secure backward integration into plant-derived surfactant supply through long-term offtake agreements with agricultural processors, defending against commodity volatility in coconut and corn feedstocks. Channel control through pharmacy-adjacent boutique partnerships in Germany and South Korea preserves premium positioning against direct-to-consumer entrants. For New Entrants and Emerging Players: Build out flexible pouch refill formats for urban South Korean and Chinese households prioritizing reduced packaging waste and subscription automation. White-space concentration sits in pharmacy-adjacent retail channels across France and Germany where dermocosmetic positioning intersects with pharmacist endorsement leverage. A go-to-market angle anchored in transparent supply chain documentation and ECOGARANTIE certification opens shelf positioning previously closed to unbranded organic alternatives. For Investors and Strategic Acquirers: Subscription-native direct-to-consumer brands with automated replenishment infrastructure and negative customer acquisition cost economics present the highest long-term viability profile across a 5-10 year holding window. These assets capture recurring revenue streams with predictable churn profiles and expand into adjacent baby care categories through trust-based cross-selling. The signal to watch is consolidation of state-level chemical transparency compliance infrastructure in California and New York, as brands with pre-existing disclosure databases will command acquisition premiums when federal mandates follow.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Automated replenishment cycles reduce customer acquisition costs and sustain recurring revenue through trust-based retention. |
| EPA Safer Choice Certification Investment | Eco-label status opens premium shelf positioning in mass retail channels previously closed to organic entrants. |
| Backward Integration into Plant-Derived Surfactants | Captive supply of coconut and corn-based feedstocks insulates margin structures from agricultural commodity volatility. |
| Pharmacy-Adjacent Boutique Expansion | Staff training on epidermal barrier science aggregates trust-based purchasing decisions in Germany and South Korea. |
| Cold-Water Optimized Formulation R&D | Dissolution efficiency below 30°C aligns with energy-efficient appliance penetration in Germany and parental preference for residue-free rinsing. |
Methodological Framework
A spread of perspectives from brand managers at multinational consumer goods conglomerates, procurement leads at domestic Chinese detergent manufacturers, category buyers at German pharmacy chains, and pediatric dermatology clinic directors converged on the working assumptions underpinning volume and value estimates. Primary fieldwork combined structured interviews with supply chain planners and regulatory affairs specialists with secondary validation against ECHA REACH substance restriction databases, EPA Safer Choice certified product listings, and customs trade data on surfactant imports through Rotterdam. Bottom-up triangulation across product-level shipment data and top-down reconciliation against national household penetration statistics anchored the analytical framework.
Demand-supply-balance framing modeled consumption patterns across formulation chemistry, packaging format, and distribution channel dimensions throughout the forecast period. Segmentation analysis incorporated product type stratification, hypoallergenic versus organic certification tiers, and regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of parental purchasing behavior shifts and enforcement trajectories of chemical transparency mandates. Industry-specific forecast inputs included washing machine cold-water cycle penetration rates and dual-income household concentration in urban China.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic Chinese brands expanding premium hypoallergenic lines or subscription-native platforms achieving rapid customer lifetime value expansion would shift outcomes beyond modeled ranges. Macroeconomic deviation in agricultural commodity markets, regulatory acceleration of surfactant restrictions beyond EU REACH baselines, or technological breakthroughs in enzyme-free stain removal chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Global Baby Mattresses Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Baby Wipes Market
Baby Products
Baby Gift Basket Market
Baby Products
Baby Slings Market
Baby Products
Baby Nipple/Teat Market
Baby Products
Automatic Baby Swing Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Diaper Bag Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Wet Wipes Market