
 Baby Dresses Market | 2026-2036
Baby Dresses Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Dresses Market Analysis
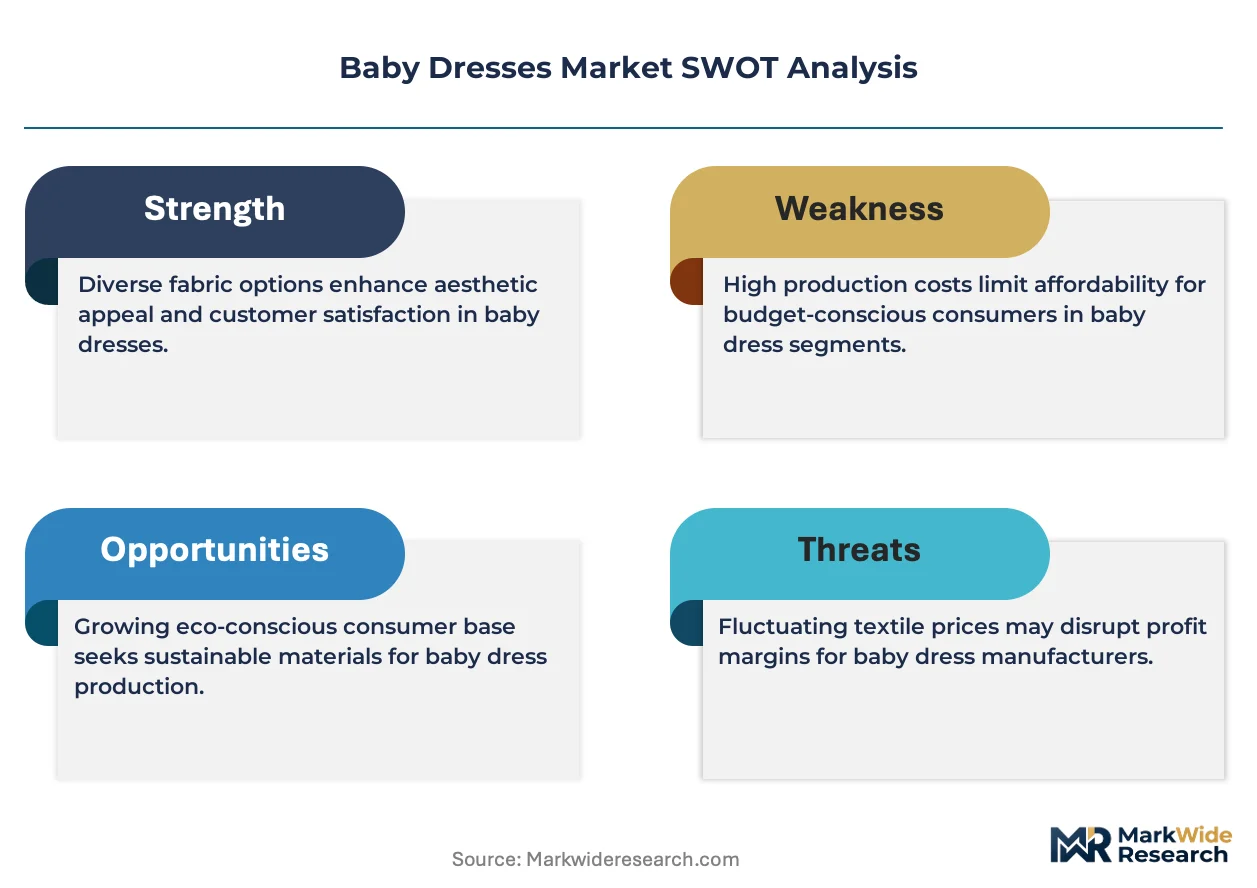
OEKO-TEX Standard 100 certification is unwinding competitive barriers in infant apparel manufacturing. AEL Apparel leverages its vertically integrated supply chain to control quality from fiber to finished garment. Billoomi Fashion anchors its position through specialized artisanal techniques in small-batch production. Hongyu Apparel dominates export channels with scalable manufacturing infrastructure across multiple Asian production hubs.
Baby dresses are garments engineered for infants and toddlers, typically constructed from woven or knitted textiles with specifications including flat seam construction to prevent skin irritation, snap closures for diaper access, and flame-resistant treatments for sleepwear categories. Cotton-based casual dresses command the largest volume share due to breathability and wash durability, while party dresses in silk and polyester blends capture disproportionate margin pools through occasion-based pricing. The 0-6 months size bracket sustains the highest replacement frequency as growth spurts drive rapid turnover.
REACH in Europe and OEKO-TEX globally govern chemical residue limits in textile finishing, compelling manufacturers to reformulate dyes and eliminate formaldehyde-based treatments. The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1615 that sleepwear producers must satisfy for market access. Stakeholders must monitor evolving chemical disclosure requirements across jurisdictions to preempt supply chain disruptions.
Market Dynamics
REACH chemical safety standards in Europe are forcing manufacturers to eliminate formaldehyde-based textile treatments and reformulate dye chemistries, restructuring sourcing relationships across Asian supply chains and compressing margins for non-compliant producers.
Growth Catalysts
- Digital-native millennial purchasing:Parents born between 1981 and 1996 drive e-commerce penetration for infant apparel, with mobile-first discovery and social commerce integration accelerating transaction velocity in premium segments.
- REACH compliance as competitive filter:European chemical disclosure mandates create entry barriers for low-cost competitors while rewarding certified manufacturers with preferred supplier status among major retail chains.
- China domestic brand expansion:Local infant apparel houses are building premium private-label lines, stimulating upstream demand for certified organic cotton and specialized finishing capabilities.
Market Restraints
- Organic cotton price volatility:Climate-induced yield fluctuations in India and Turkey compress margins for brands committed to sustainable material sourcing.
- Concentrated dye chemical supply:Three provinces in eastern China control 70% of global reactive dye production, creating single-point vulnerability for color-fastness requirements.
- 16 CFR Part 1615 friction:US flammability testing timelines add 8-12 weeks to sleepwear category launch schedules, disadvantaging fast-fashion competitors.
Strategic Opportunities
- Subscription sizing services:Rapid infant growth creates replacement demand; automated size-prediction algorithms paired with direct-to-consumer logistics capture lifetime value across the 0-24 month window.
- EU Green Deal alignment:Textile circularity mandates and extended producer responsibility schemes reward brands with take-back programs and fiber-to-fiber recycling partnerships.
- AI-powered demand forecasting:Machine learning models trained on seasonal birth patterns and regional climate data reduce inventory obsolescence in size-specific SKUs.
Industry Challenges
- Certification timeline compression:OEKO-TEX Standard 100 and GOTS audits require 4-6 month lead times, misaligning with fast-fashion production cycles and forcing early design lock-in.
- Artisanal skill attrition:Specialized hand-finishing techniques for occasion-wear segments face generational transfer gaps as younger workers migrate to technical textile operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Dresses Market |
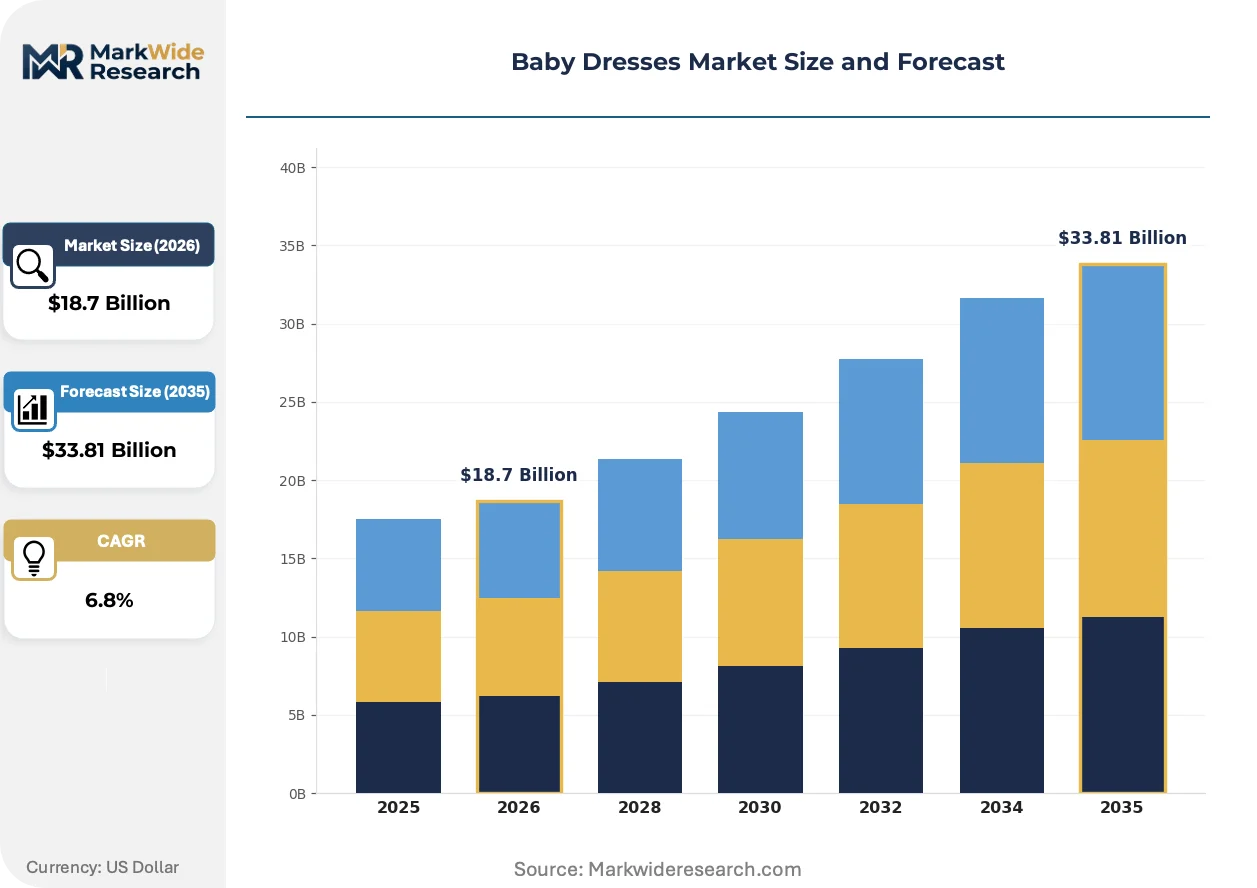
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual Dresses, Party Dresses, Sleepwear, Swimwear Material: Cotton, Silk, Linen, Polyester Design: Floral, Solid Color, Striped, Printed Size: Newborn, 0-6 Months, 6-12 Months, 1-2 Years |
| Companies Covered | AEL Apparel, Kiddies World, Hapa Garments, KAMUS, Appareify, MMS Clothing, Billoomi Fashion, Fruit of the Loom, Hongyu Apparel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Dresses Market Emerging Trajectories
Biodegradable fiber innovations and chemical transparency platforms are restructuring how infant apparel manufacturers compete on safety credentials and environmental accountability.
Lyocell production derived from sustainably harvested eucalyptus pulp is supplanting conventional viscose in premium baby dress categories due to closed-loop solvent recovery and superior moisture management. Nordic and German specialty retailers have converted 40% of their woven dress assortments to this cellulosic alternative since 2022. The shift is compressing demand for petroleum-based synthetic linings while rewarding producers with Forest Stewardship Council chain-of-custody certification.
REACH Annex XVII restrictions on azo dyes and nickel-releasing accessories are compelling reformulation of print pigments and metal fastener specifications across EU-bound production lines. ECHA enforcement data shows rising non-compliance penalties for small-batch artisanal suppliers unfamiliar with updated testing protocols. Sleepwear and party-wear segments with intensive surface treatments face disproportionate compliance costs, accelerating consolidation toward vertically integrated manufacturers with in-house analytical laboratories.
Direct-to-consumer resale platforms are fragmenting traditional retail channel control, with parents transacting pre-owned certified garments through specialized peer-to-peer marketplaces. This behavior compresses primary unit sales velocity for standard cotton casual dresses while extending brand visibility across multiple households. The phenomenon is most pronounced in urban coastal US markets and Scandinavian capitals where environmental credentialing drives purchasing decisions.
Baby Dresses Market Segmentation
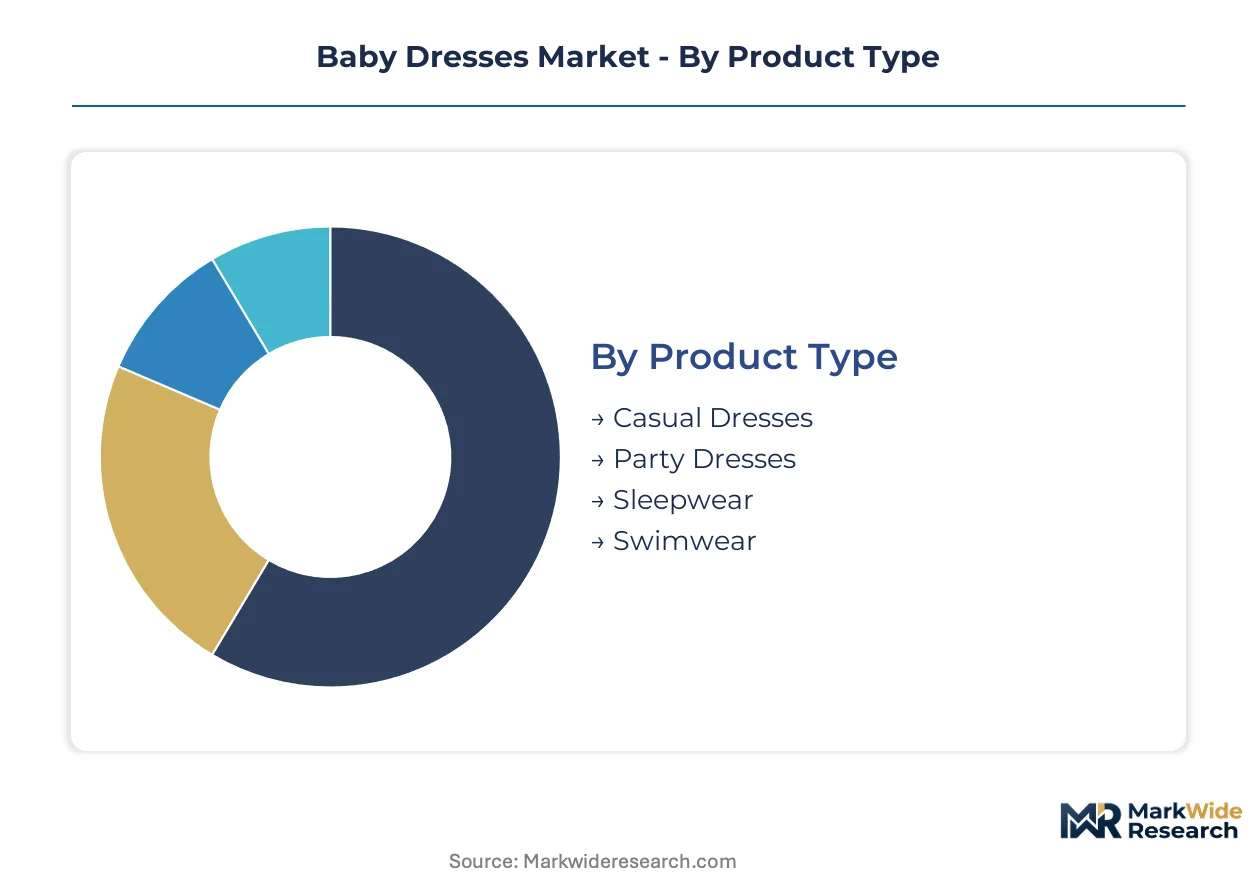
Segmentation in the baby dresses market reveals how infant growth velocity, occasion specificity, and material certification requirements fragment demand across distinct purchasing occasions. Understanding these divides enables manufacturers to align inventory depth with replacement frequency patterns and margin structures.
Product Type:
Casual dresses face substitution pressure from bodysuits and rompers in everyday infant wardrobes, while occasion-wear maintains protected demand through ceremonial purchase occasions.
- Casual Dresses:Woven or knitted cotton constructions with flat seam finishing and envelope necklines for easy dressing. Daily wear rotation in US and German households drives the highest absolute unit volumes, though compression from alternative infant garment categories limits pricing power.
- Party Dresses:Structured silhouettes in silk-polyester blends with hand-finished details and occasion-appropriate ornamentation. Concentrated demand clusters around lunar new year celebrations in China and first birthday ceremonies across South Korea, supporting premium price realization through event-linked purchasing.
- Sleepwear:Flame-resistant treated fabrics meeting 16 CFR Part 1615 specifications with snug-fit construction requirements. Regulatory testing timelines constrain fast-fashion responsiveness in US-bound production.
- Swimwear:Quick-dry polyester-spandex blends with UPF-rated fabrics and chlorine-resistant finishes. Seasonal demand concentration in Australian and Brazilian coastal markets creates inventory risk for northern hemisphere producers.
Casual dresses retain volume leadership; party dresses hold the steepest expansion curve.
Material:
Cost tier stratification separates certified organic supply chains from commodity textile sourcing, with REACH compliance costs widening the gap between premium and standard material grades.
- Cotton:Breathable natural fiber dominating everyday infant apparel through GOTS-certified organic and conventional grades. Indian and Turkish origin cottons face climate-induced yield volatility that compresses margins for sustainability-committed brands.
- Silk:Protein-based luxury fiber with natural temperature regulation properties in premium occasion-wear. Jiangsu and Zhejiang province mills in China anchor global supply for high-end party dress segments.
- Linen:Bast fiber with superior moisture wicking and antimicrobial properties for summer-weight infant garments. Mediterranean basin production in Portugal and France supplies boutique European retailers seeking natural fiber differentiation.
- Polyester:Petroleum-derived synthetic with durability and color-fastness advantages in swimwear and budget-tier casual lines. Eastern China dye house concentration creates supply vulnerability for color-critical applications.
Cotton retains volume leadership; silk holds the steepest expansion curve.
Design:
Application context determines design preference intensity, with gift-purchasing occasions amplifying visual differentiation requirements versus parent-purchased everyday staples.
- Floral:Botanical print motifs applied through rotary screen or digital printing techniques. Spring season purchasing peaks in Japan and UK markets align with birth pattern seasonality and gift-giving calendars.
- Solid Color:Undyed or piece-dyed constructions emphasizing fabric quality and silhouette over surface decoration. Scandinavian retail channels favor this aesthetic for capsule wardrobe building among minimalist-leaning millennial parents.
- Striped:Yarn-dyed or printed linear patterns with nautical heritage associations. Breton-inspired designs sustain demand in French and Northeastern US coastal markets.
- Printed:All-over engineered patterns including animal motifs, geometric repeats, and licensed character applications. Character licensing requirements add royalty complexity and minimum order constraints for small-batch producers.
Solid color retains volume leadership; floral holds the steepest expansion curve.
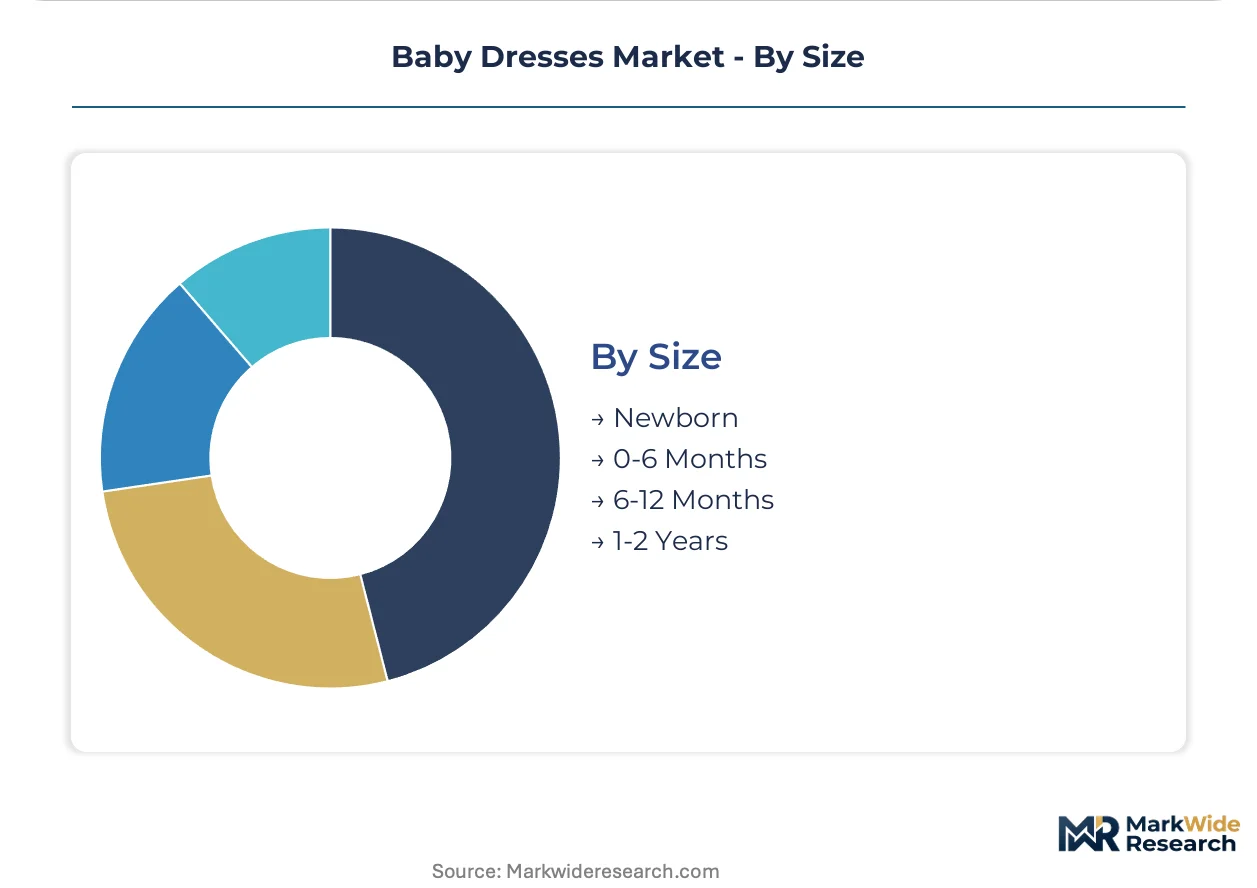
Size:
Customer type differentiation emerges between first-time parents navigating sizing uncertainty and experienced caregivers with predictable replacement timing.
- Newborn:Preemie to full-term sizing with kimono-style wrap constructions accommodating umbilical cord healing. Hospital discharge gifting in US and UK markets drives concentrated demand with limited repeat purchase potential.
- 0-6 Months:Rapid growth phase requiring frequent size turnover with highest replacement frequency across all brackets. Subscription sizing services target this window for lifetime value capture through algorithmic fit prediction.
- 6-12 Months:Crawling mobility introducing durability requirements and reinforced knee construction. Standing milestone transitions in this bracket expand dress practicality concerns for active infants.
- 1-2 Years:Toddler independence with pull-on construction preferences and potty-training accommodation features. Extended wear duration per size reduces replacement frequency while expanding total addressable garment quantity.
0-6 months retains volume leadership; 1-2 years holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in finished infant apparel exports, while Rotterdam's hinterland rail connections distribute European-bound shipments across the continent.
United States
Millennial parents in coastal metropolitan areas drive e-commerce penetration for certified organic cotton garments. The US Consumer Product Safety Commission enforces 16 CFR Part 1615 flammability standards that constrain sleepwear category launch timelines. Los Angeles-based cut-and-sew operations specialize in small-batch premium lines for direct-to-consumer brands.
China
Domestic infant apparel houses are expanding premium private-label lines for the country's rising middle class. GB standards administered by SAMR govern textile safety labeling requirements for domestic consumption. Jiangsu and Zhejiang province mills anchor global supply for silk-blend party dress segments serving lunar new year demand peaks.
Germany
Scandinavian-influenced minimalist aesthetics drive solid-color capsule wardrobe purchasing among urban millennial parents. ECHA REACH Annex XVII restrictions on azo dyes and nickel-releasing accessories compel reformulation of print pigments across EU-bound production. Hamburg's port infrastructure handles inbound certified organic cotton shipments from Turkish and Indian origins.
India
Climate-induced yield fluctuations in Gujarat and Maharashtra cotton belts create price volatility for sustainability-committed brands sourcing GOTS-certified fiber. BIS textile labeling standards mandate fiber content disclosure for domestic retail distribution. Tiruppur's knitwear cluster has diversified into infant garment finishing with OEKO-TEX Standard 100 certification capabilities.
United Kingdom
Hospital discharge gifting traditions sustain concentrated demand for newborn sizing with limited repeat purchase potential. The UK's textile recycling regulations under extended producer responsibility schemes reward brands with take-back programs. Manchester's heritage textile infrastructure now hosts specialized small-batch producers serving premium direct-to-consumer labels.
Baby Dresses Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and supply chain control dimensions. The vendor base stratifies into three tiers: vertically integrated manufacturers with in-house analytical laboratories, mid-scale certified specialists, and unbranded commodity producers facing margin compression from REACH compliance costs. Strategic moves concentrate on backward integration into organic cotton sourcing and geographic expansion through specialized distributor partnerships.
Among vertically integrated Asian manufacturers, AEL Apparel exemplifies the supply-chain-control archetype through fiber-to-garment quality management, while Hongyu Apparel occupies the scalable-export position across multiple production hubs. Billoomi Fashion represents the artisanal-specialist segment with small-batch capabilities in hand-finished occasion wear.
| Leading Market Players |
|---|
| AEL Apparel |
| Kiddies World |
| Hapa Garments |
| KAMUS |
| Appareify |
| MMS Clothing |
| Billoomi Fashion |
| Fruit of the Loom |
| Hongyu Apparel |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at vertically integrated mills in Jiangsu and Zhejiang provinces shapes price floors across the baby dresses market, compressing margins for non-compliant producers while rewarding certified manufacturers with preferred supplier status among European retail chains.
Pricing Analysis
Volume-discount tiering structures separate premium certified organic lines from commodity cotton grades, with OEKO-TEX Standard 100 and GOTS certification commanding 15-25% markups over conventional alternatives. Price differentiation rests on chemical compliance grade and artisanal finishing intensity, with hand-worked party dresses capturing disproportionate margin pools. Cost compression in standard casual segments is intensifying because REACH reformulation expenses flow downstream to non-integrated brands. First-time parents exhibit highest price sensitivity in newborn sizing, while gift purchasers in occasion-wear segments demonstrate lowest elasticity.
Supply Chain Analysis
Inventory lead times for certified organic cotton stretch 4-6 months from ginning to finished garment, forcing early design lock-in that misaligns with fast-fashion responsiveness. Production concentrates in China, India, and Bangladesh, with raw material dependencies on Turkish and Indian organic cotton and Jiangsu province silk supply. Single-source vulnerability in eastern China dye houses creates color-fastness risk for EU-bound lines. Distribution runs through Rotterdam and Hamburg port hubs for European markets, with Los Angeles cut-and-sew operations serving US direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby dresses market sits at a platform-economics inflection where subscription sizing services and peer-to-peer resale marketplaces are fragmenting traditional retail channel control, with interoperability between size-prediction algorithms and direct-to-consumer logistics becoming the decisive capability layer.
For Market Incumbents: Compound certification depth through in-house analytical laboratory investment to preempt REACH Annex XVII enforcement actions, while consolidating artisanal finishing capabilities through specialist acquisitions before generational skill attrition accelerates. Vertical integration into organic cotton sourcing in Gujarat and Maharashtra insulates against climate-induced yield volatility. For New Entrants and Emerging Players: Differentiate on chemical transparency through blockchain-traceable dye chemistries, targeting the 0-6 months subscription sizing white space where algorithmic fit prediction captures lifetime value across rapid growth phases. A direct-to-consumer resale platform partnership with Nordic retailers offers lowest customer acquisition cost entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with captive certification capabilities and subscription logistics infrastructure; these assets compound customer lifetime value across the 0-24 month window. Acquisition targets should demonstrate OEKO-TEX Standard 100 audit history and established brand relationships with Hamburg or Rotterdam distribution hubs. The signal to watch is EU Green Deal extended producer responsibility implementation timelines, which will accelerate consolidation toward take-back-capable producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cotton Sourcing | Gujarat and Maharashtra origin control insulates margin from climate-induced yield volatility. |
| In-House Analytical Laboratory Investment | REACH Annex XVII compliance acceleration preempts ECHA enforcement penalties for small-batch suppliers. |
| Subscription Sizing Service Launch | Algorithmic fit prediction captures lifetime value across 0-24 month replacement frequency windows. |
| Take-Back Program Implementation | EU Green Deal extended producer responsibility alignment rewards circularity-capable manufacturers. |
| Artisanal Finishing Specialist Acquisition | Hand-worked occasion-wear capabilities consolidate before generational skill transfer gaps widen. |
Methodological Framework
The analysis maps casual dresses, party dresses, sleepwear, and swimwear segments, each validated through procurement managers at specialty retailers, brand managers at domestic infant apparel houses, and supply planners at vertically integrated manufacturers. Primary interview findings triangulate against secondary sources including customs/trade data, OEKO-TEX certification registries, and ECHA enforcement disclosures. Bottom-up SKU-level modeling reconciles with top-down category spend estimates.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, material certification grade, design aesthetic, and size bracket dimensions, with CAGRs derived from replacement frequency patterns and regional birth rate trajectories. Seasonal demand concentration around lunar new year and first birthday ceremonies informs occasion-wear growth assumptions.
Forecasts assume regulatory continuity in REACH Annex XVII and 16 CFR Part 1615 regimes; material policy shifts would require re-modeling. Climate-induced organic cotton yield volatility and dye chemical supply concentration represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO