
 Baby Diaper Rash Cream Market | 2026-2036
Baby Diaper Rash Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Diaper Rash Cream Market Intelligence
Millennial and Gen-Z parents are redrawing demand patterns in the Baby Diaper Rash Cream Market, shifting preference toward clean-label and plant-based formulations over conventional petroleum-based products. Procter & Gamble leverages its mass-market distribution infrastructure to sustain shelf dominance across pharmacy chains and supermarkets. Johnson & Johnson anchors its position through pediatrician-endorsed heritage brands with extensive hospital formulary access. Beiersdorf AG differentiates via dermatological credibility transferred from its adult skincare research pipeline.
Baby diaper rash cream comprises topical emollient and barrier formulations, typically incorporating zinc oxide, petrolatum, or botanical extracts in occlusive bases designed to protect infant perineal skin from moisture-induced irritant contact dermatitis. Non-medicated creams lead volume sales among routine prevention users while medicated variants containing antifungal or mild corticosteroid adjuncts capture higher margin pools in clinical referral channels. Pharmacy chains dominate distribution in developed markets whereas online retailers represent the fastest-growing channel as subscription-based replenishment models gain traction among digitally native parents.
FDA oversees active ingredient concentrations and labeling claims for over-the-counter diaper rash products in the United States, while EMA's pediatric investigation plans influence formulation development timelines for European market entry. BIS certification requirements in India and NMPA registration pathways in China create divergent compliance burdens that favor multinational players with dedicated regulatory affairs capacity. Stakeholders must monitor evolving preservative restrictions under REACH and state-level clean beauty legislation to anticipate reformulation costs and channel eligibility shifts.
Market Dynamics
Clean-label formulation mandates are forcing zinc oxide and petrolatum suppliers to requalify purity grades under tightening FDA and EMA impurity thresholds, compressing legacy supply chains while opening botanical-alternative pathways.
Growth Catalysts
- Pediatric dermatology clinic expansion:Hospital formulary access protocols in the United States, Germany, and Japan now require barrier-cream stocking for neonatal discharge kits, institutionalizing routine preventive use.
- REACH preservative restrictions:The European Chemicals Agency's tightening allowable limits on parabens and formaldehyde-releasing agents is accelerating reformulation toward phenoxyethanol-free and microbiome-friendly alternatives.
- Subscription replenishment models:Direct-to-consumer platforms are capturing digitally native parents through auto-replenish algorithms tied to diaper consumption data, locking in recurring revenue streams.
Market Restraints
- API-grade zinc oxide concentration:Pharmaceutical-grade zinc oxide supply concentrates among three German and Chinese chemical manufacturers, creating input bottlenecks when purity audits fail.
- Petrolatum sourcing volatility:Refinery output fluctuations in the US Gulf Coast and Rotterdam clusters transmit directly to base-material cost instability for occlusive formulations.
- Preservative-free stability ceilings:Water-in-oil emulsions without synthetic preservatives face 12-18 month shelf-life limits that constrain distribution radius and inventory turns.
Strategic Opportunities
- India tier-2 city pharmacy penetration:BIS certification harmonization with CDSCO cosmetic registration is lowering multinational entry barriers into underpenetrated markets like Lucknow, Indore, and Kochi.
- Prebiotic microbiome positioning:Inulin and fructooligosaccharide adjuncts are opening clinical-channel differentiation at dermatology practices seeking evidence-based barrier repair claims.
- Cross-border e-commerce duty thresholds:China's NMPA cross-border e-commerce pilot zones allow duty-deferred entry for small-parcel natural formulations, bypassing 24-month registration timelines.
Industry Challenges
- Cosmetic-cosmeceutical claim boundary enforcement:FDA warning letters targeting "treats eczema" language on diaper rash packaging require legal review cycles that delay campaign launches by 4-6 months.
- Multi-jurisdiction preservative compliance:Simultaneous satisfaction of Japan's METI quasi-drug standards, EU REACH Annex VI, and US FDA 21 CFR 700.27 creates formulation conflict zones requiring parallel SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Diaper Rash Cream Market |
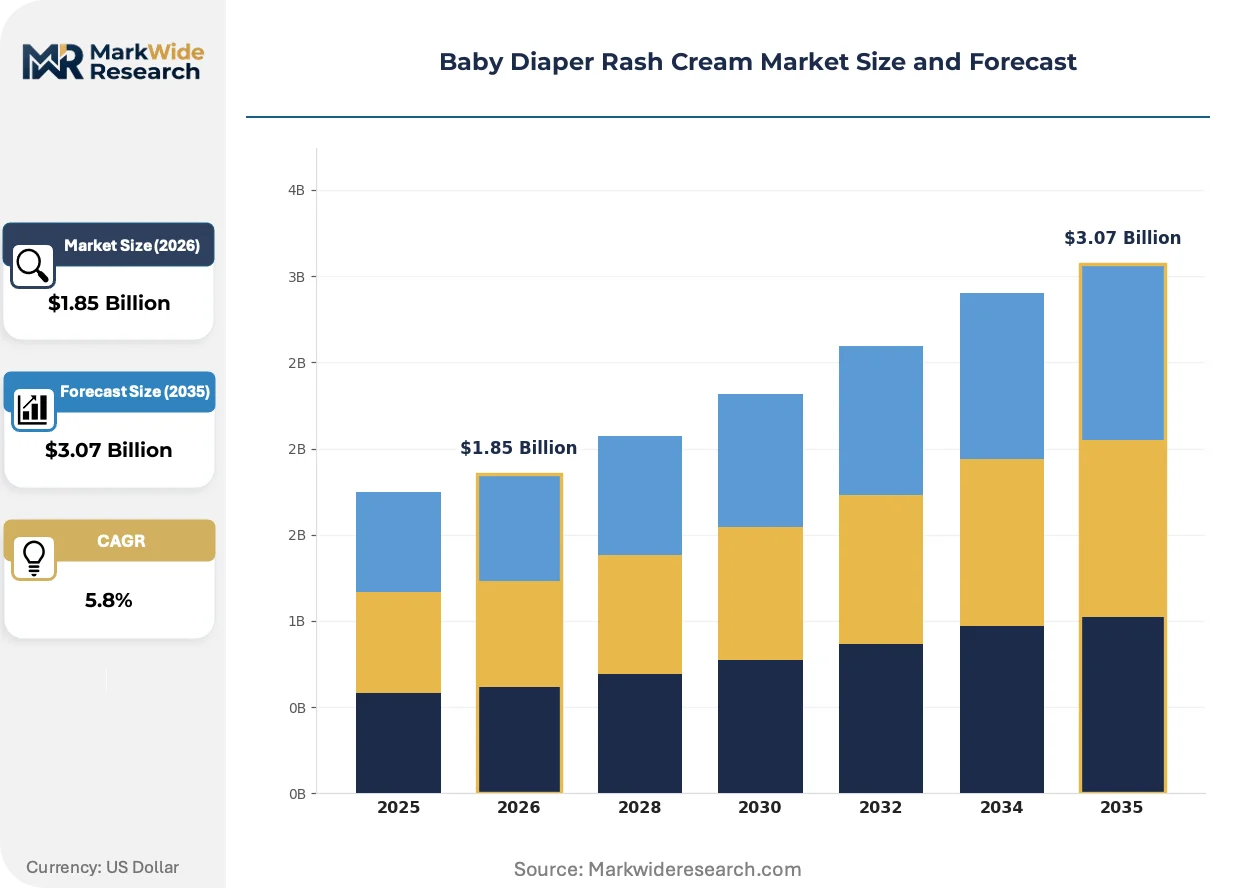
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-medicated Creams, Medicated Creams, Ointments, Powders Brand: National Brands, Store Brands, Organic Brands, Specialty Brands Distribution Channel: Online Retailers, Pharmacy Chains, Supermarkets, Specialty Stores End User: Parents, Caregivers, Hospitals, Maternity Clinics |
| Companies Covered | Himalaya Drug Company, Procter & Gamble, Johnson & Johnson, Sudocrem, Sebapharma, Beiersdorf AG, Weleda, Burt’s Bees, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Diaper Rash Cream Market Strategic Shifts & Innovations
Biomimetic lipid technology is displacing conventional petrolatum barriers, while regulatory divergence between jurisdictions is fragmenting formulation platforms and procurement behaviors are compressing traditional wholesale channels.
Colloidal oatmeal and ceramide NP complexes are decomposing the zinc oxide monopoly in premium prevention segments. Millennial parents in urban US and German markets are adopting these alternatives at 3-4x the rate of petroleum-based predecessors. The technology is decomposing margin structures by enabling 40-60% price premiums over conventional barriers while requiring substantiation investments that exclude mid-tier competitors.
EMA's pediatric investigation plan requirements for any claim referencing "atopic-prone skin" are extending European development timelines by 18-24 months. Formulators must now generate stratum corneum hydration data on infant cohorts before market authorization. The policy most affects botanical-positioned entrants seeking dermatological credibility, forcing partnerships with academic medical centers in France and the Netherlands for compliant study execution.
Hospital discharge kit procurement has consolidated under group purchasing organizations in the United States, collapsing 40+ independent formulary decisions into three dominant GPO contracts. Community birth centers and independent midwife practices in the Pacific Northwest and New England are the residual demand pockets outside this concentration, sourcing direct from B-corps and natural-specialty brands via practitioner-specific portals.
Baby Diaper Rash Cream Market Segmentation
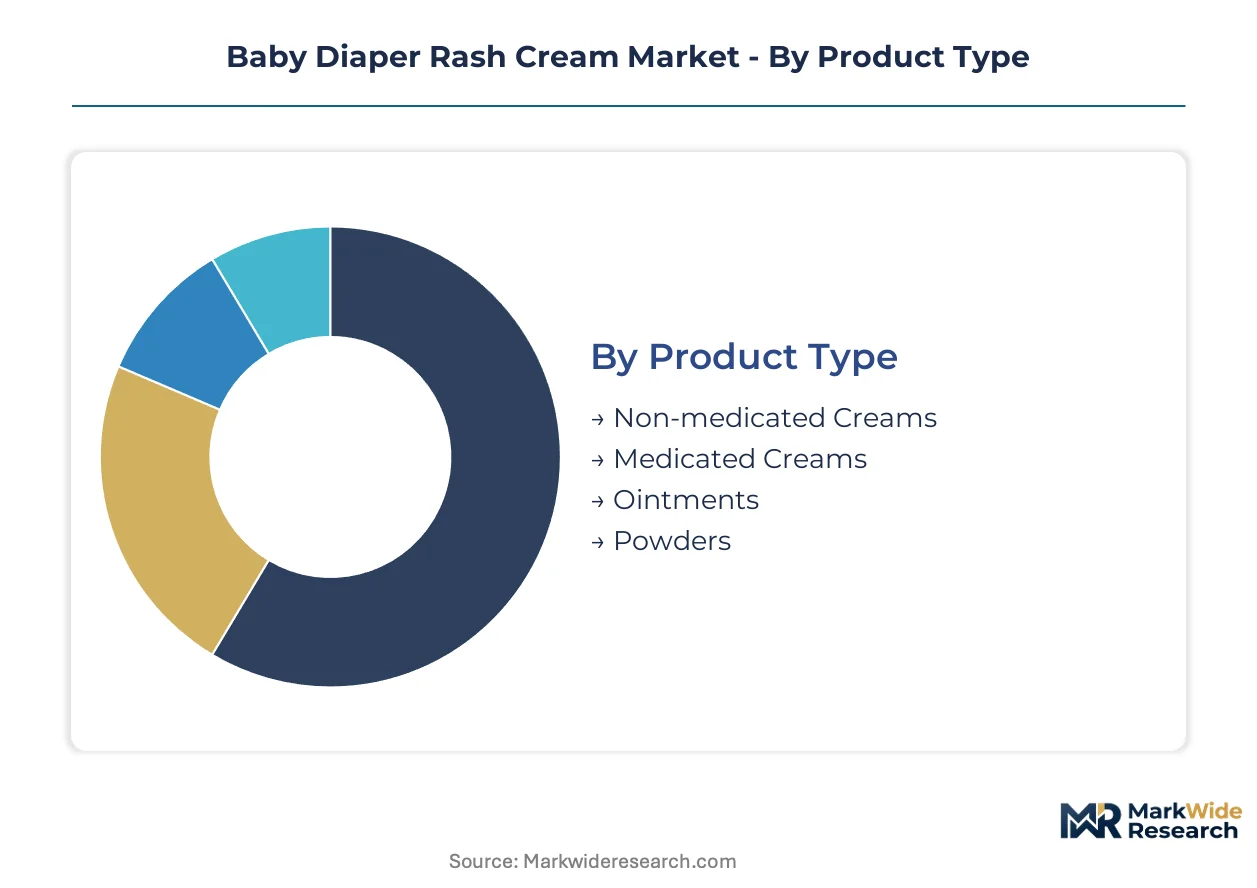
Segmentation in the Baby Diaper Rash Cream Market reveals divergent margin structures across formulation types and channel access tiers. Parents in the United States, Germany, and Japan exhibit sharply differentiated willingness-to-pay based on ingredient sourcing transparency and pediatric endorsement levels.
Product Type:
Margin pools concentrate in medicated variants with clinical-channel positioning, while volume leadership sits with routine prevention formulations.
- Non-medicated Creams:Zinc oxide or petrolatum-based barriers without active pharmaceutical ingredients dominate household replenishment cycles. Parents in the United States favor these for daily prophylaxis, with pharmacy chains capturing the bulk of volume through co-location with diaper purchases.
- Medicated Creams:Formulations incorporating antifungal agents or mild corticosteroids command premium pricing through dermatologist referral channels. Hospital discharge kit procurement in Germany and Japan institutionalizes these for moderate-to-severe cases, creating recurring formulary revenue.
- Ointments:Petrolatum-dominant occlusive bases with higher viscosity for overnight protection.
- Powders:Talc-free alternatives using corn starch or kaolin for moisture absorption in humid climates.
The dominant share belongs to Non-medicated Creams, while Medicated Creams is closing the gap fastest.
Brand:
Price stratification separates heritage pharmaceutical credibility from emerging clean-label challengers.
- National Brands:Mass-market heritage labels with decades of pediatrician endorsement and hospital formulary access. Shelf positioning in United States pharmacy chains and German Drogeriemarkt networks sustains volume leadership despite ingredient scrutiny from Millennial parents.
- Organic Brands:Plant-based formulations certified to USDA Organic or EU Organic standards capture urban premium segments. Parents in Pacific Northwest and New England metro areas adopt these at steep premiums, with direct-to-consumer subscriptions bypassing traditional wholesale markups.
- Store Brands:Private-label offerings from CVS, Walgreens, dm-drogerie markt, and Aeon retail networks.
- Specialty Brands:Dermatologist-developed lines sold through practitioner portals and medical spas.
National Brands retain volume leadership, though Organic Brands are expanding most quickly in premium urban corridors.
Distribution Channel:
Channel selection determines both customer acquisition cost and repeat-purchase velocity for formulation portfolios.
- Pharmacy Chains:CVS, Walgreens, Boots, and dm-drogerie markt dominate developed-market volume through pharmacist recommendation authority. Parents in Germany and Japan trust pharmacy staff for ingredient guidance, creating higher conversion rates for premium-positioned lines.
- Online Retailers:Amazon, iHerb, and brand-direct sites capture digitally native parents through subscription algorithms tied to diaper consumption data. Auto-replenishment models in the United States lock in 6-12 month purchase commitments, compressing customer acquisition costs.
- Supermarkets:Mass-market placement in Walmart, Target, and Aeon hypermarkets for impulse and basket-fill purchases.
- Specialty Stores:Buy Buy Baby, natural parenting boutiques, and hospital gift shops for occasion-based gifting.
Pharmacy Chains command the largest transaction volume, while Online Retailers are climbing the fastest on subscription attach rates.
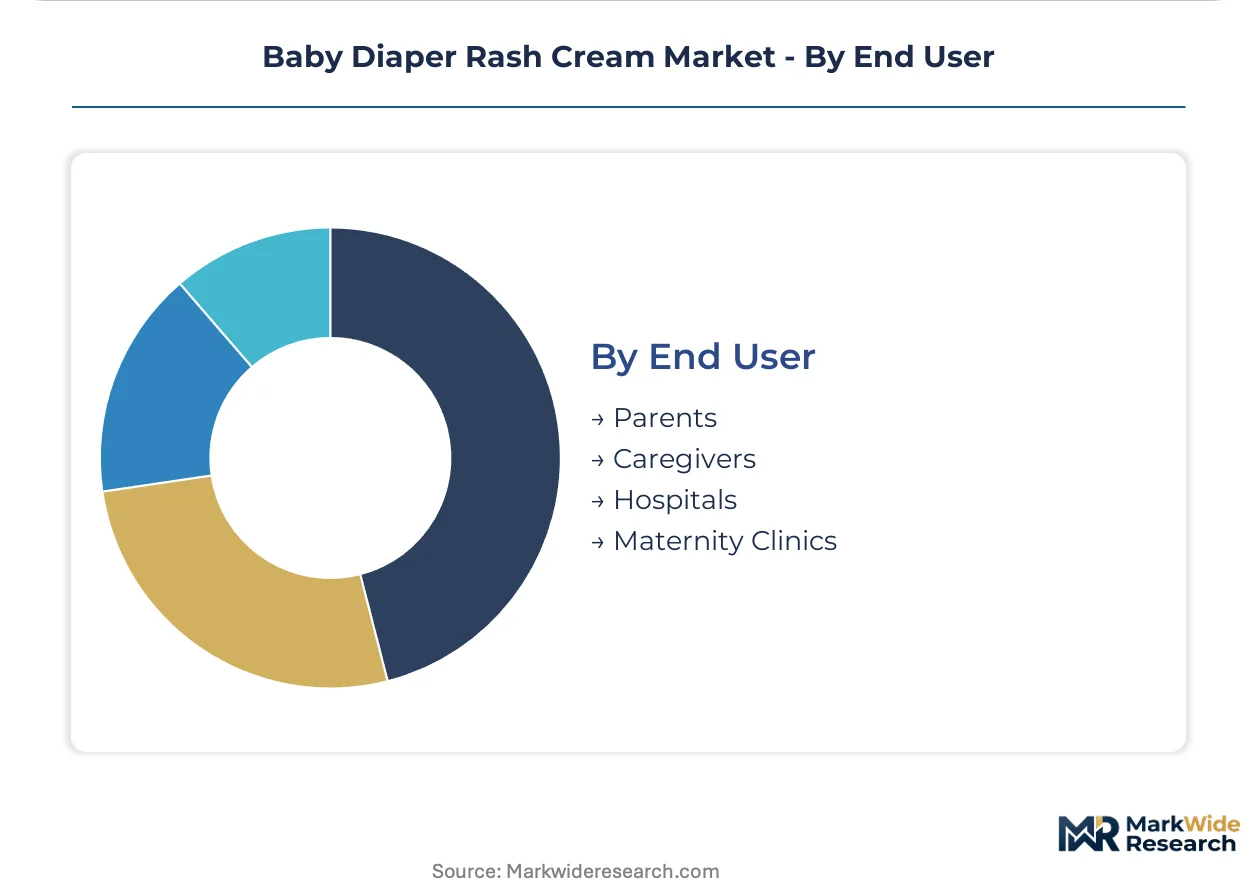
End User:
Procurement authority fragments across institutional purchasers with formulary protocols and individual decision-makers seeking peer validation.
- Parents:Primary household purchasers conducting ingredient research through parenting forums and dermatology clinic handouts. Millennial and Gen-Z parents in the United States and Germany prioritize EWG ratings and clean beauty certifications over heritage brand loyalty.
- Hospitals:Neonatal units and pediatric wards in the United States, Germany, and Japan specify barrier creams for discharge kits through group purchasing organization contracts. Three dominant GPOs consolidate procurement decisions from 40+ independent formulary committees.
- Caregivers:Daycare staff and extended family members purchasing for shared custody or grandparent care arrangements.
- Maternity Clinics:Birth centers and midwife practices in Pacific Northwest and New England sourcing B-corp certified alternatives.
Parents drive absolute unit volume, while Hospitals are gaining share fastest on formulary standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial parents in the United States, Germany, and Japan command premium shelf positioning for clean-label formulations, while hospital formulary procurement in these markets institutionalizes barrier-cream adoption through discharge kit mandates.
United States
CVS and Walgreens pharmacy chains capture volume through pharmacist-endorsed recommendations, while FDA oversight of zinc oxide concentration limits shapes formulation standards. The Pacific Northwest and New England corridor concentrates demand for B-corp certified alternatives outside group purchasing organization networks.
Germany
Dm-drogerie markt and pharmacy networks sustain heritage brand loyalty among parents seeking pediatrician-validated options, with EMA pediatric investigation plans extending timelines for atopic-prone skin claims. The Rhine-Ruhr and Bavarian metropolitan clusters concentrate dermatology clinic expansion driving clinical-channel premium positioning.
Japan
Hospital discharge kit procurement through institutional formulary protocols anchors routine preventive use, while METI quasi-drug standards create preservative compliance boundaries that favor established players. The Kanto and Kansai regions concentrate neonatal unit purchasing power and midwife practice demand for microbiome-friendly alternatives.
India
Tier-2 city pharmacy penetration in Lucknow, Indore, and Kochi accelerates as BIS certification harmonization with CDSCO cosmetic registration lowers multinational entry barriers. The Maharashtra and Gujarat industrial corridors concentrate contract manufacturing capacity serving both domestic and export formulation demand.
China
NMPA cross-border e-commerce pilot zones enable duty-deferred entry for natural formulations, bypassing standard registration timelines for digitally native parents in Shanghai and Beijing. The Yangtze River Delta cluster concentrates logistics infrastructure supporting subscription-based replenishment models.
Baby Diaper Rash Cream Market Key Industry Players
Player mix skews toward multinational consumer health conglomerates with pharmacy chain shelf dominance and heritage pediatrician endorsement. Three structural tiers operate: mass-market volume leaders with hospital formulary access, premium botanical specialists capturing urban clean-label segments, and private-label substitutes compressing mid-tier margin pools. Competitive moves concentrate on M&A absorption of dermatology-credible challengers and backward integration into zinc oxide supply security.
Among heritage pharmaceutical conglomerates, Procter & Gamble, Johnson & Johnson, and Beiersdorf AG occupy positions reflecting divergent strategic anchoring. Procter & Gamble exemplifies mass-market distribution infrastructure scale. Johnson & Johnson represents pediatrician-endorsed heritage brand equity with extensive hospital formulary relationships. Beiersdorf AG sits within the dermatological credibility tier, transferring adult skincare research pipelines into infant barrier protection positioning.
| Leading Market Players |
|---|
| Himalaya Drug Company |
| Procter & Gamble |
| Johnson & Johnson |
| Sudocrem |
| Sebapharma |
| Beiersdorf AG |
| Weleda |
| Burt's Bees |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
FDA and EMA purity-grade certification regimes simultaneously gate zinc oxide supplier qualification and stratify price tiers across infant barrier cream portfolios. Pharmaceutical-grade feedstock requirements compress legacy supplier margins while enabling botanical-alternative entrants to command 40-60% premiums through clean-label positioning.
Pricing Analysis
Biomimetic lipid formulations versus conventional petrolatum barriers versus next-generation microbiome-adjunct platforms define the technology-generation pricing gap confronting procurement teams. Three-tier pricing structure across premium ceramide complexes, standard zinc oxide barriers, and economy petrolatum bases reflects ingredient sourcing transparency and pediatric endorsement levels. Cost compression in standard-tier petrolatum formulations is intensifying because refinery output volatility in the US Gulf Coast transmits directly to base-material instability. Mass-market parents in pharmacy chains exhibit highest price sensitivity, whereas hospital formulary purchasers prioritize clinical validation over unit cost.
Supply Chain Analysis
Inventory cycles for API-grade zinc oxide extend 12-18 months due to pharmaceutical purity audit queues at German and Chinese chemical manufacturers. Active ingredient supply concentrates in Germany, China, and India, with formulation finishing distributed across United States, European, and Japanese contract manufacturing networks. Raw material dependencies rest on petroleum refinery byproduct streams for petrolatum bases, botanical extraction capacity for oat and shea derivatives, and fermentation infrastructure for prebiotic adjuncts. Single-source vulnerability concentrates in three German and Chinese zinc oxide producers when purity certifications lapse. Distribution runs through pharmacy chain wholesale networks in developed markets and cross-border e-commerce logistics clusters in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA pediatric investigation plan mandates for atopic-prone skin claims represent a regulatory inflection accelerating consolidation around dermatology-credible research pipelines. This disruption favors players with captive clinical validation infrastructure over formulation-assemblers.
For Market Incumbents: Shield formulary access relationships by securing captive zinc oxide supply through backward integration into pharmaceutical-grade chemical manufacturing. Invest in EMA-compliant infant stratum corneum hydration studies at academic medical centers in France and the Netherlands to preempt botanical-entrant credibility claims. Channel control through group purchasing organization contract consolidation remains essential as three dominant GPOs collapse 40+ independent hospital procurement decisions.
For New Entrants and Emerging Players: Subscription replenishment algorithm gaps expose incumbent under-service of digitally native parents seeking auto-replenish convenience tied to diaper consumption data. Pacific Northwest and New England maternity clinics sourcing B-corp certified alternatives outside GPO networks offer the most penetrable white-space. Direct-to-consumer portals with practitioner-specific credentialing bypass pharmacy chain slotting fee barriers.
For Investors and Strategic Acquirers: REACH preservative restriction implementation reshapes the acquisition landscape toward microbiome-friendly formulation capabilities with phenoxyethanol-free stability science. Five-to-ten year viability hinges on regulatory compliance capacity rather than brand heritage alone. Target acquisition archetypes include dermatology-credible challengers with EMA pediatric investigation plan execution experience. Monitor FDA warning letter velocity targeting cosmetic-cosmeceutical claim boundary enforcement as the signal indicating margin compression timing for legacy-positioned assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API-Grade Zinc Oxide | Captive pharmaceutical-grade supply secures formulary access against German and Chinese producer bottlenecks. |
| EMA Pediatric Investigation Plan Execution | Stratum corneum hydration data generation unlocks atopic-prone skin claims and 18-24 month competitive moats. |
| Direct-to-Consumer Subscription Platform Launch | Auto-replenish algorithms tied to diaper consumption data compress customer acquisition costs among Millennial parents. |
| Prebiotic Microbiome Formulation Development | Inulin and fructooligosaccharide adjuncts open clinical-channel differentiation at dermatology practices seeking evidence-based positioning. |
| Cross-Border E-Commerce Duty Threshold Exploitation | China NMPA pilot zones enable duty-deferred natural formulation entry bypassing standard registration timelines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric dermatologists, hospital formulary directors, pharmacy chain category buyers, contract manufacturing executives, and zinc oxide procurement leads at chemical manufacturers. Secondary validation drew from FDA 21 CFR over-the-counter monograph filings, EMA pediatric investigation plan submission databases, REACH Annex VI preservative restriction updates, Nielsen retail audit data, and customs records tracking API-grade zinc oxide trade flows. Bottom-up unit volume estimates triangulated against top-down market sizing across formulation type, brand tier, and distribution channel dimensions.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, brand positioning tier, distribution channel access level, and geographic regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macro-infant demographic trends and channel shift elasticity parameters. Forecast inputs incorporated hospital discharge kit formulary standardization mandates, subscription replenishment model penetration curves, and REACH preservative reformulation cost pass-through assumptions.
Underlying assumptions cover regulatory timeline stability, raw material purity audit pass rates, and pharmacy chain shelf-space allocation continuity, with deviation risk concentrated in FDA warning letter enforcement intensity and refinery output volatility for petrolatum feedstocks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Tablet Keyboards Market
Consumer Goods
China Cookware Market
Consumer Goods
South America Hair Conditioner Market
Consumer Goods
Pearl Jewelry Market
Consumer Goods
Plant-Based Dog Food Market
Consumer Goods
Global Electronic Bidet Seats Market
Consumer Goods
UAE Major Home Appliances Market
Consumer Goods
Barefoot Shoes Market
Consumer Goods
Hunting Boots Market
Consumer Goods
Electric Fireplace Market
Consumer Goods
Sailing Jackets Market
Consumer Goods
Portable Steam Cleaners Market
Consumer Goods
Wireless Keyboard Market
Consumer Goods
Mexico Laundry Appliances Market
Consumer Goods
Surfing Apparel and Accessory Market
Consumer Goods
India Vegan Cosmetics Market