
 Baby Bath and Shower Products Market | 2026-2036
Baby Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Bath and Shower Products Market Outlook
Sulfate-free surfactant chemistry is realigning cost structures across baby cleansing formulations as manufacturers reformulate around milder alternatives. Johnson & Johnson sustains broad retail distribution through pharmacy and hospital channels in North America. Henkel AG & Co. KGaA differentiates via dermatological testing protocols and European manufacturing scale. Beiersdorf specializes in sensitive-skin positioning with fragrance-free lines across German-speaking markets.
Baby bath and shower products encompass liquid cleansers, solid bars, and conditioning formulations designed for infant and toddler skin with pH-balanced, tear-free, and hypoallergenic properties; these products typically exclude sulfates, parabens, and synthetic dyes to minimize irritation during daily hygiene routines. The shampoo segment dominates volume due to frequent washing requirements in early childhood, while organic ingredient classifications command premium shelf positioning and expanded margin pools. Natural positioning within ingredient type segments is gaining fastest as clean-label claims reshape parental purchasing criteria across developed markets.
REACH in Europe and FDA cosmetic labeling requirements in the United States enforce stringent ingredient disclosure and safety substantiation, compelling reformulation investments and documentation costs that favor established manufacturers with regulatory affairs infrastructure. The EU Green Deal and emerging state-level chemical restrictions in California are tightening permissible substance lists, reshaping raw material sourcing strategies. Stakeholders must monitor evolving patchwork compliance obligations across multiple jurisdictions to anticipate formulation mandates before they disrupt supply continuity.
Market Dynamics
Sulfate-free surfactant chemistry is forcing wholesale reformulation across baby cleansing portfolios as manufacturers absorb elevated raw material costs and recertification expenses to meet clean-label mandates from millennial and Gen Z parents.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH substance bans are accelerating R&D investment in biodegradable surfactant alternatives, creating first-mover advantages for compliant suppliers.
- Pharmacy channel concentration:Hospital and clinic procurement networks in Germany and France are consolidating purchasing around dermatologically tested infant formulations.
- Solid bar format innovation:Waterless cleansing formats are reducing packaging waste and shipping costs while appealing to sustainability-focused parental segments.
Market Restraints
- Surfactant input cost volatility:Coconut-derived glucoside prices fluctuate with Philippine and Indonesian agricultural yields, compressing margin stability for natural-positioned brands.
- European regulatory documentation burden:ECHA safety substantiation requirements demand toxicology dossiers that smaller formulators cannot finance independently.
- Private-label substitution threat:Retailer-owned baby care lines at dm-drogerie markt and Target are capturing price-sensitive volume with mimicked clean-label claims.
Strategic Opportunities
- Underpenetrated French organic segment:ECOCERT and COSMOS-certified infant cleansers hold sub-15% shelf space in hypermarkets outside Paris and Lyon.
- Subscription direct-to-home channels:Recurring delivery models for sensitive-skin formulations are building predictable revenue streams and reducing customer acquisition costs.
- Biotechnology convergence:Fermentation-derived ceramides and postbiotic complexes are enabling next-generation barrier-support claims beyond basic mildness.
Industry Challenges
- Toxicologist and regulatory affairs talent scarcity:Qualified safety assessors familiar with pediatric exposure scenarios command premium compensation in Basel and Frankfurt.
- Multi-jurisdiction certification timelines:Simultaneous FDA notification and EU CPNP filing for new preservative systems extends time-to-market by 18-24 months.
- Legacy ERP integration with traceability platforms:Batch-level ingredient tracking for supply chain transparency requires expensive middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Bath and Shower Products Market |
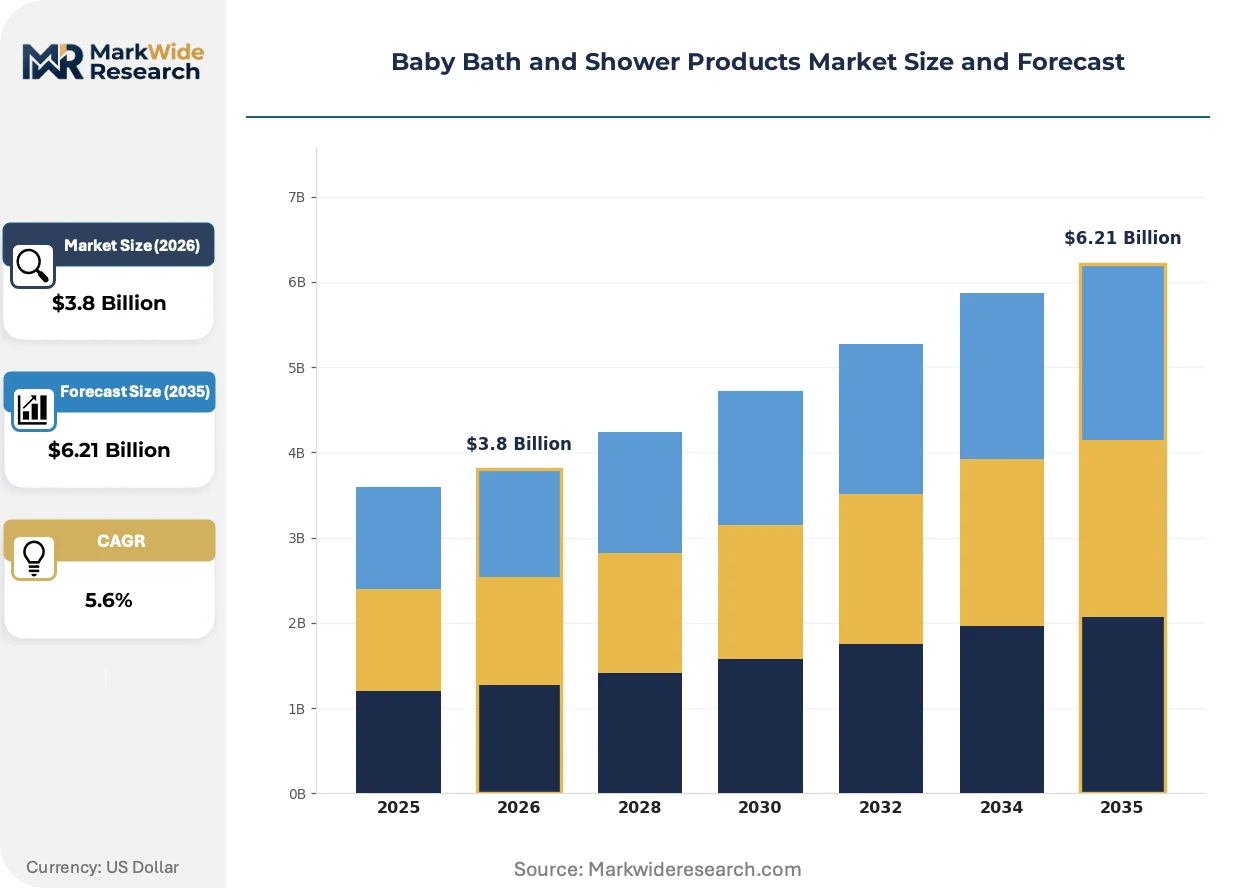
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Body Wash, Soap, Conditioning Gel Ingredient Type: Natural, Organic, Hypoallergenic, Fragrance-Free Age Group: Newborn, Infant, Toddler, Pre-school Packaging Type: Tube, Bottle, Pump, Pouch |
| Companies Covered | L'Oréal, Colgate-Palmolive Company, Johnson & Johnson, Mothercare, Henkel AG & Co. KGaA, Procter & Gamble, Beiersdorf, Honasa Consumer Limited, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Bath and Shower Products Market Strategic Shifts
Clean-label ingredient transparency is compressing formulation timelines and elevating biotechnology-derived alternatives across infant personal care portfolios.
Plant-based emulsification systems are expanding into tear-free shampoo and wash formulations as suppliers replace PEG-derivatives with lecithin and saponin complexes. Mid-tier manufacturers in the United States and Germany are adopting these systems fastest to avoid California Proposition 65 litigation exposure. The technology is expanding into premium positioning while forcing commodity suppliers to absorb margin compression or exit pediatric segments entirely.
REACH Annex XVII restrictions on microplastics are compelling reformulation of exfoliating and visual-effect additives in toddler wash products. The European Chemicals Agency enforcement timeline is accelerating substitution toward cellulose and mineral-based alternatives. Fragrance-free and minimal-ingredient lines for atopic-prone infants face the steepest compliance costs, driving consolidation among contract manufacturers.
Ingredient-scanning mobile applications are reshaping parental purchase verification habits in urban United States and United Kingdom markets. Millennial buyers photograph shelf labels to cross-reference against EWG Skin Deep and Yuka databases before adding items to carts. This behavior concentrates demand around brands with fully disclosed supply chains and third-party organic certifications, penalizing legacy portfolios with undisclosed fragrance components.
Baby Bath and Shower Products Market Segmentation
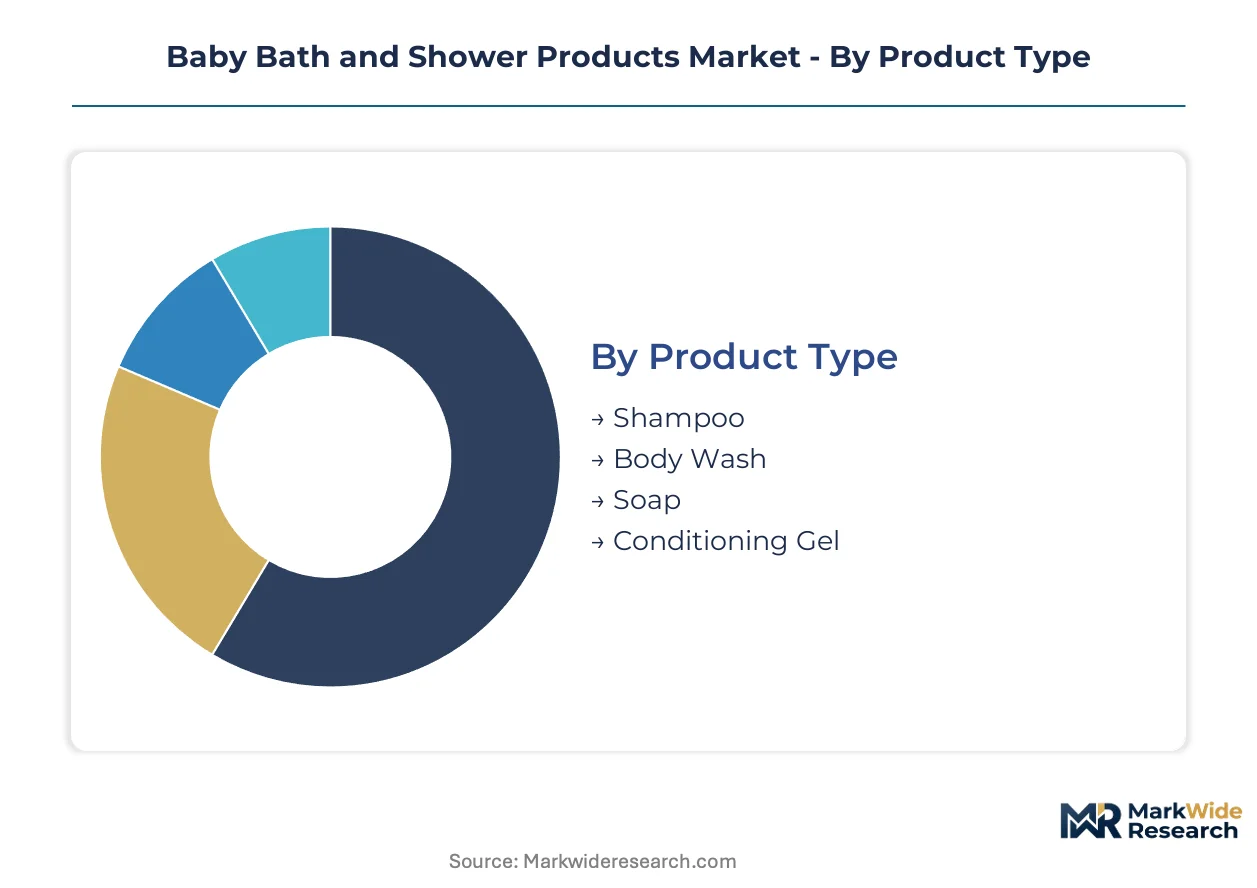
Segmentation in baby bath and shower products determines regulatory pathways, margin structures, and channel access. Certification requirements vary sharply across ingredient classifications, while age-group targeting dictates formulation chemistry and safety testing protocols.
Product Type:
ECOCERT and COSMOS certifications apply selectively across this category, with liquid formats facing stricter preservative scrutiny than solid alternatives. FDA cosmetic notification requirements in the United States and EU CPNP filings create divergent compliance timelines for each format.
- Shampoo:Tear-free formulations rely on amphoteric surfactants such as cocamidopropyl betaine combined with pH buffering systems between 4.5 and 5.5. Demand concentrates in pharmacy and hospital procurement networks across Germany and France, where dermatological testing documentation is mandatory for institutional purchasing. Frequent washing requirements in early childhood sustain volume leadership despite higher per-unit formulation costs than body wash alternatives.
- Body Wash:Liquid cleansers incorporate milder glucoside surfactants derived from coconut and corn sugars to maintain skin barrier integrity. Millennial parents in urban United States markets prioritize pump-dispense formats for single-handed use during bathing. REACH Annex XVII restrictions on microplastic additives are forcing rapid reformulation of visual-effect variants in this segment.
- Soap:Solid bar formats bypass preservative requirements entirely, appealing to zero-waste positioning and reducing shipping weights. Saponin-based cleansing systems from soapnut and quillaja extracts are gaining traction in German-speaking markets.
- Conditioning Gel:Leave-in and rinse-out detangling formulations target toddler and pre-school age groups with longer hair. Cationic conditioning agents require separate safety substantiation for pediatric ocular exposure scenarios.
Leading the category by volume: Shampoo. Growing fastest: Conditioning Gel.
Ingredient Type:
Cost tiers in this category separate commodity-positioned products from premium segments commanding shelf space in pharmacy and specialty retail channels. Raw material sourcing complexity and certification documentation expenses create steep tier boundaries.
- Natural:Plant-derived surfactants, emollients, and preservatives without synthetic petrochemical inputs. Demand concentrates in dm-drogerie markt and Target private-label programs that mimic premium positioning at reduced price points. Agricultural yield volatility in Philippine coconut regions creates input cost instability for glucoside-based formulations.
- Organic:ECOCERT and COSMOS-certified ingredients with full supply chain traceability and prohibited substance lists. French hypermarkets outside Paris and Lyon show sub-15 percent shelf penetration, creating expansion opportunity for certified entrants. Certification costs and annual audit requirements exclude smaller formulators from this tier.
- Hypoallergenic:Dermatologically tested formulations with reduced allergen profiles and pediatric safety substantiation. Hospital and clinic procurement networks in Germany mandate this classification for institutional purchasing.
- Fragrance-Free:Complete absence of masking agents and essential oils, targeting atopic-prone infants and parental sensitivity concerns. ECHA documentation requirements for trace fragrance contaminants impose analytical testing burdens that favor manufacturers with in-house toxicology capabilities.
Highest margin tier: Organic. Steepest volume growth: Natural.
Age Group:
Customer type segmentation in this category reflects developmental skin physiology differences that dictate surfactant selection, preservative systems, and safety testing protocols. Each transition point triggers reformulation requirements and regulatory re-submission.
- Newborn:Formulations for the first four weeks emphasize minimal ingredient lists and barrier-support lipids such as ceramide precursors. Neonatal intensive care unit procurement in the United States requires FDA 510(k) clearance for any therapeutic positioning claims.
- Infant:Four weeks to twelve months represents the largest addressable population with standard tear-free and pH-balanced requirements. Subscription direct-to-home channels concentrate recurring revenue in this segment for sensitive-skin positioning.
- Toddler:Twelve months to three years introduces playful formats and mild conditioning for emerging hair density. Solid bar adoption is climbing fastest in this group as parents transition children toward independent bathing routines.
- Pre-school:Three to five years demands conditioning and detangling functionality alongside character-licensed packaging for purchase influence. Biotechnology-derived postbiotic complexes are penetrating this tier for next-generation barrier support claims.
Largest addressable population: Infant. Fastest format innovation: Toddler.
Packaging Type:
Supply concentration in packaging formats reflects manufacturing equipment requirements and sustainability positioning trade-offs. European and North American suppliers dominate differentiated formats while Asian contract manufacturers capture commodity volumes.
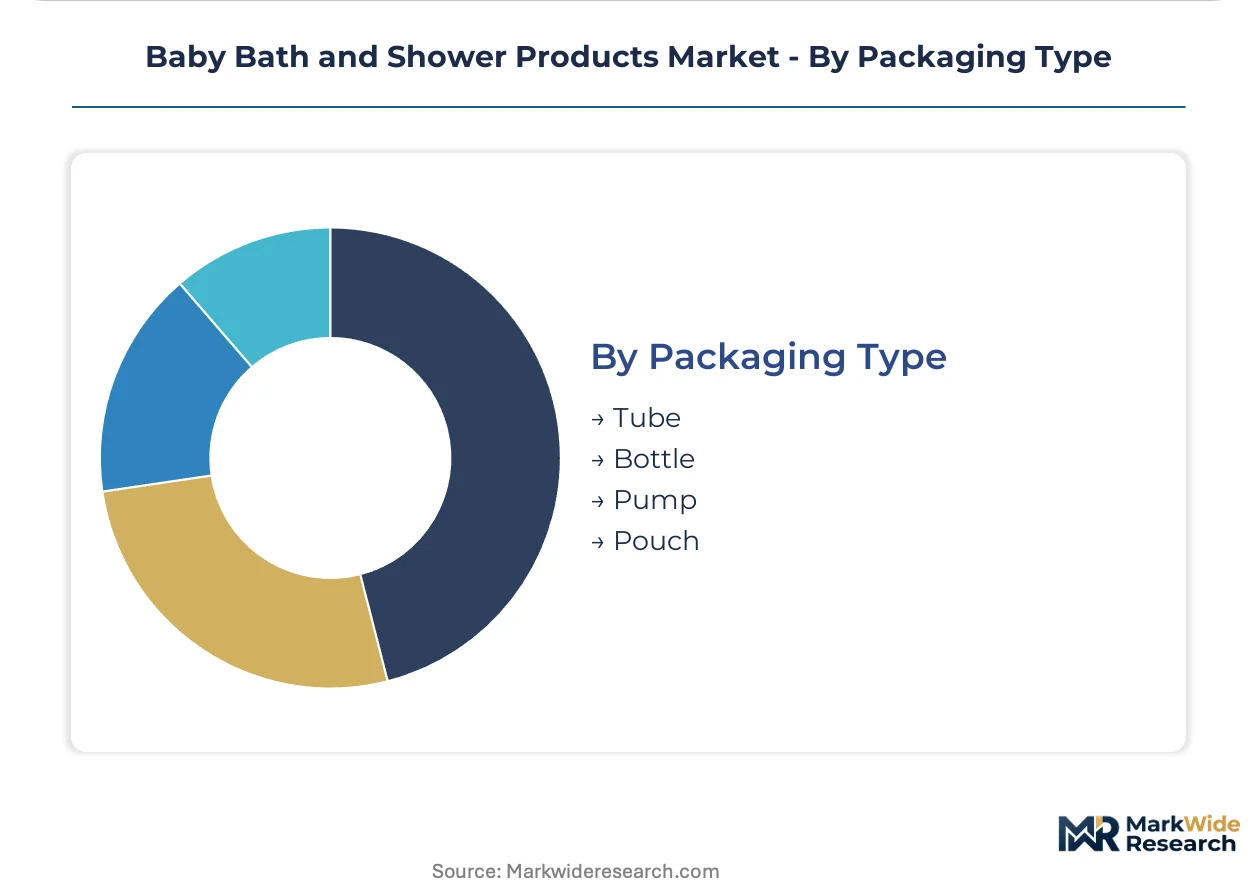
- Tube:Laminated aluminum and plastic multilayer structures offer portability and controlled dispensing for travel and diaper bag contexts. Squeeze-tube formats face EU Single-Use Plastics Directive pressure for recyclability redesign.
- Bottle:Standard HDPE and PET containers dominate mass retail shelf presence with lowest unit packaging costs. Post-consumer recycled content mandates in California and EU member states are elevating rPET sourcing requirements.
- Pump:Single-handed dispensing systems command premium positioning in pharmacy channels and subscription delivery models. Mechanical pump reliability testing for viscous formulations adds quality assurance overhead.
- Pouch:Flexible refill formats reduce per-unit plastic weight and shipping cube, appealing to sustainability-focused segments. Refill infrastructure availability limits geographic penetration to urban United States and Western European markets.
Highest volume format: Bottle. Fastest sustainability-driven growth: Pouch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z parental purchasing concentrates in Germany, the United States, and France, where clean-label demand and pharmacy channel density create premium margin pools for compliant formulations.
Germany
dm-drogerie markt and Rossmann pharmacy chains drive private-label substitution while hospital procurement networks mandate dermatological testing documentation. REACH Annex XVII enforcement through ECHA accelerates biodegradable surfactant adoption. Manufacturing clusters in North Rhine-Westphalia and Hesse host contract laboratories specializing in pediatric toxicology dossiers.
United States
Subscription direct-to-home channels and Target's private-label programs capture price-sensitive volume alongside premium pharmacy positioning. FDA cosmetic labeling requirements and emerging California state-level chemical restrictions reshape formulation mandates. Ingredient-scanning application usage concentrates in urban coastal markets from Seattle to Boston.
France
Hypermarket shelf space for ECOCERT and COSMOS-certified infant cleansers remains underpenetrated outside Paris and Lyon metropolitan areas. EU Green Deal chemical restrictions through REACH substance bans elevate compliance costs for imported formulations. Pharmaceutical manufacturing corridors around Lyon and Strasbourg anchor dermatological testing infrastructure.
United Kingdom
Millennial buyers in London and Manchester metropolitan areas photograph shelf labels to cross-reference against EWG Skin Deep and Yuka databases before purchase. The UK Cosmetics Regulation maintains alignment with EU REACH standards post-Brexit. Biotechnology-derived ingredient development clusters in Cambridge and Oxfordshire support next-generation barrier-support claims.
India
Honasa Consumer Limited and domestic Ayurveda-positioned brands expand distribution through modern trade and e-commerce channels in Delhi-NCR and Mumbai metropolitan regions. BIS cosmetic standards and CDSCO safety requirements create documentation barriers for imported formulations. Manufacturing concentration in Gujarat and Maharashtra supports cost-competitive natural-positioned output.
Baby Bath and Shower Products Market Competitive Environment
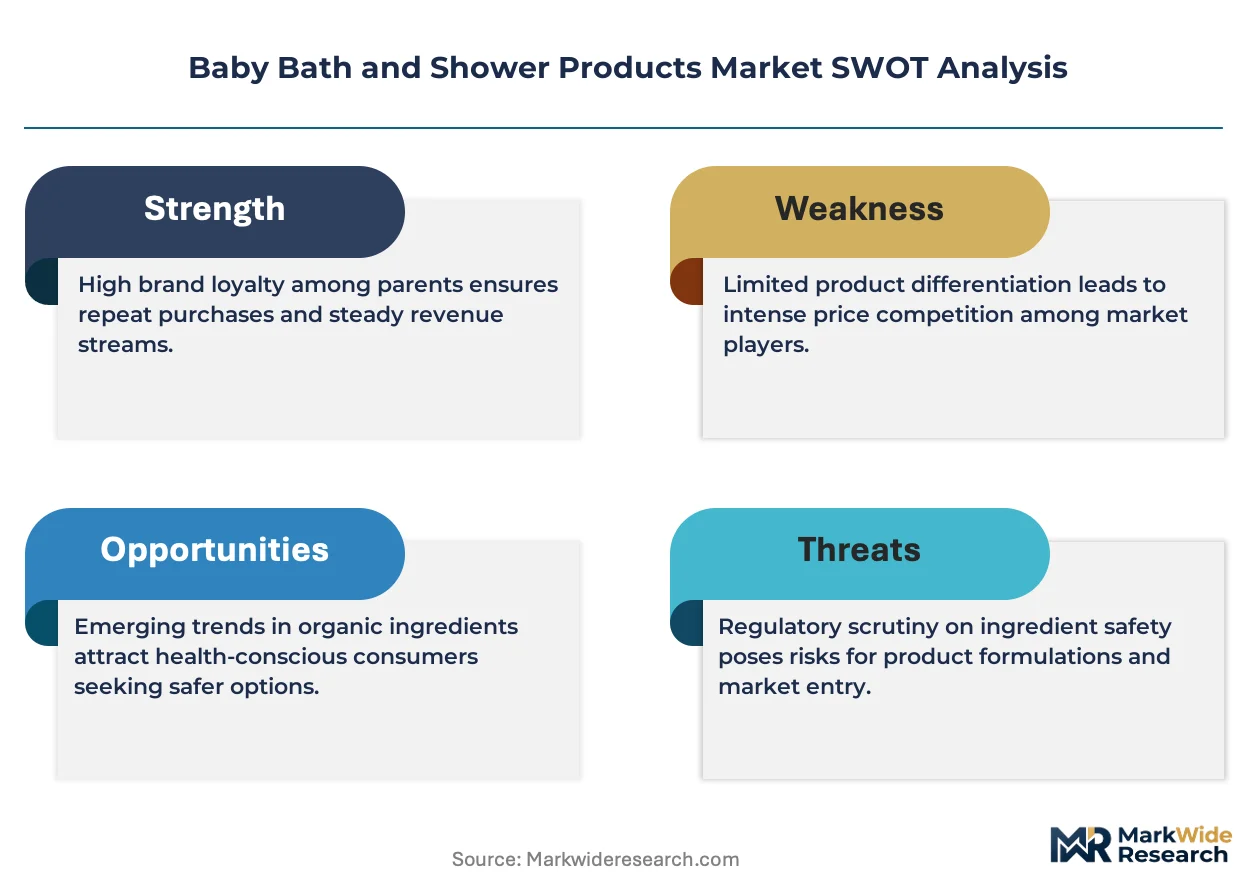
Portfolio diversification dominates the current landscape as established personal care conglomerates acquire clean-label specialists and expand pediatric dermatology credentials. The vendor base separates into three tiers: multinational conglomerates with regulatory affairs infrastructure, mid-tier regional specialists with pharmacy channel relationships, and emerging direct-to-consumer brands with subscription models. Two strategic archetypes define competitive positioning: scale-driven manufacturers absorbing reformulation costs across broad portfolios, and agile specialists capturing premium segments through third-party organic certifications. M&A activity and capacity expansion in biodegradable surfactant production represent the dominant competitive moves.
Among conglomerate-tier players, Johnson & Johnson and Henkel AG & Co. KGaA exemplify scale-driven archetypes with established pharmacy and hospital procurement networks. Beiersdorf occupies a position within the sensitive-skin specialization tier through fragrance-free line positioning. These three entities represent divergent strategic responses to sulfate-free surfactant chemistry realignment: Johnson & Johnson sustains broad retail distribution, Henkel leverages European manufacturing scale with dermatological testing protocols, and Beiersdorf concentrates on atopic-prone infant segments in German-speaking markets.
| Leading Market Players |
|---|
| L'Oréal |
| Colgate-Palmolive Company |
| Johnson & Johnson |
| Mothercare |
| Henkel AG & Co. KGaA |
| Procter & Gamble |
| Beiersdorf |
| Honasa Consumer Limited |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Philippine coconut oil futures and Indonesian palm kernel derivatives cascade through glucoside surfactant production costs, stratifying final product pricing across ECOCERT-certified organic tiers, standard natural-positioned lines, and private-label economy alternatives. REACH documentation burdens and ECHA safety substantiation requirements compound input cost pressures, forcing manufacturers to absorb reformulation expenses or retreat from premium pediatric segments entirely.
Pricing Analysis
Volume concentrates in standard natural-positioned shampoo and body wash formats through mass retail channels, while margin pools accrue to organic-certified and fragrance-free dermatological tiers commanding pharmacy shelf space. Three-tier pricing structure across premium, standard, and economy levels separates ECOCERT-audited formulations with full supply chain traceability from dm-drogerie markt private-label mimics. Pricing pressure stems from coconut-derived glucoside agricultural yield volatility compressing margin stability for natural-positioned brands. Price-sensitive volume concentrates in Target and Rossmann private-label programs, while least sensitivity appears in hospital procurement networks mandating hypoallergenic documentation.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia and Hesse anchor European hub-and-spoke patterns for dermatological testing infrastructure and pediatric toxicology dossier completion. Manufacturing concentration spans Germany, the United States, and France for formulation and compliance documentation, with raw material sourcing drawing from Philippine coconut regions and Indonesian palm kernel suppliers. Single-source vulnerability in Southeast Asian agricultural yields threatens surfactant input continuity. Distribution runs through pharmacy and hospital procurement networks in Germany and France alongside mass retail channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH Annex XVII restrictions and ECHA toxicology dossier requirements erect barrier-to-entry moats favoring established manufacturers with regulatory affairs infrastructure and in-house pediatric safety assessment capabilities.
For Market Incumbents: Deploy backward integration into biodegradable surfactant production capacity to secure input cost control against Philippine and Indonesian agricultural volatility. Consolidate dermatological testing infrastructure through acquisition of North Rhine-Westphalia contract laboratories to defend against private-label substitution threats from dm-drogerie markt and Target. Expand subscription direct-to-home channel penetration to lock in recurring revenue and reduce customer acquisition cost exposure.
For New Entrants and Emerging Players: Capture underpenetrated ECOCERT and COSMOS-certified shelf space in French hypermarkets outside Paris and Lyon metropolitan areas where certified infant cleansers hold sub-15 percent presence. Target solid bar format innovation for toddler age segments as parents transition children toward independent bathing routines and zero-waste positioning. Pursue biotechnology-derived postbiotic complex partnerships with Cambridge and Oxfordshire development clusters for next-generation barrier-support claims.
For Investors and Strategic Acquirers: The window for entry favors mid-tier regional specialists with established pharmacy channel relationships and pending organic certification completion. Long-term viability hinges on regulatory affairs talent density and ECHA documentation infrastructure rather than brand equity alone. Watch for EWG Skin Deep and Yuka database integration rates among millennial parental segments as inflection indicator for clean-label premiumization sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Capacity Expansion | REACH Annex XVII compliance secures first-mover advantage in EU Green Deal-aligned formulations. |
| Dermatological Testing Infrastructure Acquisition | ECHA safety substantiation capabilities exclude smaller competitors from hospital procurement networks. |
| Subscription Direct-to-Home Channel Launch | Recurring delivery models reduce customer acquisition costs for sensitive-skin positioning segments. |
| ECOCERT Certification Investment | Full supply chain traceability commands premium shelf positioning in German pharmacy channels. |
| Solid Bar Format Innovation | Waterless formulations bypass preservative requirements and appeal to zero-waste parental segments. |
Study Parameters
Trade publications, customs records, and Nielsen retail audit data formed the secondary backbone, cross-referenced against primary interviews with brand managers at multinational conglomerates, category buyers at dm-drogerie markt and Target, dermatological testing laboratory directors in North Rhine-Westphalia, and regulatory affairs leads specializing in REACH compliance. Bottom-up volume modeling across shampoo, body wash, soap, and conditioning gel formats triangulated against top-down value assessments derived from pharmacy channel pricing and mass retail scanner data.
Historical trendline analysis tracked sulfate-free surfactant adoption rates, organic certification penetration, and subscription channel growth across the projection horizon. Segmentation dimensions modeled include product type, ingredient classification, age group targeting, and packaging format alongside regional regulatory cluster differentiation. CAGRs were derived from regression analysis of volume and value trajectories, incorporating coconut oil futures volatility indices and ECHA enforcement timeline assumptions as industry-specific forecast inputs.
The model holds under stable REACH enforcement timelines and continued millennial parental preference for clean-label verification; deviation in EU Green Deal acceleration or Philippine agricultural yield disruption would shift surfactant input cost assumptions and reformulation investment requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
DIY PC Gaming Chassis Market
Consumer Goods
Powdered Hand Soap Market
Consumer Goods
Forward Facing Type Child Safety Seats Market
Consumer Goods
Gaming Laptops and Desktops Market
Consumer Goods
Vegan Dog Food Market
Consumer Goods
Australia Washing Machine Market
Consumer Goods
Remote Control Holder Market
Consumer Goods
Spiritual and Devotional Products Market
Consumer Goods
North America Denim Jeans Market
Consumer Goods
Countertop Spray Market
Consumer Goods
France Household Appliances Market
Consumer Goods
Israel Hair Care Market
Consumer Goods
Pet Slow Feeder Bowl Market
Consumer Goods
Window Rain Guards Market
Consumer Goods
Compression and Shapewear Market
Consumer Goods
Adult Sex Dolls Market