
 Asphalt Pavers Market | 2026-2036
Asphalt Pavers Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Pavers Market Intelligence
The performance gap between premium and commodity asphalt paver tiers is decoupling as telematics-equipped machines command widening price premiums over basic mechanical models. Caterpillar Inc. leverages its dealer network density to sustain aftermarket revenue streams across North American highway contractors. Joseph Vögele AG differentiates through precision screed technology that dominates European airport runway specifications. XCMG Construction Machinery Co. Ltd. anchors its position in domestic Chinese road construction through aggressive cost engineering on wheeled paver configurations.
An asphalt paver is a self-propelled engineering vehicle that lays asphalt concrete on roads, bridges, and parking surfaces at specified thicknesses and slopes, typically operating at paving widths from 1.5 meters to 18 meters and temperatures exceeding 140 degrees Celsius. Its primary purpose is to distribute, shape, and partially compact hot mix asphalt into a smooth, durable mat ready for roller compaction. Tracked pavers now lead volume in highway maintenance applications where flotation and traction requirements exclude wheeled alternatives, while 3D paving technology represents the fastest-growing technology segment as contractors replace stringline-based grade control with GPS and laser-guided automated systems. The rental service provider end user category remains the most mature channel, with margin pools shifting toward technology-enabled fleet operators who bundle telematics subscriptions with hourly equipment rates.
The United States Environmental Protection Agency enforces Tier 4 Final emission standards that limit particulate matter and nitrogen oxides from diesel-powered construction equipment, compelling fleet turnover and reshaping manufacturer product development priorities. The European Union's Stage V regulation through ECHA and national type-approval authorities similarly constrains engine certification, while China's Ministry of Ecology and Environment applies dual carbon goals that tighten domestic manufacturing compliance costs. Stakeholders must monitor how emission compliance investments alter the competitive economics between imported and locally manufactured pavers in each major demand cluster.
Market Dynamics
Telematics-enabled fleet management is compressing replacement cycles as contractors demand real-time equipment utilization data to justify capital deployment against tightening municipal budget scrutiny.
Growth Catalysts
- Highway maintenance programs:Federal and provincial infrastructure budgets in the United States, Germany, and China are accelerating equipment procurement timelines for road rehabilitation projects.
- Tier 4 Final standards:The United States Environmental Protection Agency's emission limits on particulate matter and nitrogen oxides are compelling fleet turnover toward cleaner diesel architectures.
- 3D paving technology:GPS and laser-guided automated systems are displacing stringline-based grade control, reducing material waste and labor requirements on precision paving contracts.
Market Restraints
- Engine certification costs:EU Stage V compliance through ECHA and national type-approval authorities adds substantial development overhead for manufacturers serving European contractors.
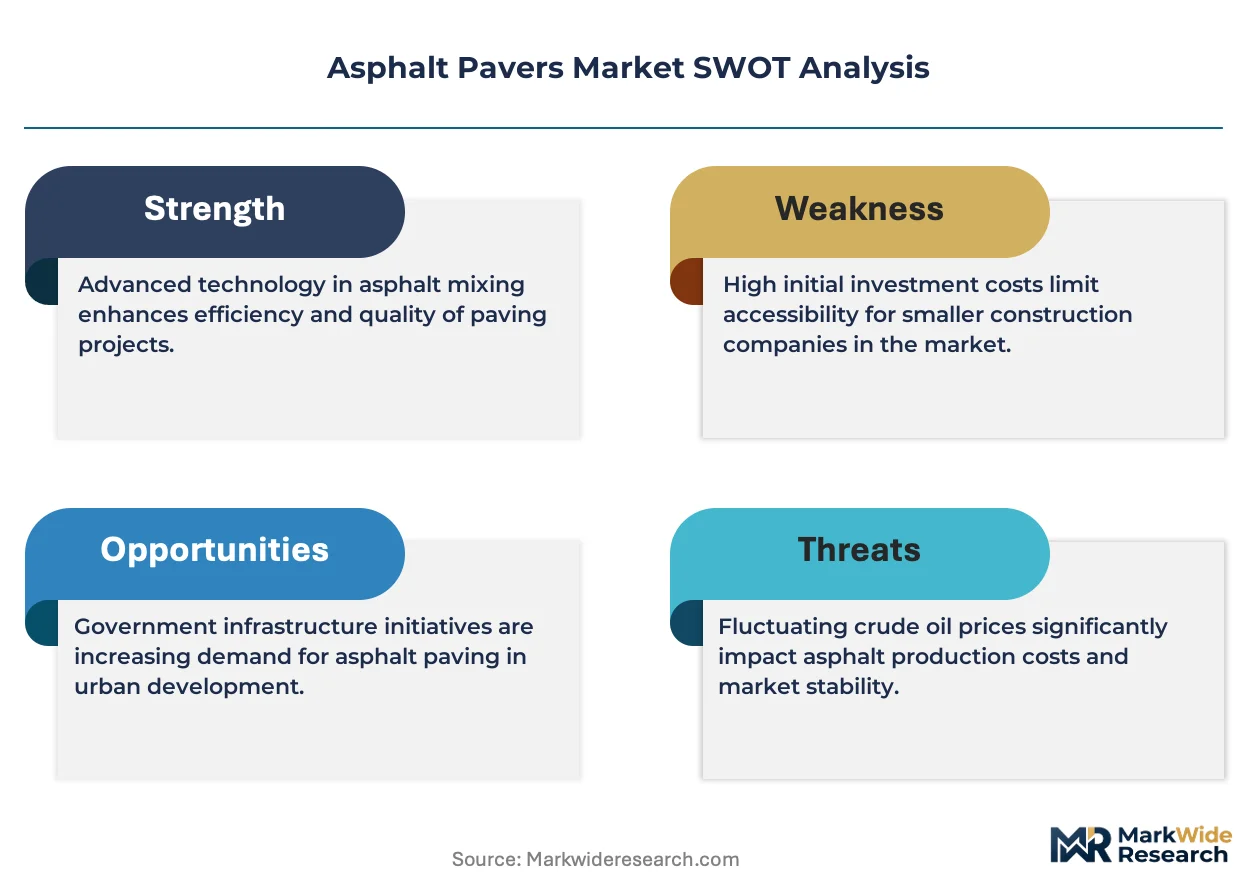
- Steel price volatility:Input cost fluctuations for chassis and screed components compress margin predictability for equipment producers.
- Tracked paver specialization:Highway maintenance applications with flotation and traction requirements exclude lower-cost wheeled alternatives, limiting product portfolio flexibility.
Strategic Opportunities
- Technology-enabled rental bundling:Margin pools are shifting toward fleet operators who package telematics subscriptions with hourly equipment rates, creating recurring revenue streams.
- China's dual carbon goals:The Ministry of Ecology and Environment's tightening compliance standards favor domestic manufacturers with localized supply chains over import-dependent competitors.
- Airport runway specifications:Precision screed technology for high-tolerance surfaces commands price premiums in specialized aviation infrastructure segments.
Industry Challenges
- Telematics integration complexity:Contractors face operational friction retrofitting legacy mechanical fleets with connected diagnostic systems.
- Skilled operator shortages:GPS-guided automation requires retraining programs for traditional paving crews accustomed to manual grade control methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Pavers Market |
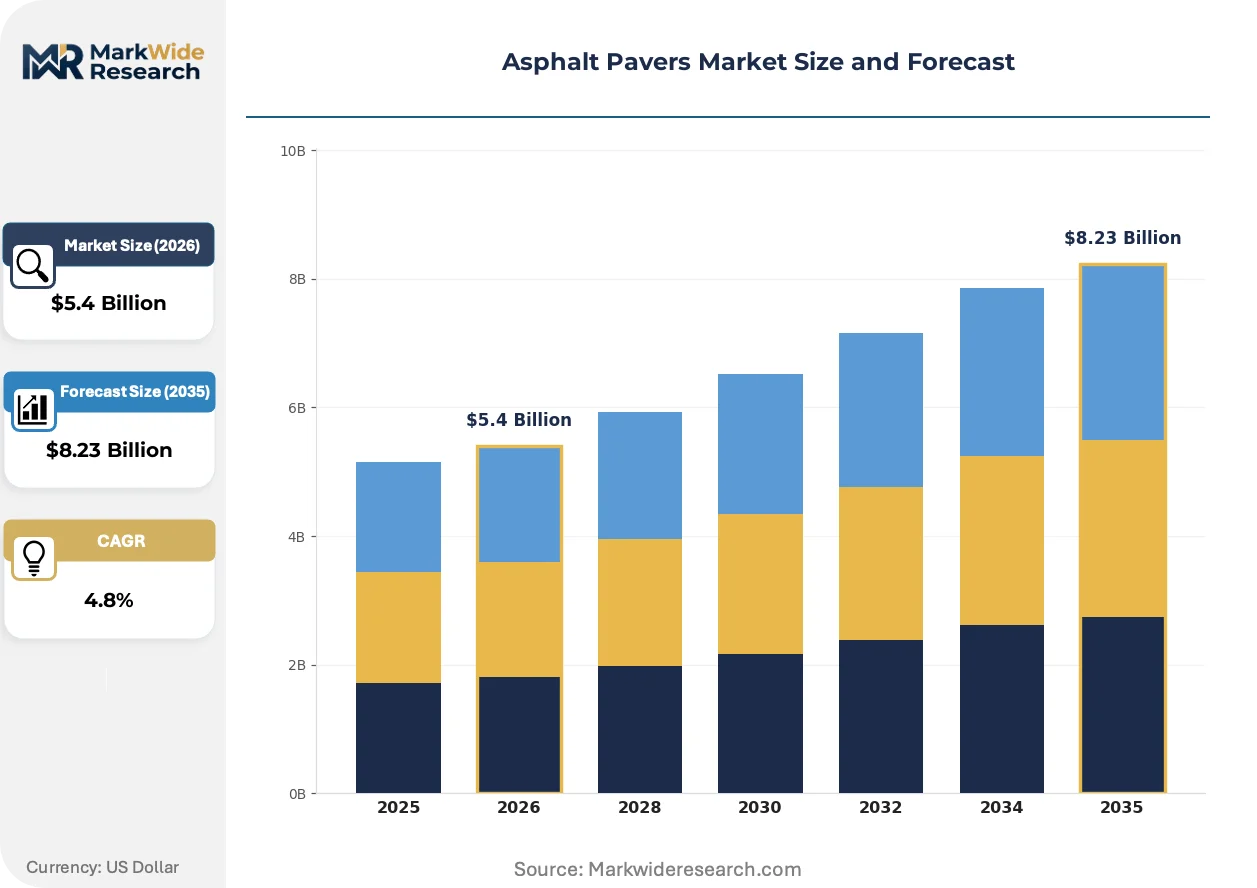
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracked Pavers, Wheeled Pavers, Mini Pavers, Sectional Pavers Application: Road Construction, Airport Runway, Parking Lots, Highway Maintenance End User: Construction Companies, Government Contractors, Rental Service Providers, Infrastructure Developers Technology: Electronic Control, Hydraulic Systems, Automated Paving, 3D Paving |
| Companies Covered | Fayat Group, Dynapac, Caterpillar Inc., Joseph Vögele AG, Bomag GmbH, Wirtgen Group, Ammann Group, XCMG Construction Machinery Co. Ltd., Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Pavers Market Strategic Shifts & Innovations
Equipment intelligence and emission compliance are converging to reshape competitive positioning, with connectivity features becoming the primary differentiation vector rather than mechanical specifications alone.
GPS-guided 3D paving control is decentralizing grade management authority from survey crews to machine operators. Municipal highway departments and commercial paving contractors are adopting these systems at accelerating rates for projects requiring sub-centimeter elevation tolerance. Real-time kinematic positioning is compressing pre-construction survey timelines and reducing rework costs on complex intersection geometries.
The European Union's Stage V regulation through ECHA constrains diesel engine certification for non-road mobile machinery. Manufacturers must redesign exhaust after-treatment systems and thermal management architectures to meet particulate number limits. Equipment producers serving German, French, and Italian markets are prioritizing engine platform consolidation to amortize compliance investments across product families.
Service contract unbundling is fragmenting traditional dealer revenue models. Large highway contractors in the United States are negotiating direct telematics data access rather than purchasing bundled maintenance agreements. Equipment financiers are responding with usage-based lease structures that tie payment obligations to machine productivity metrics rather than calendar terms.
Asphalt Pavers Market Segmentation
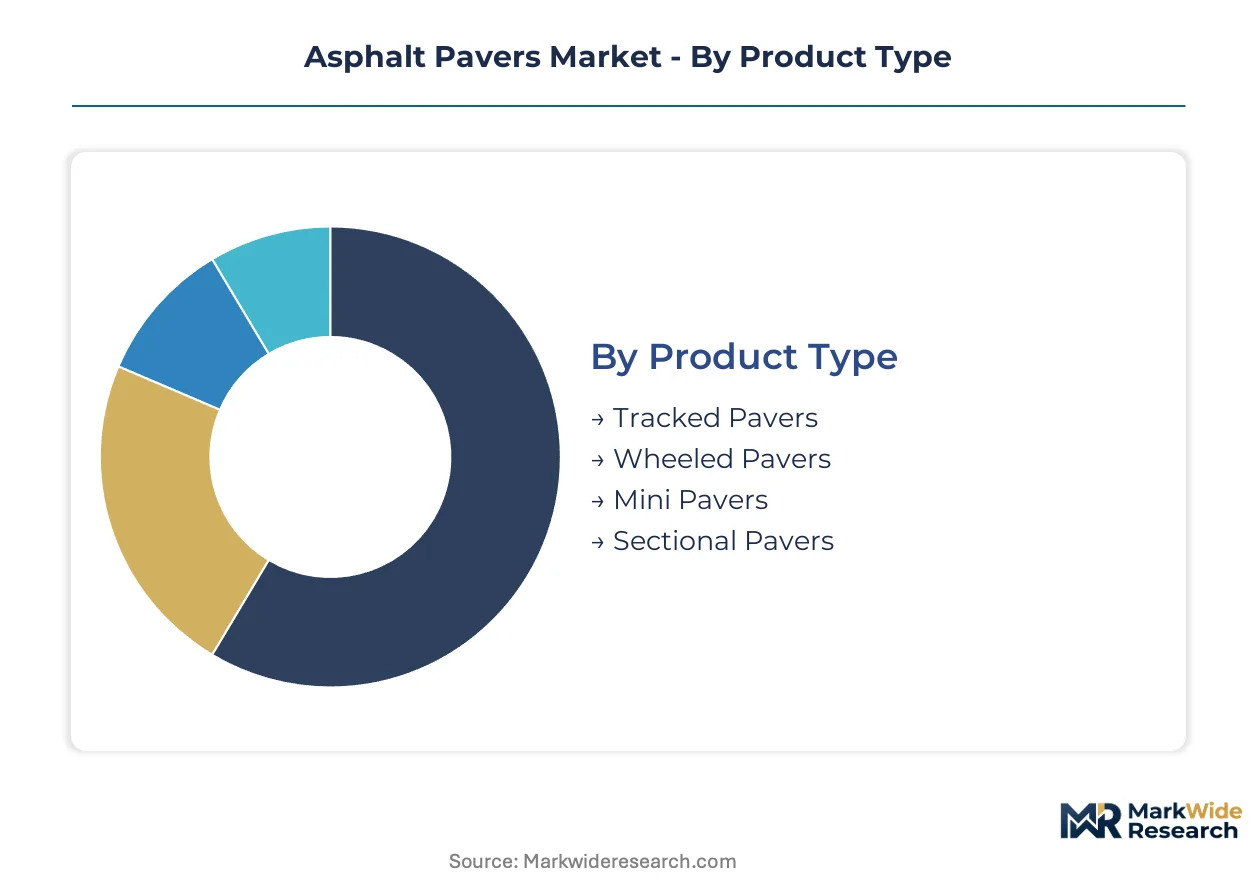
Equipment procurement patterns diverge sharply across customer types and project scales, with highway contractors prioritizing flotation performance while municipal fleets favor wheeled mobility for urban constraints. Technology adoption curves further stratify the installed base, separating telematics-enabled operators from mechanical-legacy holdouts.
Product Type:
Capital intensity peaks with tracked configurations requiring reinforced undercarriages and dual-width screeds, while mini pavers demand lower upfront commitment but restrict fleet versatility.
- Tracked Pavers:Continuous track systems distribute machine weight across soft subgrades and unimproved surfaces, enabling year-round operation in highway maintenance zones. United States federal highway contractors specify these units for interstate rehabilitation contracts where traction requirements exclude alternatives. Tier 4 Final compliance investments concentrate here due to engine displacement thresholds.
- Wheeled Pavers:Rubber-tire mobility permits rapid site relocation and reduced surface damage on finished binder courses, dominating urban road construction in Germany and China. Provincial infrastructure budgets in lower-tier Chinese cities favor these configurations for cost-engineered procurement programs.
- Mini Pavers:Compact chassis designs access confined commercial parking structures and residential driveways where maneuverability trumps throughput.
- Sectional Pavers:Modular screed attachments enable width reconfiguration mid-project for variable lane geometries on airport taxiway contracts.
Tracked pavers absorb the bulk of installed capacity; 3D paving technology is expanding most quickly across all chassis types.
Application:
Project scale dictates equipment specification, with runway tolerances demanding precision screed technology that road builders rarely require.
- Road Construction:Greenfield highway and arterial road projects specify standard paving widths from 2.5 to 9 meters, with screed extensions available for temporary widening. German federal transport infrastructure budgets prioritize these contracts for economic stimulus allocation.
- Airport Runway:Sub-centimeter elevation tolerances and high-tolerance surface regularity specifications command premium pricing for precision screed systems. Joseph Vögele AG dominates European aviation infrastructure procurement through specialized technology validated by EASA certification requirements.
- Parking Lots:Lower-specification commercial work tolerates basic grade control, concentrating demand among rental fleet operators serving regional contractors.
- Highway Maintenance:Rehabilitation-focused contracts emphasize flotation and rapid mobilization, favoring tracked units with minimal ground pressure ratings.
Road construction commands the dominant share of annual equipment hours; airport runway specifications yield the steepest margin premiums.
End User:
Customer sophistication varies from technology-integrated fleet operators to price-sensitive municipal procurement offices.
- Construction Companies:Large integrated contractors in the United States negotiate direct telematics data access and usage-based lease structures tied to productivity metrics. These operators consolidate purchasing power across multi-state project portfolios.
- Government Contractors:Federal and state procurement offices enforce standardized specification compliance, with EPA emission certification serving as mandatory bid qualification.
- Rental Service Providers:Fleet operators bundle hourly equipment rates with telematics subscriptions, shifting margin pools toward recurring revenue streams.
- Infrastructure Developers:Private concession holders prioritize total cost of ownership calculations over upfront capital expenditure.
Construction companies deploy the largest share of high-technology units; rental service providers are climbing fastest in connected fleet penetration.
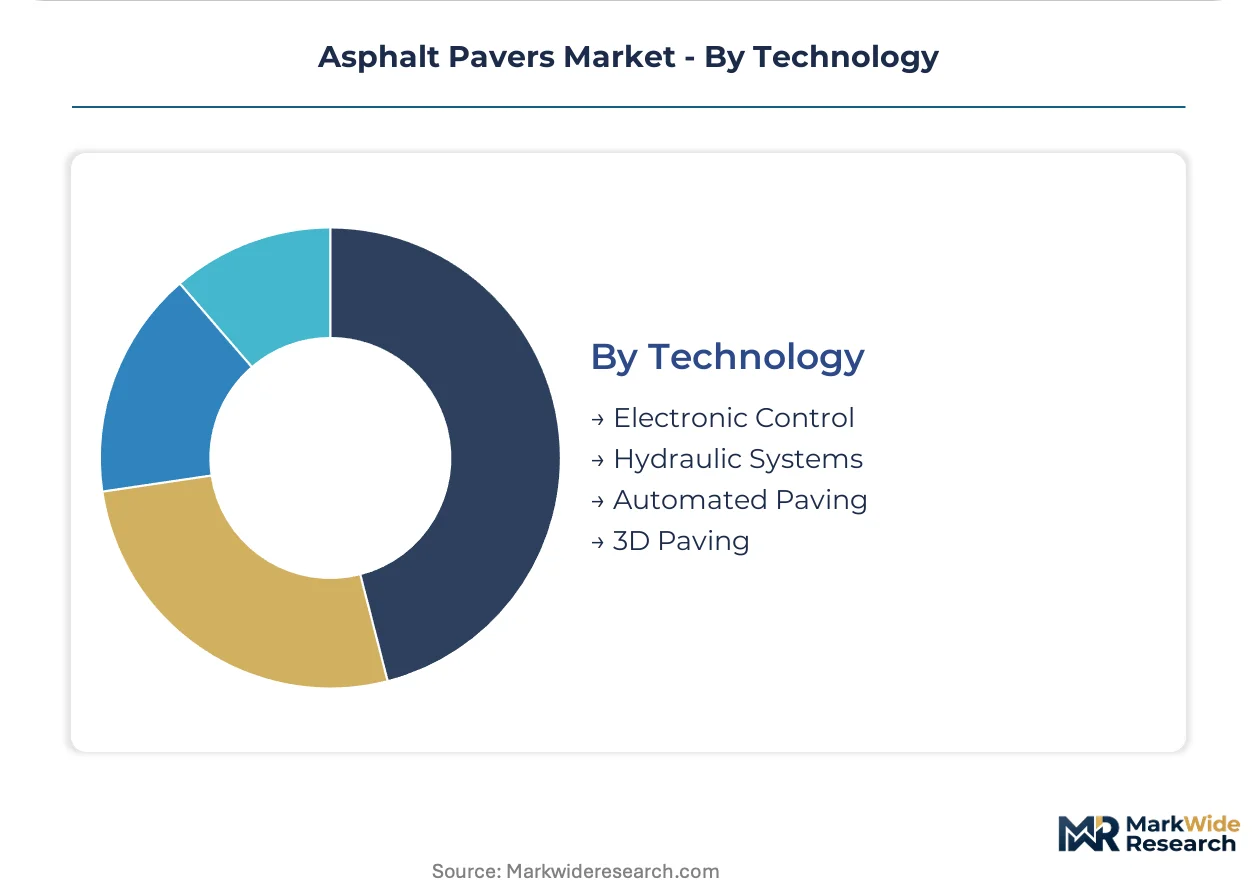
Technology:
Control system architecture separates premium pricing tiers, with automated grade management commanding widening premiums over manual alternatives.
- 3D Paving:GPS and laser-guided automated systems displace stringline-based grade control, reducing pre-construction survey timelines and material waste on complex intersection geometries. Municipal highway departments in the United States adopt these systems for sub-centimeter elevation tolerance requirements.
- Electronic Control:Digital screed adjustment and automatic thickness regulation enable real-time mat quality monitoring, standard on mid-tier highway contractor specifications.
- Hydraulic Systems:Conventional power transmission architectures persist in cost-engineered wheeled pavers for emerging market price sensitivity.
- Automated Paving:Integrated machine guidance combines steering automation with material feed optimization, reducing operator skill requirements.
Electronic control systems anchor the majority of current installations; 3D paving technology is gaining share fastest among municipal procurement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peoria, Illinois anchors North American paver demand through Caterpillar's manufacturing footprint and dense dealer network serving federal highway contractors across the Midwest corridor.
United States
Interstate rehabilitation contracts drive tracked paver procurement as state DOTs accelerate replacement cycles under IIJA funding allocations. EPA Tier 4 Final enforcement compels fleet turnover in Texas, California, and Florida markets. Oklahoma City contractors deploy telematics-enabled units for real-time productivity tracking on municipal projects.
Germany
Federal transport infrastructure budgets prioritize precision runway specifications at Frankfurt and Munich airports. EU Stage V compliance through ECHA constrains engine certification timelines for Mannheim-based fabricators. Bavarian highway maintenance zones favor flotation-capable tracked configurations for year-round asphalt laying operations.
China
Provincial infrastructure expansion in lower-tier cities sustains wheeled paver volume for cost-engineered procurement programs. MEE dual carbon goals tighten domestic manufacturing compliance costs. Xuzhou construction equipment clusters anchor supply chain localization for domestic fleet operators.
India
National highway development under NHAI tenders accelerates equipment deployment across Maharashtra and Gujarat corridors. BIS certification requirements for construction machinery create entry barriers for import-dependent suppliers. Mumbai-Pune expressway contractors test GPS-guided grade control on greenfield arterial projects.
Japan
Metropolitan road resurfacing contracts in Tokyo and Osaka prioritize compact wheeled pavers for urban maneuverability. METI energy efficiency guidelines influence equipment specification for municipal procurement offices. Nagoya industrial zones concentrate aftermarket service capabilities for aging fleet refurbishment.
Asphalt Pavers Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated manufacturers with captive component supply face specialized precision-engineering houses. The vendor base separates into three archetypes: scale-driven full-liners dominating highway maintenance contracts, precision screed specialists capturing aviation infrastructure premiums, and cost-engineered regional players serving price-sensitive municipal procurement. Consolidation pressures concentrate among mid-tier European fabricators seeking engine platform consolidation to amortize Stage V compliance investments. Geographic expansion and technology licensing represent the dominant competitive vectors as players seek offset markets for emission-compliant product families.
Within the precision-engineering tier, Joseph Vögele AG and Bomag GmbH exemplify German fabrication excellence for high-tolerance surface specifications. Among scale-driven integrated manufacturers, Caterpillar Inc. anchors North American distribution density through its Peoria-centered dealer network. XCMG Construction Machinery Co. Ltd. occupies the cost-engineered domestic supplier position within Chinese provincial procurement programs.
| Leading Market Players |
|---|
| Fayat Group |
| Dynapac |
| Caterpillar Inc. |
| Joseph Vögele AG |
| Bomag GmbH |
| Wirtgen Group |
| Ammann Group |
| XCMG Construction Machinery Co. Ltd. |
| Volvo Construction Equipment |
| Others |
Cost & Logistics Intelligence
Captive engine production at Caterpillar's Peoria complex anchors both supply security and pricing power for Tier 4 Final-compliant tracked pavers, insulating integrated manufacturers from certification cost volatility that pressures import-dependent competitors serving United States federal highway contractors.
Pricing Analysis
Throughput-based pricing tied to square-meter paving capacity anchors contractor procurement decisions, with telematics-enabled units commanding premiums over mechanical equivalents. Price differentiation rests on emission certification tier and connected fleet management bundling. Cost compression in wheeled configurations intensifies as XCMG's cost-engineered domestic supply chains undercut import-dependent rivals. Municipal procurement offices in lower-tier Chinese cities exhibit highest price sensitivity; airport runway contractors in Germany show lowest.
Supply Chain Analysis
Dual-sourcing requirements for screed hydraulic systems compel manufacturers to qualify suppliers across Germany, China, and the United States. Steel plate for chassis fabrication and diesel engine blocks for powertrain assembly constitute critical input dependencies. Single-source vulnerability concentrates in precision screed casting foundries serving aviation specifications. Distribution runs through manufacturer-authorized dealer networks for aftermarket parts and service contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asphalt pavers market sits in a technology-transition phase as GPS-guided 3D paving control displaces stringline-based grade management, compressing replacement cycles and reshaping competitive positioning.
For Market Incumbents: Cement dealer network density through telematics data access negotiations, countering direct procurement threats from large integrated contractors seeking unbundled service contracts. Prioritize engine platform consolidation to amortize EU Stage V compliance investments across product families.
For New Entrants and Emerging Players: EPA Tier 4 Final enforcement in the United States opens a window for emission-compliant specialty manufacturers to penetrate federal highway contractor procurement programs. Target tracked paver segments in Texas and Florida where fleet turnover accelerates under IIJA funding. Lead with usage-based lease structures tied to productivity metrics.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision screed technology specialists serving aviation infrastructure premiums. Long-term viability favors manufacturers with captive component supply and localized compliance capabilities. Monitor telematics penetration rates in rental fleet operators as inflection indicator for recurring revenue model adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | GPS-guided 3D paving systems reduce material waste on municipal highway contracts. |
| Emission Compliance Investment | Tier 4 Final and EU Stage V certification expands addressable market for federal contractors. |
| Precision Screed Technology Licensing | Airport runway specifications command price premiums validated by EASA requirements. |
| Dealer Network Expansion | Aftermarket service density sustains recurring revenue from highway maintenance fleets. |
| Cost-Engineered Wheeled Configuration | Provincial budgets in lower-tier Chinese cities favor domestic supply chain localization. |
Research Approach
Document review covered equipment manufacturer technical specifications, EPA emission certification filings, and ECHA Stage V type-approval records, complemented by interviews with highway maintenance fleet managers, municipal procurement officers, and aftermarket service directors. Secondary validation drew from United States DOT infrastructure budget disclosures, German federal transport ministry allocations, and China Ministry of Ecology and Environment compliance bulletins. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending allocation models.
Installed base projections and revenue forecasts emerged from segmentation across chassis type, control system architecture, and end-user procurement sophistication. The analytical framework modeled replacement cycle compression from telematics adoption, emission-driven fleet turnover, and 3D paving technology penetration across the projection horizon. CAGRs derived from equipment hour utilization trends, infrastructure budget growth trajectories, and regional regulatory compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for automated paving control would alter the outlook if skilled operator shortages delay GPS-guided system deployment. Deviation in steel price volatility or engine certification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Middle East Seismic Services Market
Construction and Engineering
Composite Roof Shingle Market
Construction and Engineering
Case Erectors Market
Construction and Engineering
Southern Africa Construction Equipment Rental Market
Construction and Engineering
Spain Prefab Wood Buildings Market
Construction and Engineering
Global Rail Infrastructure Market
Construction and Engineering
Stacker Crane Market
Construction and Engineering
Sawn Timber Market
Construction and Engineering
Sawmill Machinery Market
Construction and Engineering
Asia Pacific Construction Equipment Rental Market
Construction and Engineering
Elevator Ropes Market
Construction and Engineering
Thin Wall Mould Market
Construction and Engineering
Integrated Building Management Systems Market
Construction and Engineering
Vietnam Construction Market
Construction and Engineering
North America HVAC Filter Change Service Market
Construction and Engineering
China Power Tools Market