
 Asia-Pacific Private Equity Market | 2026-2036
Asia-Pacific Private Equity Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Private Equity Market Outlook
Multi-source capital deployment from limited partners is restructuring how Asia-Pacific private equity funds raise and recycle commitments. Temasek Holdings anchors Singapore's sovereign wealth model through direct co-investment structures that bypass traditional fund fees. Hillhouse Capital Group dominates growth-stage technology allocations across Greater China through concentrated sector bets. PAG competes across buyout and special situations in Japan through operational improvement playbooks imported from Western markets.
Asia-Pacific private equity constitutes negotiated equity investments in non-publicly traded companies across venture, growth, and buyout stages, typically structured through limited partnership vehicles with ten-to-twelve-year lockups and carried interest waterfalls tied to hurdle rates. The asset class serves as primary growth financing for unlisted enterprises and as portfolio diversification for institutions seeking illiquidity premiums over public markets. Buyout transactions from closed-end fund structures currently command the deepest capital pools, while venture capital within technology market segments registers the fastest deployment velocity. Sovereign wealth funds as an investor type are displacing pension fund primacy in first-close anchor positions across flagship fundraises.
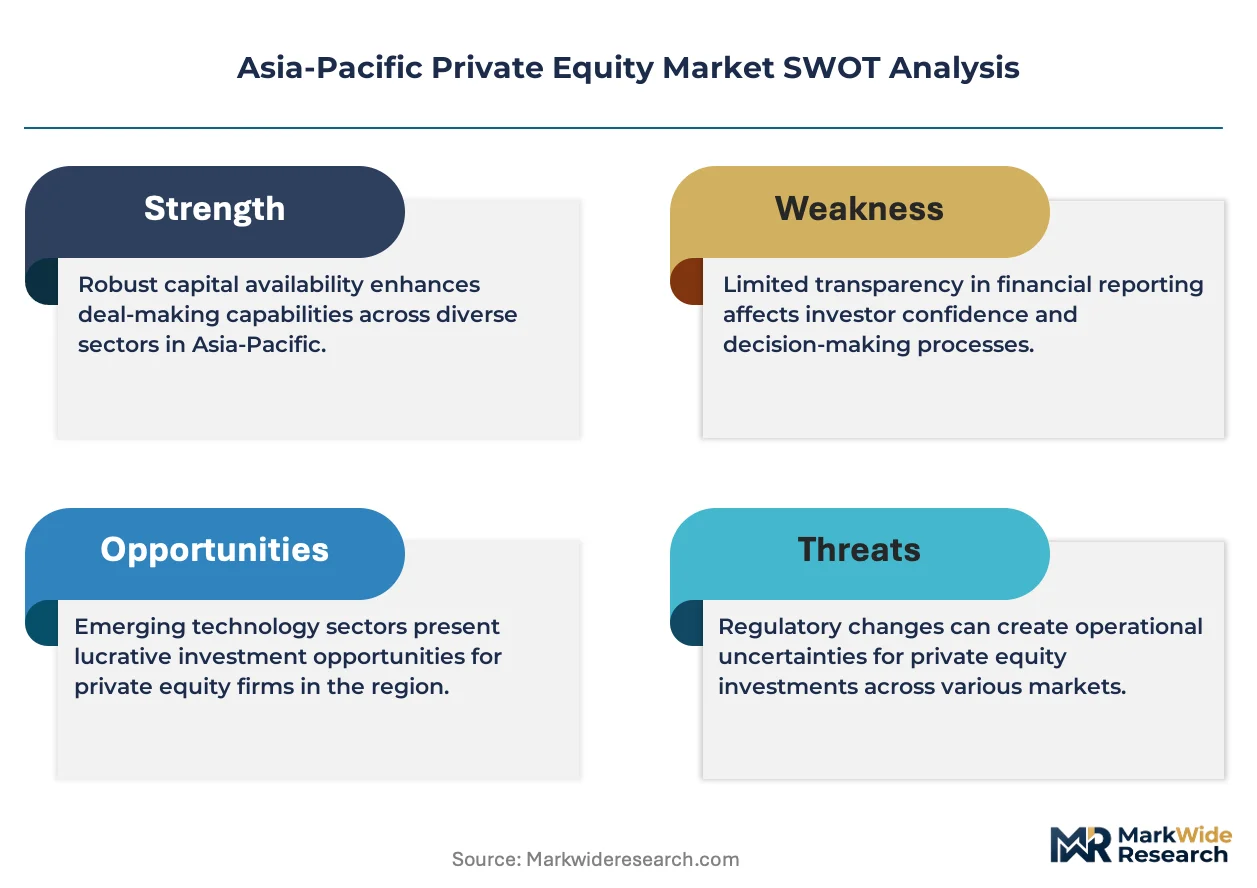
Japan's FSA stewardship code and Singapore's VCC framework together with Australia's ASIC regulatory guidance shape fund structuring costs and cross-border marketing permissions across the region. China's SAMR antitrust reviews and India's SEBI AIF regulations increasingly determine timeline risk and hold period assumptions for control transactions. Stakeholders must track how divergent LP-GP fee negotiations and local content requirements for fund managers reshape competitive access to sovereign capital commitments.
Market Dynamics
Sovereign wealth funds are restructuring Asia-Pacific private equity capital formation by bypassing traditional fund-of-funds fee structures through direct co-investment mandates and separately managed account arrangements.
Growth Catalysts
- Singapore's VCC framework:The variable capital company structure reduces fund domiciliation costs and enables umbrella sub-fund segregation, attracting cross-border capital pools from Japanese institutional investors.
- India's domestic AIF regime:SEBI's alternative investment fund regulations permit Category II structures with pass-through tax treatment, channeling local insurance and pension capital into growth-stage technology deployments.
- Technology sector buyouts:Southeast Asian startup ecosystems are maturing from venture to growth equity, creating control transaction opportunities for operational improvement playbooks.
Market Restraints
- China's SAMR antitrust reviews:Extended merger control timelines for control transactions compress IRR assumptions and extend hold periods beyond traditional fund life cycles.
- Fund manager localization mandates:India's SEBI requires onshore general partner presence for AIF marketing, elevating compliance infrastructure costs for foreign sponsors.
- JPY-denominated deployment constraints:Japan's negative real rate environment limits domestic LP commitment growth, forcing GPs to source offshore dollar commitments for buyout scale.
Strategic Opportunities
- Vietnam's underpenetrated growth capital:Domestic conglomerate spin-outs and family business succession create control equity openings with limited sponsor competition.
- Australia's superannuation capital deepening:A$3.5 trillion in pension assets is rotating toward private markets, creating anchor LP demand for Asia-Pacific-focused flagship funds.
- Climate technology convergence:Renewable energy infrastructure and carbon credit monetization platforms are attracting blended finance structures from development finance institutions.
Industry Challenges
- Cross-border tax treaty navigation:Australia's ATO guidance on permanent establishment attribution creates structuring uncertainty for regional fund platforms with Australian underlying assets.
- Operational due diligence bandwidth:Portfolio company digital infrastructure audits and cybersecurity assessments are extending transaction timelines and elevating pre-close costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Private Equity Market |
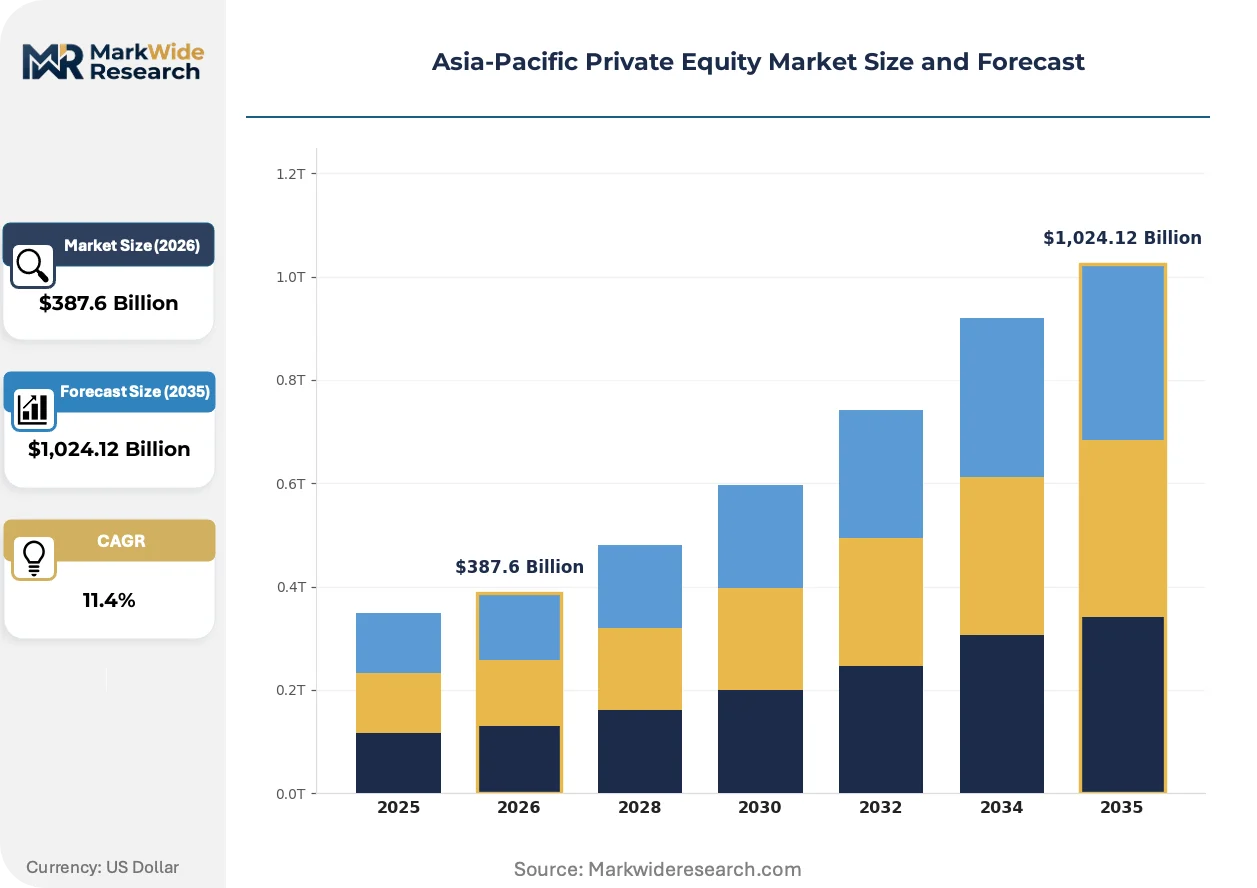
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Venture Capital, Growth Capital, Buyout, Mezzanine Investor Type: Pension Funds, Sovereign Wealth Funds, Family Offices, Institutional Investors Fund Structure: Closed-End Funds, Open-End Funds, Fund of Funds, Co-Investment Funds Market Segment: Technology, Healthcare, Consumer Goods, Financial Services |
| Companies Covered | Hillhouse Capital Group, Temasek Holdings, PAG, MBK Partners, GIC Private Limited, CDH Investments, Affinity Equity Partners, Navis Capital Partners, Everstone Capital, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Private Equity Market Strategic Shifts
Technology-enabled fund operations and regulatory arbitrage across domiciliation choices are compressing cost structures while expanding accessible LP pools beyond traditional pension and endowment anchors.
Artificial intelligence-driven deal sourcing is integrating natural language processing of regulatory filings, patent databases, and supply chain disclosures to identify proprietary transaction opportunities before auction processes commence. Growth-stage sponsors in Greater China are deploying these tools to map corporate venture capital exit pathways and preempt competitive bidding. The technology is integrating diligence workflows across distributed investment teams, reducing travel-dependent fieldwork for cross-border transactions.
Japan's FSA stewardship code revisions are mandating institutional investors disclose voting policies and engagement records, elevating ESG integration from marketing differentiation to regulatory compliance. Asset owners are redirecting mandates toward GPs with documented operational carbon accounting and board diversity metrics. Private equity sponsors with Japanese LP relationships are responding by embedding sustainability-linked ratchets into portfolio company capital structures.
LP direct investment programs are displacing traditional fund commitments among Asia-Pacific sovereign wealth funds, compressing fee load tolerance and accelerating separately managed account negotiations. Temasek and GIC are building in-house private equity capabilities to lead transactions without external GP economics. This behavior concentrates capital among top-quartile sponsors while elevating operational track record requirements for first-time regional funds.
Asia-Pacific Private Equity Market Segmentation
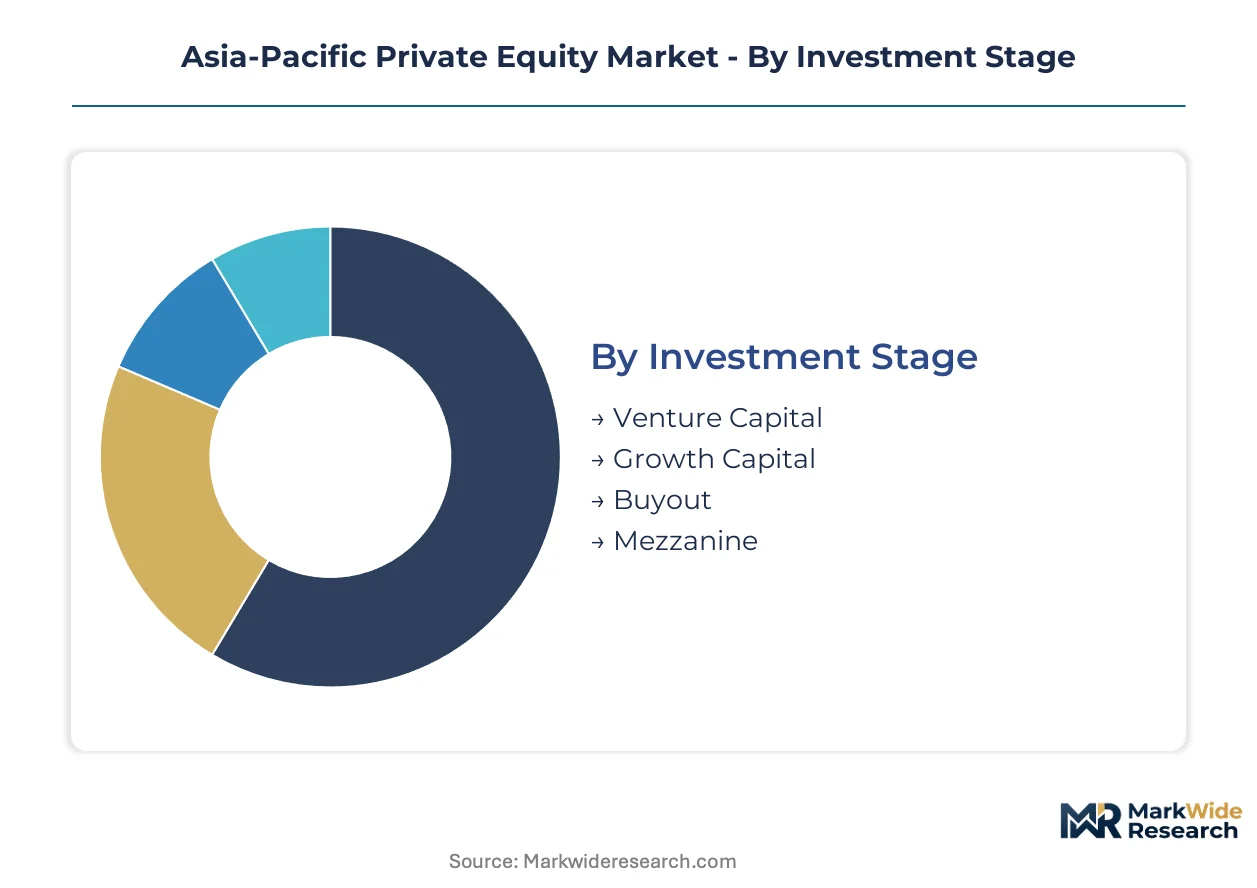
Investment stage classification determines risk-return profiles and LP commitment structures across Asia-Pacific private equity. Investor type and fund structure choices reshape fee economics and governance rights in a region where sovereign capital increasingly dominates first-close positions.
Investment Stage:
SEBI AIF Category I regulations govern venture capital structures in India, while Japan's FSA oversight applies to growth capital vehicles marketed to domestic institutions. Australia's ASIC licensing framework creates additional compliance layers for buyout funds accessing superannuation capital.
- Venture Capital:Early-stage equity deployed into technology startups with pre-revenue or Series A-B traction. Demand concentrates in Bengaluru and Singapore fintech clusters, where SEBI's AIF pass-through tax treatment accelerates domestic LP participation. SEBI Category I structures require onshore GP presence, elevating compliance costs for foreign sponsors.
- Growth Capital:Expansion financing for revenue-positive enterprises seeking scale without full control transfer. Southeast Asian technology platforms in Indonesia and Vietnam absorb the majority of regional deployment, driven by family business succession liquidity needs and conglomerate spin-out opportunities.
- Buyout:Control transactions employing leveraged capital structures and operational improvement playbooks. Japan's negative real rate environment constrains domestic JPY-denominated commitments, forcing GPs to source offshore dollar pools for transaction scale.
- Mezzanine:Subordinated debt with equity participation rights, filling capital structure gaps between senior secured and common equity. Australian mid-market industrial buyouts utilize these instruments most frequently.
Buyout sits at the top of the volume ranking, with growth capital climbing the fastest.
Investor Type:
Fee tolerance and governance requirements diverge sharply across LP categories, with direct co-investment mandates displacing traditional fund commitments among the largest capital pools.
- Pension Funds:Australia's A$3.5 trillion superannuation sector anchors regional anchor LP demand, with ASIC prudential standards shaping due diligence intensity and ESG integration mandates.
- Sovereign Wealth Funds:Direct transaction capabilities and separately managed account structures bypass traditional fund economics entirely. Singapore's Temasek and GIC lead this behavioral shift.
- Family Offices:Concentrated wealth vehicles with flexible liquidity horizons and concentrated sector theses. Greater China technology allocations dominate their regional exposure.
- Institutional Investors:Insurance companies and endowments with liability-matching requirements and alternative asset allocation targets. Japanese life insurers face FSA stewardship code pressure on voting policy disclosure.
Sovereign wealth funds command the deepest capital reserves, with family offices expanding regional commitments most aggressively.
Fund Structure:
Structural choices determine fee load distribution, liquidity terms, and cross-border marketing permissions across Singapore's VCC framework and competing domiciles.
- Closed-End Funds:Ten-to-twelve-year lockups with committed capital drawdowns and carried interest waterfalls tied to hurdle rates. Standard for buyout and special situations strategies.
- Open-End Funds:Evergreen structures with periodic liquidity windows and NAV-based subscriptions. Rare in control-oriented strategies due to valuation complexity.
- Fund of Funds:Diversified exposure across multiple underlying GPs with layered fee structures. Losing share to direct co-investment programs among sophisticated LPs.
- Co-Investment Funds:Sidecar vehicles enabling LP participation in specific transactions alongside flagship funds. Singapore's VCC umbrella structure facilitates sub-fund segregation for these arrangements.
Closed-end structures capture the majority of committed capital, with co-investment vehicles gaining share fastest among top-quartile sponsors.
Market Segment:
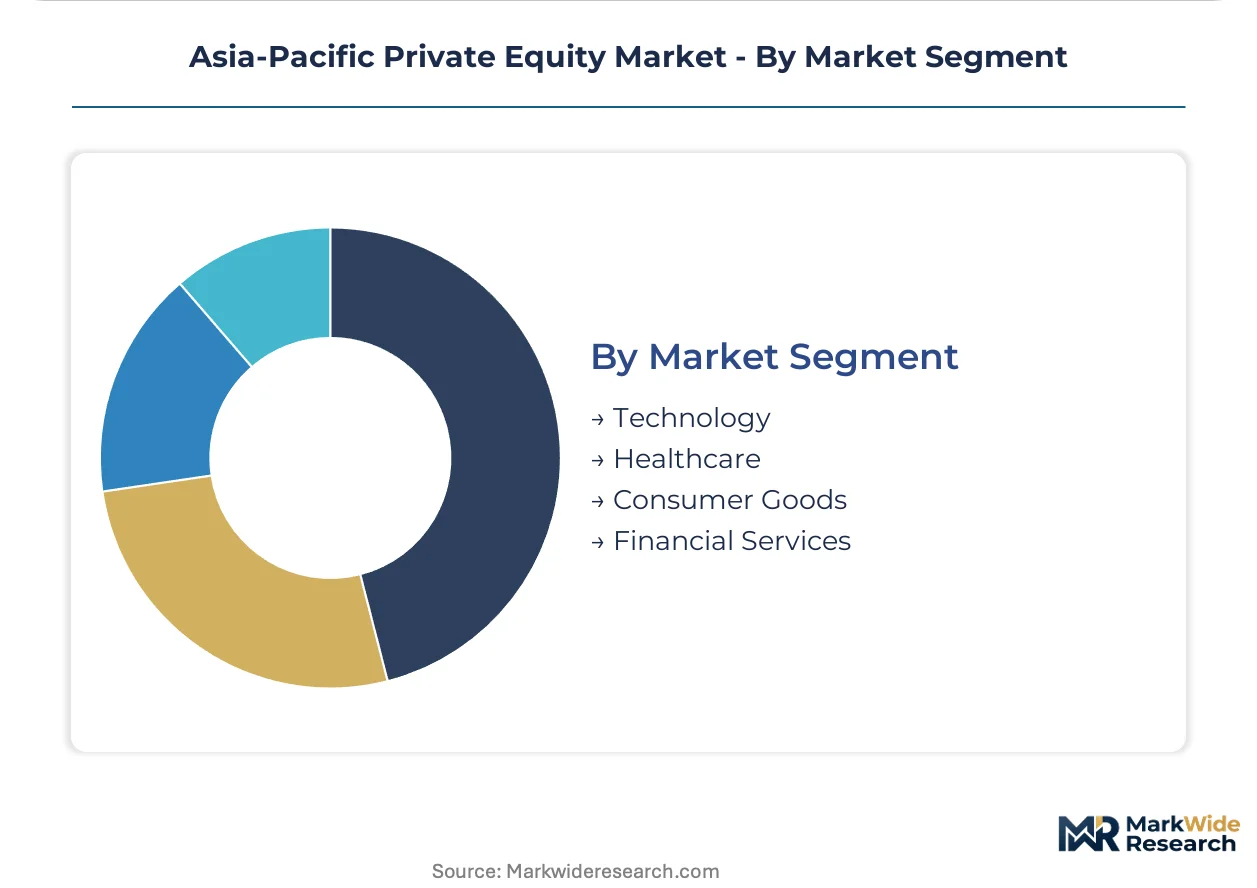
Sector concentration reflects demographic tailwinds, regulatory arbitrage opportunities, and technology adoption curves specific to regional economies.
- Technology:Software, fintech, and enterprise SaaS platforms across Greater China and Southeast Asia. SAMR antitrust reviews in China compress IRR assumptions and extend hold periods.
- Healthcare:Pharmaceutical services, medical devices, and provider platforms. India's CDSCO regulatory pathway shapes transaction timelines for control acquisitions.
- Consumer Goods:Premiumization plays and omnichannel retail infrastructure. Domestic consumption growth in Indonesia and Vietnam drives sponsor interest.
- Financial Services:Non-bank lending, insurance distribution, and wealth management platforms. RBI and SEBI licensing requirements determine scalability assumptions.
Technology sits at the top of the volume ranking, with healthcare climbing the fastest on aging demographics and insurance penetration expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fund domiciliation costs and regulatory treatment divergence are redirecting capital formation toward Singapore and away from higher-compliance jurisdictions. SEBI's AIF regime and Japan's FSA stewardship code revisions create competing anchors for institutional capital pools across the region.
Singapore
The Monetary Authority of Singapore's VCC framework enables umbrella sub-fund segregation that reduces structuring costs for cross-border vehicles. Temasek Holdings and GIC Private Limited anchor domestic sovereign wealth deployment through direct co-investment mandates that bypass traditional fund economics. The city-state's fund administration cluster concentrates legal and compliance infrastructure for regional GPs marketing to Japanese institutional investors.
Japan
Negative real interest rates constrain JPY-denominated LP commitment growth from domestic life insurers and pension funds. The FSA stewardship code revisions mandate voting policy disclosure and engagement record transparency, elevating ESG integration to regulatory compliance rather than marketing differentiation. Tokyo's fund management district hosts operational improvement specialists importing Western buyout playbooks for mid-market industrial transactions.
India
Domestic insurance and pension capital is deepening alternative asset allocations through SEBI's Category II AIF structures with pass-through tax treatment. The regulator's onshore GP presence requirement elevates compliance infrastructure costs for foreign sponsors seeking to market to local institutions. Bengaluru's technology cluster absorbs growth-stage deployment into fintech and enterprise SaaS platforms with domestic consumption tailwinds.
Australia
A$3.5 trillion in superannuation assets is rotating toward private markets under ASIC prudential standards that shape due diligence intensity and ESG integration mandates. The ATO's permanent establishment attribution guidance creates structuring uncertainty for regional fund platforms with Australian underlying assets. Sydney and Melbourne anchor LP advisory relationships for Asia-Pacific-focused flagship fundraises.
Vietnam
Domestic conglomerate spin-outs and family business succession create control equity openings with limited sponsor competition relative to more penetrated Southeast Asian markets. The absence of developed local fund regulation channels capital through Singapore-domiciled vehicles with Vietnamese investment mandates. Ho Chi Minh City's industrial zones attract operational improvement specialists targeting manufacturing platform consolidation.
Asia-Pacific Private Equity Market Competitive Environment
Established sponsors occupy the buyout and growth capital tiers; emerging entrants pursue sector-specialized mandates and direct co-investment structures. The market concentrates capital among top-quartile performers with documented operational track records, while first-time regional funds face elevated barriers to sovereign wealth anchor commitments. Three archetypes dominate: sovereign wealth direct investors bypassing external GP economics, multi-strategy platforms spanning venture through buyout stages, and operational improvement specialists importing Western playbooks. Competitive dynamics center on fee compression through SMA negotiations and talent acquisition for in-house value creation capabilities.
Among Greater China-focused growth capital specialists, Hillhouse Capital Group exemplifies concentrated sector bets in technology platforms. Singapore-based Temasek Holdings anchors the sovereign wealth direct investment archetype through co-investment structures that displace traditional fund commitments. PAG occupies a position across buyout and special situations in Japan, representing the operational improvement playbook model imported from Western markets. These three entities collectively illustrate the capital formation shift toward direct mandates and away from layered fund-of-funds fee structures.
| Leading Market Players |
|---|
| Hillhouse Capital Group |
| Temasek Holdings |
| PAG |
| MBK Partners |
| GIC Private Limited |
| CDH Investments |
| Affinity Equity Partners |
| Navis Capital Partners |
| Everstone Capital |
| Others |
Value Chain & Pricing Dynamics
Artificial intelligence-driven deal sourcing platforms are compressing due diligence timelines and reducing fieldwork-dependent costs for cross-border transactions, simultaneously concentrating operational capabilities among sponsors with proprietary technology stacks and reshaping fee economics across fund formation layers.
Pricing Analysis
Carried interest waterfalls in closed-end funds typically command 20 percent rates above 8 percent hurdle thresholds, with management fees stratifying across 1.5-2.0 percent for flagship vehicles and 0.5-1.0 percent for separately managed accounts. Singapore's VCC framework reduces domiciliation costs by enabling umbrella sub-fund segregation, creating pricing pressure on traditional offshore structures. Sovereign wealth funds exhibit lowest price sensitivity through direct co-investment mandates that bypass layered fee loads entirely, while first-time regional funds face highest sensitivity as LPs demand fee discounts for unproven track records.
Supply Chain Analysis
SEBI's onshore GP presence requirement for AIF marketing creates qualification gating that channels foreign sponsor capital through Singapore-domiciled vehicles with Indian investment mandates. Fund administration clusters concentrate in Singapore and Hong Kong, drawing from legal, compliance, and custody service inputs. Single-source vulnerability runs through Singapore's fund administration infrastructure for Southeast Asian deployment. Distribution runs through limited partner advisory relationships anchored in Sydney, Tokyo, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific private equity operates as a geographic-arbitrage play between Singapore's low-friction VCC domiciliation and India's higher-compliance AIF regime, with fund formation cost differentials exceeding 30 basis points annually.
For Market Incumbents: Anchor fee resilience through separately managed account capabilities that match sovereign wealth fund direct investment preferences. Build in-house operational improvement teams to reduce reliance on external consultants. Threat intensity runs from Temasek and GIC building direct transaction capabilities that displace external GP economics entirely. Vertical integration into portfolio company value creation functions serves as the critical defensive lever. For New Entrants and Emerging Players: Mid-market industrial buyouts in Vietnam offer concentrated white-space opportunity with limited sponsor competition relative to Indonesia or Thailand. Family business succession liquidity needs in Ho Chi Minh City create proprietary deal flow channels. SEBI Category II AIF structures provide the most penetrable regulatory pathway for accessing Indian domestic institutional capital. Go-to-market execution should prioritize operational improvement playbook specialization over sector diversification. For Investors and Strategic Acquirers: Valuations sit cheapest among first-time regional funds with SEBI-compliant onshore infrastructure but limited sovereign wealth anchor relationships. Long-term viability favors sponsors with documented operational track records across multiple fund cycles. Acquisition target archetype: Japan-focused buyout specialists with Western-imported improvement playbooks and JPY-denominated LP relationships. Inflection signal to watch: FSA stewardship code enforcement intensity on voting policy disclosure.| Strategic Initiative | Industry Significance |
|---|---|
| VCC Domiciliation Migration | Singapore's umbrella structure reduces fund formation costs for cross-border vehicles marketing to Japanese LPs. |
| Direct Co-Investment Program Buildout | Sovereign wealth funds bypass traditional fund economics through SMA mandates that compress fee loads. |
| Operational Improvement Capability In-Housing | PAG's Japan playbook demonstrates value creation through captive consulting teams rather than external advisors. |
| SEBI AIF Category II Compliance Infrastructure | Onshore GP presence requirements channel foreign sponsor capital through regulated Indian structures. |
| Climate Technology Platform Development | Renewable energy infrastructure attracts blended finance from development finance institutions seeking ESG-aligned deployment. |
Study Parameters
Multiple input streams — primary interviews with fund formation attorneys, sovereign wealth investment officers, and SEBI compliance specialists; secondary validation through regulatory filings and fund documentation; and proprietary transaction databases — were reconciled through bottom-up and top-down triangulation. Secondary sources included MAS VCC registration records, SEBI AIF circulars, FSA stewardship code disclosure filings, and Australian Prudential Regulation Authority superannuation allocation surveys.
Historical fundraising velocity was cross-referenced against panel input from LP advisory consultants to construct deployment trajectory assumptions across the projection horizon. Segmentation dimensions modeled encompass investment stage, investor type, fund structure, and market sector, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived through regression analysis of committed capital growth rates against macroeconomic and regulatory predictor variables.
Inputs from MAS registration databases and SEBI AIF disclosure filings were available through the study window; gaps in private fund fee schedule transparency introduce uncertainty bands around fee compression trajectory assumptions. Forecasts reflect documented behavioral shifts among sovereign wealth funds toward direct investment programs. A model refresh is warranted upon material change in FSA stewardship code enforcement intensity or SEBI AIF regulatory amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Machinery Rental and Leasing Market
Investment Analysis and Financial Strategies
Southeast Asia E-Invoicing Market
Investment Analysis and Financial Strategies
Business Analytics in Fintech Market
Investment Analysis and Financial Strategies
Ghana Mobile Money Market
Investment Analysis and Financial Strategies
Clinical Risk Grouping Solutions Market
Investment Analysis and Financial Strategies
Asia Pacific POS Terminal Market
Investment Analysis and Financial Strategies
Indonesia Private Health Insurance Market
Investment Analysis and Financial Strategies
Slovakia POS Terminal Market
Investment Analysis and Financial Strategies
UK Forensic Accounting Market
Investment Analysis and Financial Strategies
Digital Account Opening Market
Investment Analysis and Financial Strategies
Southeast Asia Commercial Banking Market
Investment Analysis and Financial Strategies
Global Boats and Yacht Insurance Market
Investment Analysis and Financial Strategies
UAE POS Terminal Market
Investment Analysis and Financial Strategies
India Car Loan Market
Investment Analysis and Financial Strategies
Japan Mortgage/Loan Brokers Market
Investment Analysis and Financial Strategies
Asia-Pacific Crypto Payment Gateway Market