
 Asia-Pacific Pet Nutraceuticals Market | 2026-2036
Asia-Pacific Pet Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pet Nutraceuticals Market Insights
Australian contract manufacturers is restructuring production lines to accommodate thermolabile probiotic strains for tropical distribution. Mars Incorporated leverages captive R&D facilities in Thailand to develop species-specific formulations for brachycephalic breeds. ADM anchors its regional position through backward integration into marine-derived omega-3 supply chains. Vetoquinol competes primarily through veterinary channel exclusivity across Southeast Asian markets.
Asia-Pacific pet nutraceuticals comprise bioactive compounds including vitamins, minerals, fatty acids, and antioxidants formulated for oral administration to companion animals to support physiological functions beyond basic nutrition. Soft chew matrices require lipid-based encapsulation at temperatures below forty degrees Celsius to preserve viability of heat-sensitive actives. Fatty acids currently occupy the largest margin pool among product types due to sourcing complexity of algae and fish oil precursors. Veterinary offices represent the fastest-growing distribution channel as practitioner endorsement commands price premiums over retail alternatives.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict quarantine-adjacent import rules on animal-derived functional ingredients that filter non-compliant suppliers. Australia's Pesticides and Veterinary Medicines Authority regulates therapeutic claims on pet supplements, creating compliance moats for established registrants. China's National Medical Products Administration aligns pet nutraceutical oversight with human dietary supplement frameworks, elevating manufacturing standards. Stakeholders must monitor evolving veterinary telehealth regulations that could redirect prescription-grade nutraceutical flows through digital platforms.
Market Dynamics
Japan's FSSAI-equivalent nutritional labeling mandates are compressing formulation cycles across the Asia-Pacific pet nutraceuticals landscape, forcing manufacturers to revalidate ingredient dossiers before product registration deadlines.
Growth Catalysts
- Pet Humanization in Chinese Tier-One Cities:Shanghai and Beijing households now treat companion animals as family members, creating veterinarian-formulated supplement demand that commands 40-60% price premiums over mass-market alternatives.
- Marine-Derived Omega-3 Sourcing Complexity:Algae and fish oil precursors require specialized cold-chain infrastructure, rewarding suppliers with backward integration into sustainable aquaculture operations across Thailand and Vietnam.
- Veterinary Telehealth Expansion:Singapore and South Korea's digital health frameworks are enabling remote prescription-grade nutraceutical consultations, redirecting premium product flows through practitioner-endorsed channels.
Market Restraints
- Thermolabile Probiotic Viability:Soft chew matrices require lipid-based encapsulation below 40°C, constraining production throughput in tropical climates without specialized equipment.
- Import Quarantine Adjacency Rules:Japan's Ministry of Agriculture, Forestry and Fisheries filters non-compliant animal-derived functional ingredient suppliers through extended documentation requirements.
- Therapeutic Claims Regulation:Australia's Pesticides and Veterinary Medicines Authority creates compliance moats that delay market entry for unregistered therapeutic supplement formulations.
Strategic Opportunities
- Brachycephalic Breed Specialization:Thailand-based captive R&D facilities are developing species-specific respiratory and digestive support formulations for pugs, bulldogs, and Persian cats.
- Veterinary Channel Exclusivity:Southeast Asian markets reward practitioners with exclusive distribution rights for prescription-strength joint and cognitive health supplements.
- China NMPA Alignment:National Medical Products Administration oversight elevation creates manufacturing standard parity with human dietary supplements, enabling cross-border quality certification leverage.
Industry Challenges
- Cold-Chain Infrastructure Gap:Thermolabile strain distribution across Indonesia and Philippines requires capex-intensive refrigerated logistics networks that mid-scale manufacturers struggle to finance.
- Formulation Scientist Scarcity:Cross-functional expertise spanning veterinary pharmacology, food science, and encapsulation engineering concentrates in Japanese and Australian research clusters, creating recruitment bottlenecks elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pet Nutraceuticals Market |
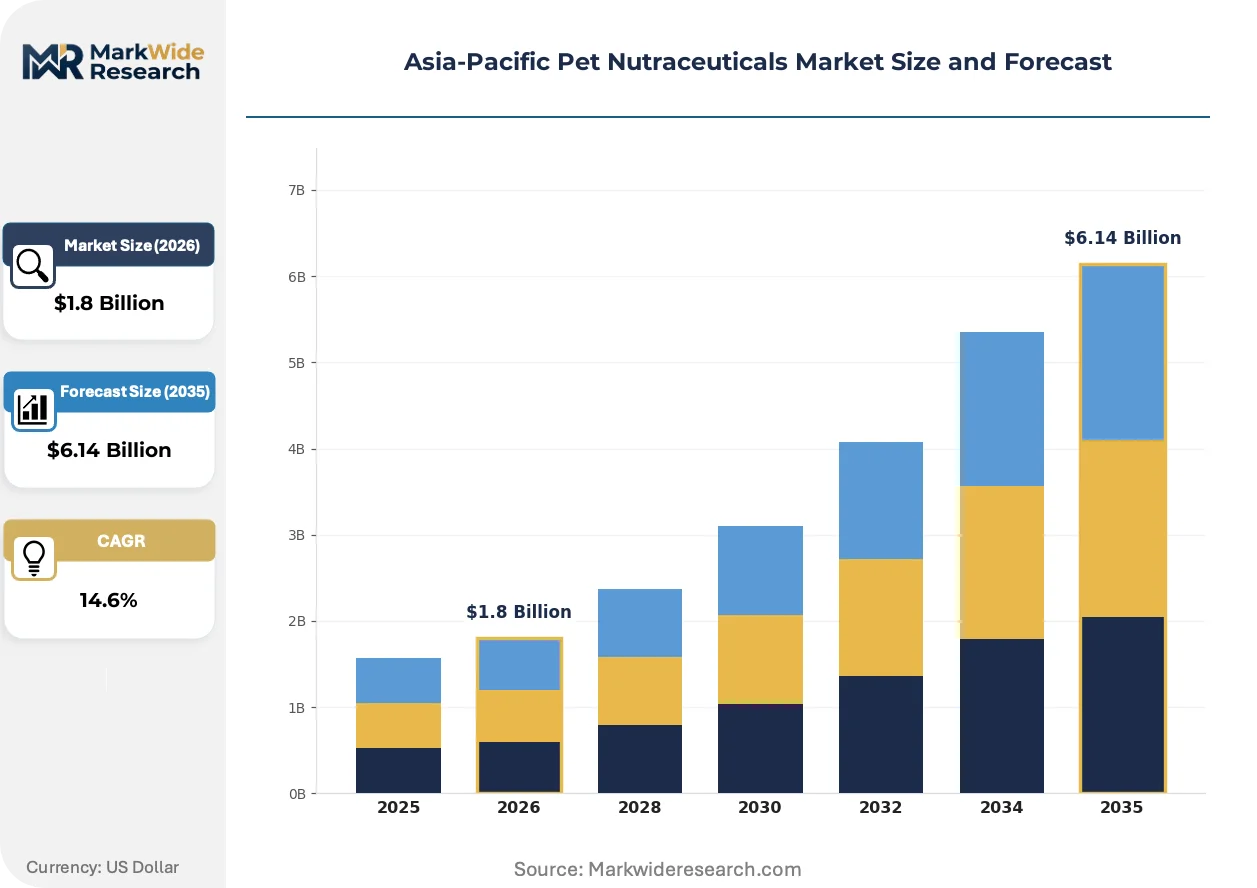
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Fatty Acids, Antioxidants End User: Pet Owners, Veterinary Clinics, Distributors, Online Retailers Formulation: Soft Chews, Powders, Capsules, Liquid Distribution Channel: Specialty Stores, Supermarkets, E-commerce, Veterinary Offices |
| Companies Covered | Mars Incorporated, ADM, Vetoquinol, EBOS Group Limited, Alltech, Nestle (Purina), Colgate-Palmolive Company (Hill's Pet Nutrition Inc.), Virbac Corporation, General Mills Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pet Nutraceuticals Market Trends and Innovations
Lipid-based microencapsulation protocols are compressing the viability window for heat-sensitive actives, while regulatory alignment between human and pet supplement frameworks elevates manufacturing complexity across the region.
Microencapsulation technology employing phospholipid bilayers is rewriting the shelf-stability economics of probiotic pet supplements. Japanese contract manufacturers are retrofitting production lines to accommodate these temperature-sensitive processes, enabling tropical distribution without cold-chain dependency. The structural consequence is a geographic expansion of viable manufacturing locations beyond temperate climate zones.
China's National Medical Products Administration has aligned pet nutraceutical oversight with human dietary supplement frameworks through GB standard harmonization. This regulatory convergence forces dual-registration compliance costs onto manufacturers while creating quality certification leverage for exporters. Domestic Chinese producers are responding by upgrading GMP facilities to pharmaceutical-grade specifications ahead of enforcement deadlines.
Veterinary telehealth platforms in South Korea and Singapore are disintermediating traditional retail distribution for prescription-grade supplements. Practitioner endorsement through digital channels commands price premiums that mass-market e-commerce cannot replicate. This channel shift concentrates most visibly in cognitive health and senior mobility product categories where diagnostic confidence drives purchase decisions.
Asia-Pacific Pet Nutraceuticals Market Segmentation
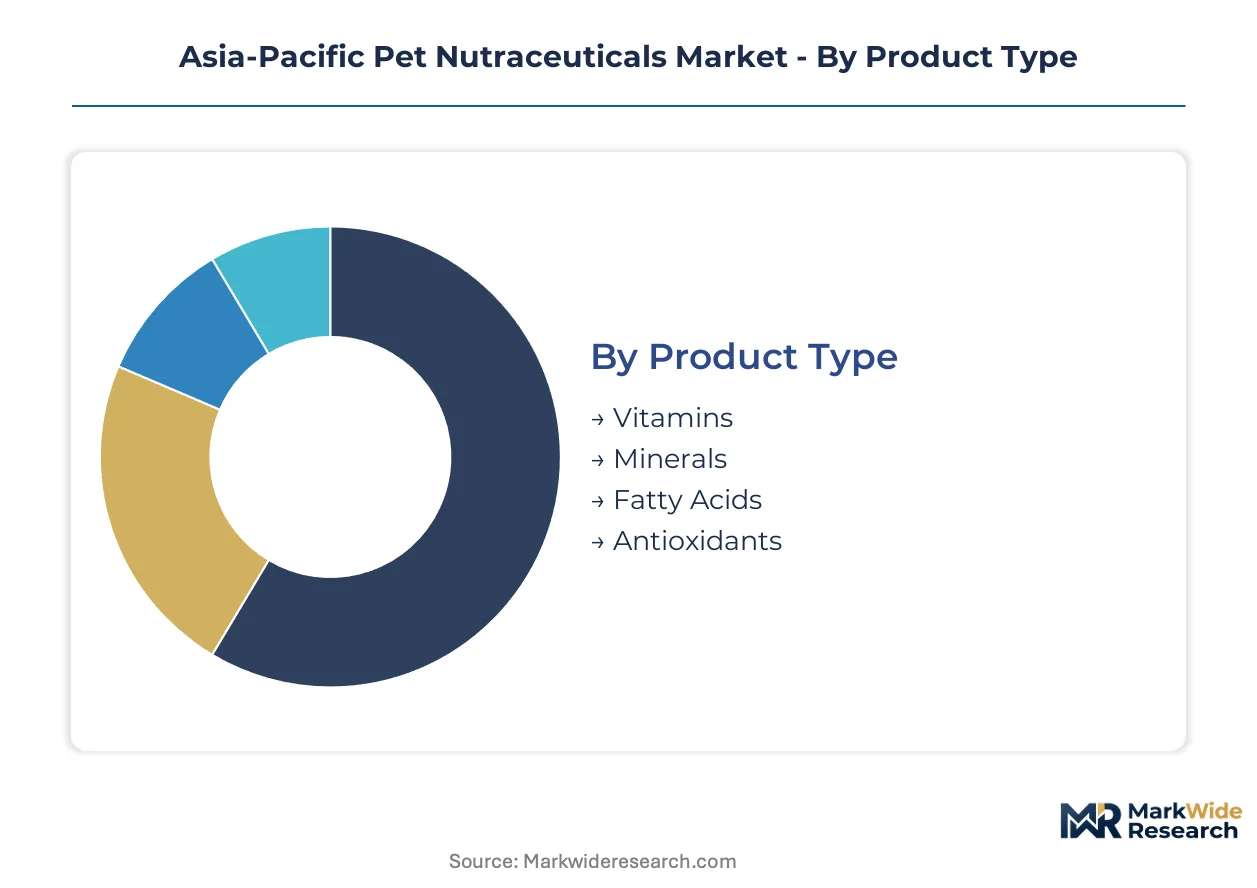
Pet nutraceutical manufacturers configure production lines around formulation constraints and channel access rather than uniform scale economics. Segment boundaries shift as veterinary telehealth platforms redirect prescription-grade flows and cold-chain requirements filter viable geographies for thermolabile products.
Product Type:
Upgrade cycles in companion animal nutrition follow humanization trends that reposition basic supplements toward functional health solutions.
- Fatty Acids:Marine-derived omega-3 formulations from algae and fish oil precursors command the largest margin pool due to sourcing complexity. Thailand and Vietnamese suppliers with backward integration into sustainable aquaculture operations capture premium positioning in China's tier-one cities.
- Antioxidants:Carotenoid and polyphenol blends targeting cellular aging in senior pets concentrate demand among Shanghai and Beijing households seeking veterinarian-formulated solutions. Practitioner endorsement through digital channels supports price premiums over retail alternatives.
- Vitamins:Water-soluble and fat-soluble complexes address deficiency correction in homemade pet diets.
- Minerals:Chelated trace element formulations support bone density and metabolic function in large-breed dogs.
Fatty acids sit at the top of the volume ranking, with antioxidants climbing the fastest.
End User:
Cost tier differentiation separates mass-market accessibility from practitioner-mediated premium positioning.
- Veterinary Clinics:Prescription-grade joint and cognitive health supplements flow through exclusive distribution arrangements across Southeast Asian markets. Singapore and South Korea's telehealth frameworks enable remote consultations that concentrate premium product access through endorsed channels.
- Pet Owners:Direct purchasers in Chinese tier-one cities drive demand for veterinarian-formulated supplements that command substantial price premiums over mass-market alternatives. Humanization trends reposition companion animals as family members.
- Distributors:Wholesale intermediaries manage cold-chain logistics for thermolabile probiotic strains across tropical markets.
- Online Retailers:E-commerce platforms capture volume in standard-grade products where diagnostic confidence is not required.
Veterinary clinics anchor the highest-margin tier, with online retailers expanding most quickly in standard formulations.
Formulation:
Supply concentration in encapsulation technology creates geographic moats around viable production locations.
- Soft Chews:Lipid-based matrices require encapsulation below 40°C to preserve viability of heat-sensitive actives. Australian contract manufacturers are restructuring production lines to accommodate thermolabile probiotic strains for tropical distribution without cold-chain dependency.
- Powders:Dry-blend formats bypass temperature constraints and concentrate manufacturing in mid-scale facilities across Indonesia and Philippines. Lower capex requirements enable broader geographic dispersion.
- Capsules:Hard-shell and soft-gel variants suit precision dosing for therapeutic applications.
- Liquid:Emulsion-based delivery systems address palatability challenges in finicky eaters and senior animals with dental issues.
Soft chews dominate premium positioning, with powders gaining share fastest in cost-sensitive segments.
Distribution Channel:
Channel maturity determines regulatory compliance burden and margin structure simultaneously.
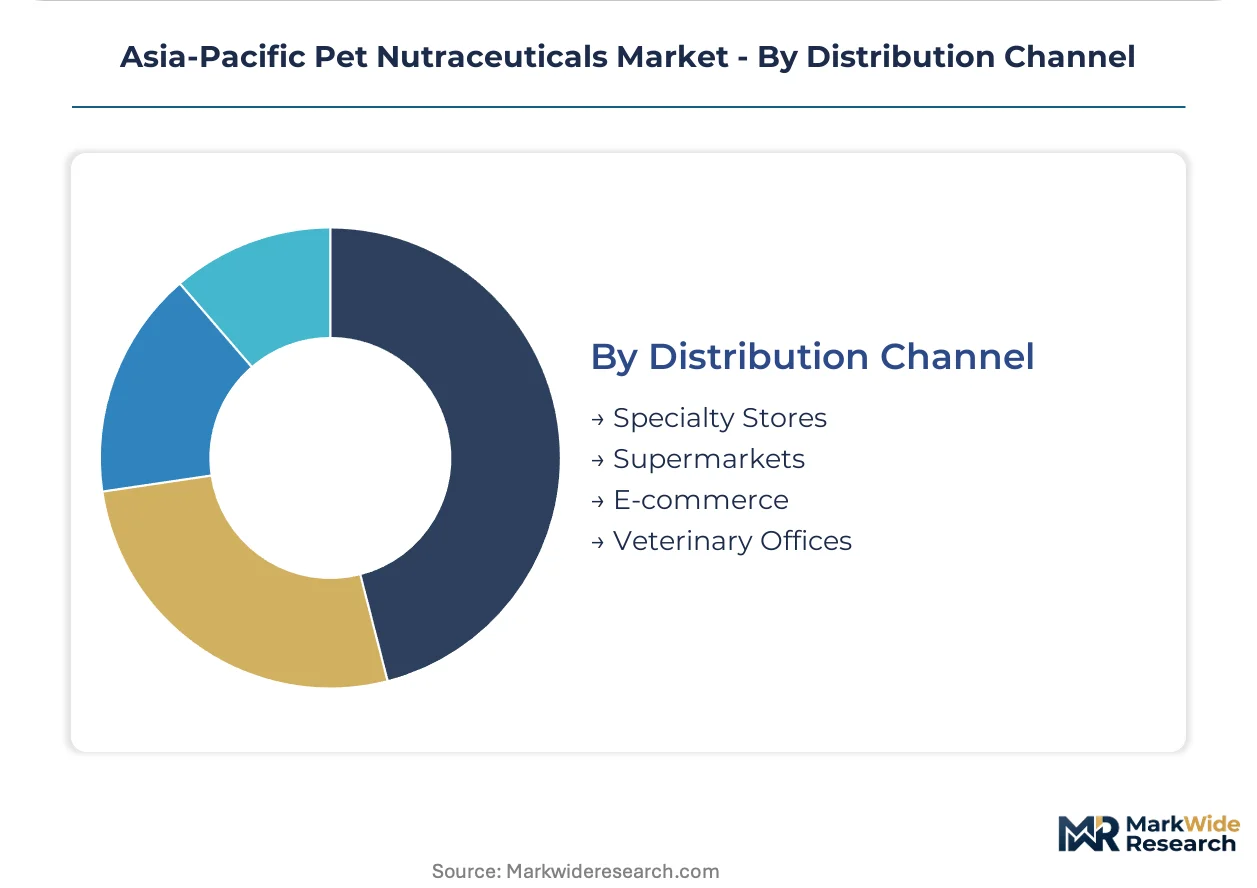
- Veterinary Offices:Practitioner endorsement commands price premiums that mass-market e-commerce cannot replicate. Cognitive health and senior mobility categories concentrate here where diagnostic confidence drives purchase decisions.
- E-commerce:Digital platforms disintermediate traditional retail for standard-grade supplements in South Korea and Singapore. Convenience positioning captures younger pet owner demographics.
- Specialty Stores:Curated assortments of premium and niche formulations serve educated consumers seeking species-specific solutions.
- Supermarkets:Mass-market placement of basic vitamin and mineral supplements reaches price-sensitive households.
Veterinary offices lead in value generation, with e-commerce showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate toward jurisdictions with streamlined compliance pathways for animal-derived functional ingredients. Cost-of-compliance gaps between mature and emerging regulatory environments drive facility investment decisions across the region.
China
Shanghai and Beijing households treat companion animals as family members, generating veterinarian-formulated supplement demand that commands substantial price premiums. NMPA oversight elevation through GB standard harmonization forces pharmaceutical-grade manufacturing upgrades. Yangtze River Delta producers are retrofitting GMP facilities to meet dual-registration compliance requirements ahead of enforcement deadlines.
Japan
Pet humanization trends concentrate in Tokyo and Osaka metropolitan corridors where aging demographics elevate companion animal status. MAFF enforces strict quarantine-adjacent import rules on animal-derived functional ingredients that filter non-compliant suppliers. Kanto-based contract manufacturers are restructuring production lines to accommodate thermolabile probiotic encapsulation below forty degrees Celsius.
Australia
Veterinary channel exclusivity arrangements dominate distribution for prescription-grade joint and cognitive health supplements. APVMA therapeutic claims regulation creates compliance moats that delay market entry for unregistered formulations. Melbourne and Sydney research clusters concentrate cross-functional expertise spanning veterinary pharmacology and encapsulation engineering.
South Korea
Digital health frameworks enable remote prescription-grade nutraceutical consultations that redirect premium product flows through practitioner-endorsed channels. MFDS nutritional labeling mandates compress formulation cycles and force ingredient dossier revalidation. Seoul Capital Area telehealth platforms disintermediate traditional retail for cognitive health and senior mobility categories.
Thailand
Backward integration into sustainable aquaculture operations captures premium positioning for marine-derived omega-3 formulations. Captive R&D facilities develop species-specific respiratory and digestive support for brachycephalic breeds. Bangkok-based manufacturers leverage regional cold-chain infrastructure to distribute thermolabile strains across tropical Southeast Asian markets.
Asia-Pacific Pet Nutraceuticals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue veterinary channel exclusivity and species-specific formulation niches. The market structure reflects a bifurcation between multinational ingredient suppliers with captive supply chains and regional specialists commanding practitioner-mediated distribution. Three archetypes dominate: integrated nutrition conglomerates with backward integration into marine sourcing, veterinary pharmaceutical houses with channel exclusivity arrangements, and contract manufacturers with encapsulation technology specialization. Competitive moves concentrate on regulatory pre-registration of ingredient dossiers and cold-chain infrastructure partnerships for tropical distribution.
Among integrated nutrition conglomerates, Mars Incorporated and ADM represent the backward-integration archetype, anchoring positions through captive supply of algae and fish oil precursors. Vetoquinol exemplifies the veterinary pharmaceutical specialist model, occupying a position defined by practitioner channel exclusivity across Southeast Asian markets. These three entities sit within distinct competitive vectors: manufacturing scale, supply chain control, and distribution access respectively.
| Leading Market Players |
|---|
| Mars Incorporated |
| ADM |
| Vetoquinol |
| EBOS Group Limited |
| Alltech |
| Nestle (Purina) |
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) |
| Virbac Corporation |
| General Mills Inc. |
| Others |
Pricing and Supply Chain Analysis
Veterinary clinic procurement in Southeast Asia concentrates demand for prescription-grade supplements, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects channel access rather than ingredient cost alone.
Pricing Analysis
Distributor margin layers in tropical markets absorb cold-chain infrastructure costs that compress manufacturer netbacks on thermolabile probiotic formulations. Pricing stratifies across premium, standard, and economy tiers based on veterinary endorsement certification and volume scale, with price differentiation widening as China's NMPA elevates manufacturing standards. Pricing pressure stems from mid-scale entrants in Indonesia and Philippines undercutting on powders that bypass encapsulation complexity. Mass-market e-commerce buyers exhibit highest price sensitivity; veterinary-channel purchasers show lowest.
Supply Chain Analysis
Direct-to-veterinary channels handle prescription-strength demand across Thailand, Australia, and South Korea, while retail intermediaries manage standard-grade flows. Marine-derived omega-3 supply draws from Thai and Vietnamese aquaculture operations with backward integration into algae cultivation. Soft chew manufacturing rests on lipid-based encapsulation equipment concentrated in Japanese and Australian facilities. Single-source vulnerability runs through cold-chain logistics networks across Indonesian archipelago distribution. Procurement is shifting toward regional contract manufacturers with phospholipid microencapsulation capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
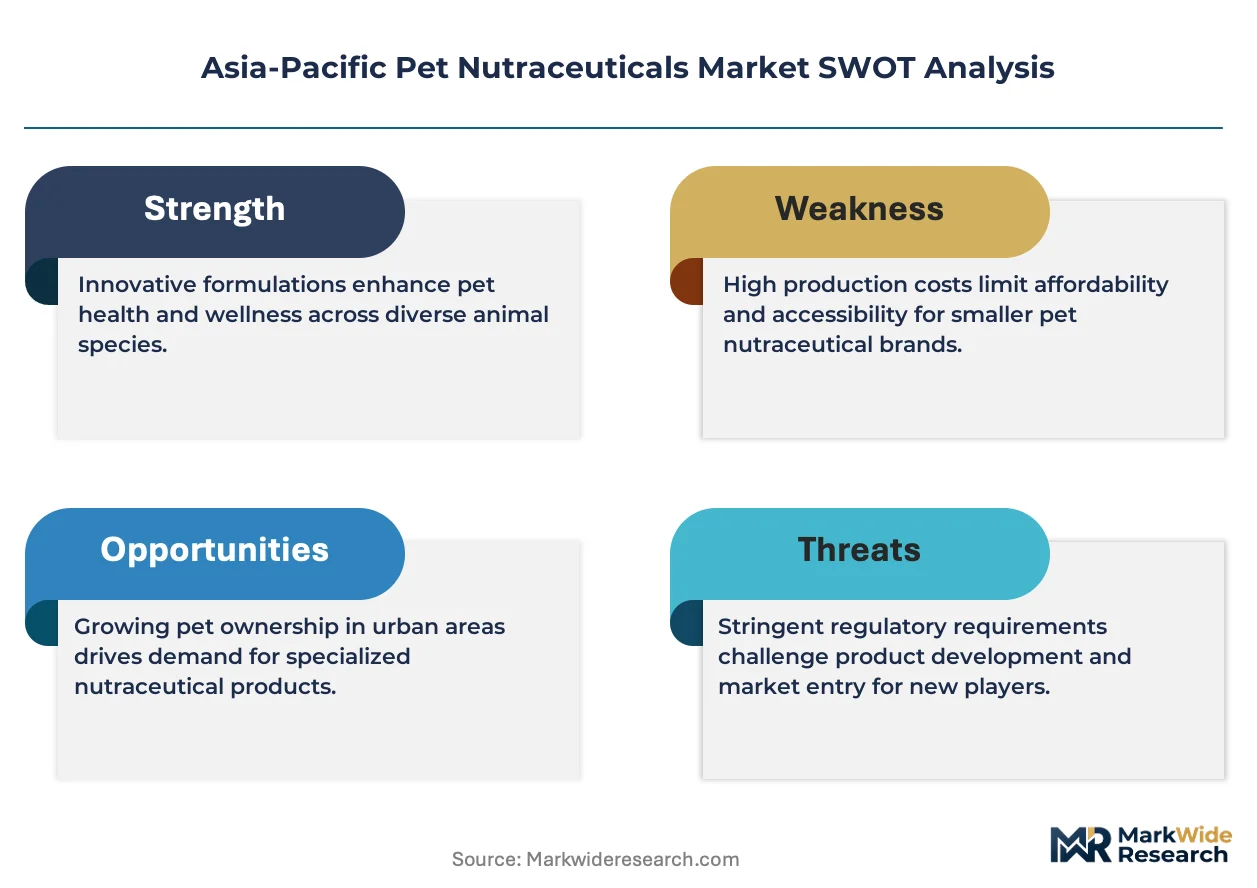
Asia-Pacific pet nutraceuticals operate as a geographic-arbitrage play where compliance cost gaps between Japan's MAFF quarantine rules and Thailand's streamlined import pathways reward facility relocation toward Bangkok-based production clusters.
For Market Incumbents: Acquire captive omega-3 aquaculture assets in Thailand and Vietnam to secure margin pool control against marine sourcing volatility. Expand GMP-certified encapsulation capacity in Australia ahead of NMPA-aligned enforcement deadlines. Channel control through veterinary exclusivity arrangements defends position against direct-to-consumer telehealth disintermediation. For New Entrants and Emerging Players: Lipid-based microencapsulation technology-first wedge opens white-space in Indonesian and Philippine powder markets where cold-chain gaps exclude thermolabile competitors. Target veterinary telehealth partnerships in South Korea and Singapore as the most penetrable channel. Position through species-specific brachycephalic formulations as go-to-market angle. For Investors and Strategic Acquirers: Integrated nutrition conglomerates with captive supply chains are the most active acquirer in this space, consolidating backward into marine sourcing and forward into veterinary distribution. Long-term viability frames around regulatory harmonization elevating manufacturing barriers. Watch NMPA enforcement timeline as inflection signal for quality-certification leverage plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marine Sourcing | Captive algae and fish oil supply secures largest margin pool against precursor volatility. |
| Veterinary Channel Exclusivity Arrangements | Practitioner endorsement commands price premiums that mass-market e-commerce cannot replicate. |
| Phospholipid Microencapsulation Technology Deployment | Temperature-sensitive processing enables tropical distribution without cold-chain dependency. |
| GMP Facility Upgrade to Pharmaceutical Grade | China's NMPA alignment creates quality certification leverage for cross-border exporters. |
| Species-Specific Formulation Development | Brachycephalic breed specialization captures premium positioning in underserved respiratory segments. |
Research Methodology
Multiple input streams — regulatory filing databases, customs trade records, veterinary procurement systems — were reconciled through bottom-up and top-down triangulation. Primary interviews with formulation scientists, veterinary clinic procurement managers, contract manufacturing executives, and aquaculture supply specialists informed demand-side validation. Secondary sources included MAFF import documentation, APVMA therapeutic claim registers, NMPA GB standard publications, and MFDS labeling mandate records across the analysis window.
Data-stream reconciliation applied segmentation modeling across product type, end-user tier, formulation technology, and distribution channel dimensions throughout the forecast period. CAGRs were derived from growth-rate reconciliation between macroeconomic drivers and segment-specific adoption curves. Industry-specific forecast inputs incorporated veterinary telehealth penetration rates and cold-chain infrastructure development timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement timing, marine raw material price volatility, and telehealth platform reimbursement policy shifts. Forecasts reflect documented assumptions around NMPA implementation pacing and MAFF quarantine rule stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Cognitive Health Ingredients Market