
 Asia Pacific Pet Insurance Market | 2026-2036
Asia Pacific Pet Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pet Insurance Market Outlook
Market Context
Buyer concentration among millennial pet owners across Australian metropolitan areas is expanding as younger demographics replace aging customer cohorts. Sompo Japan Insurance Inc. leverages its domestic agency network to sustain premium volume in Tokyo and Osaka prefectures. Allianz Care competes through direct-to-consumer digital channels that reduce acquisition costs across Southeast Asian markets. Anicom Holdings Inc anchors its position through exclusive partnerships with veterinary clinic chains, controlling a dense referral network that limits competitor access.
Technical Definition and Segments
Asia Pacific pet insurance constitutes risk-transfer contracts covering veterinary treatment costs, mortality benefits, and third-party liability for companion animals, with policies typically specifying annual benefit limits, co-payment ratios between ten and thirty percent, and waiting periods for pre-existing condition exclusions. The primary commercial purpose centers on reducing financial volatility for pet owners facing escalating specialist veterinary fees across the region's urban centers. Health coverage policies command the deepest margin pools due to recurring premium structures and predictable claims patterns, while wellness plans represent the fastest-growing product type as preventive care awareness spreads among first-time adopters in South Korea and Singapore. Accident coverage remains mature in Japan, where decades of market development have saturated the core risk segment.
Regulatory Environment
Japan's Financial Services Agency, Australia's Prudential Regulation Authority, and India's Insurance Regulatory and Development Authority each enforce solvency and disclosure standards that shape product design and distribution eligibility across their respective jurisdictions. These frameworks elevate capital requirements and mandate transparent claims handling, which filters out undercapitalized entrants and reinforces incumbent stability. Stakeholders must monitor evolving digital insurance licensing pathways as regulators in Thailand and Indonesia draft bespoke rules for pet-specific coverage distribution.
Market Dynamics
Veterinary cost inflation across Australian and Japanese metropolitan centers is compressing policy affordability thresholds while simultaneously elevating perceived value among risk-averse pet owners. This structural tension between rising claims exposure and premium accessibility is forcing product redesign across the region's regulated markets.
Growth Catalysts
- APRA Disclosure Standards:Australia's prudential regulator mandates granular claims-handling transparency, elevating consumer trust indices and reducing policy comparison friction among digitally native buyers.
- Urban Millennial Concentration:Dense pet ownership clusters in Tokyo and Sydney generate network effects that accelerate word-of-mouth referral velocity and lower customer acquisition costs for direct channels.
- Specialist Veterinary Infrastructure:Advanced diagnostic imaging and oncology capabilities in Japanese university hospitals expand addressable claim severity, justifying higher premium tiers.
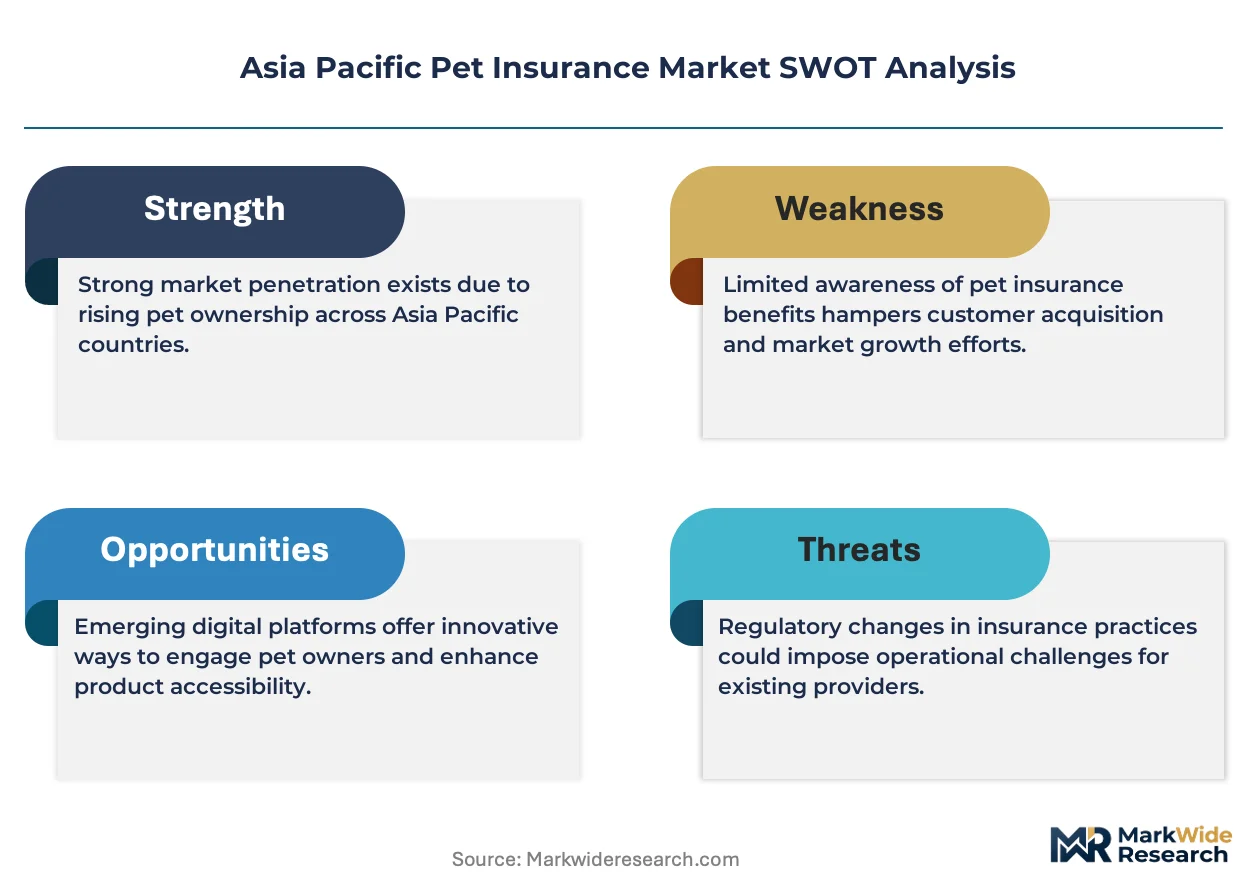
Market Restraints
- Veterinary Labor Cost Escalation:Specialist veterinarian wage inflation in Australian capital cities compresses loss ratios and forces co-payment ratio adjustments that dampen policy attractiveness.
- Pre-Existing Condition Asymmetry:Information gaps between policyholders and underwriters regarding hereditary breed conditions elevate adverse selection risk in high-penetration Japanese prefectures.
- Regulatory Fragmentation:Divergent licensing requirements across Thailand, Indonesia, and the Philippines prevent standardized product portability and elevate compliance overhead for regional carriers.
Strategic Opportunities
- Singapore Wellness Plan White Space:Preventive care riders remain underdeveloped relative to Japanese benchmarks, creating first-mover advantage for bundled vaccination and dental coverage products.
- Veterinary Telehealth Convergence:Integration of remote diagnostic platforms with policy administration systems enables real-time claims pre-authorization and reduces fraud exposure.
- South Korea Digital-Native Distribution:KakaoTalk and LINE super-app ecosystems offer embedded insurance pathways that bypass traditional agency cost structures entirely.
Industry Challenges
- Actuarial Talent Scarcity:Limited supply of professionals with concurrent veterinary medicine and insurance pricing expertise constrains product innovation velocity in emerging Southeast Asian markets.
- Legacy System Integration:Core policy administration platforms at incumbent Japanese carriers resist API connectivity with modern veterinary practice management software, delaying real-time claims automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pet Insurance Market |
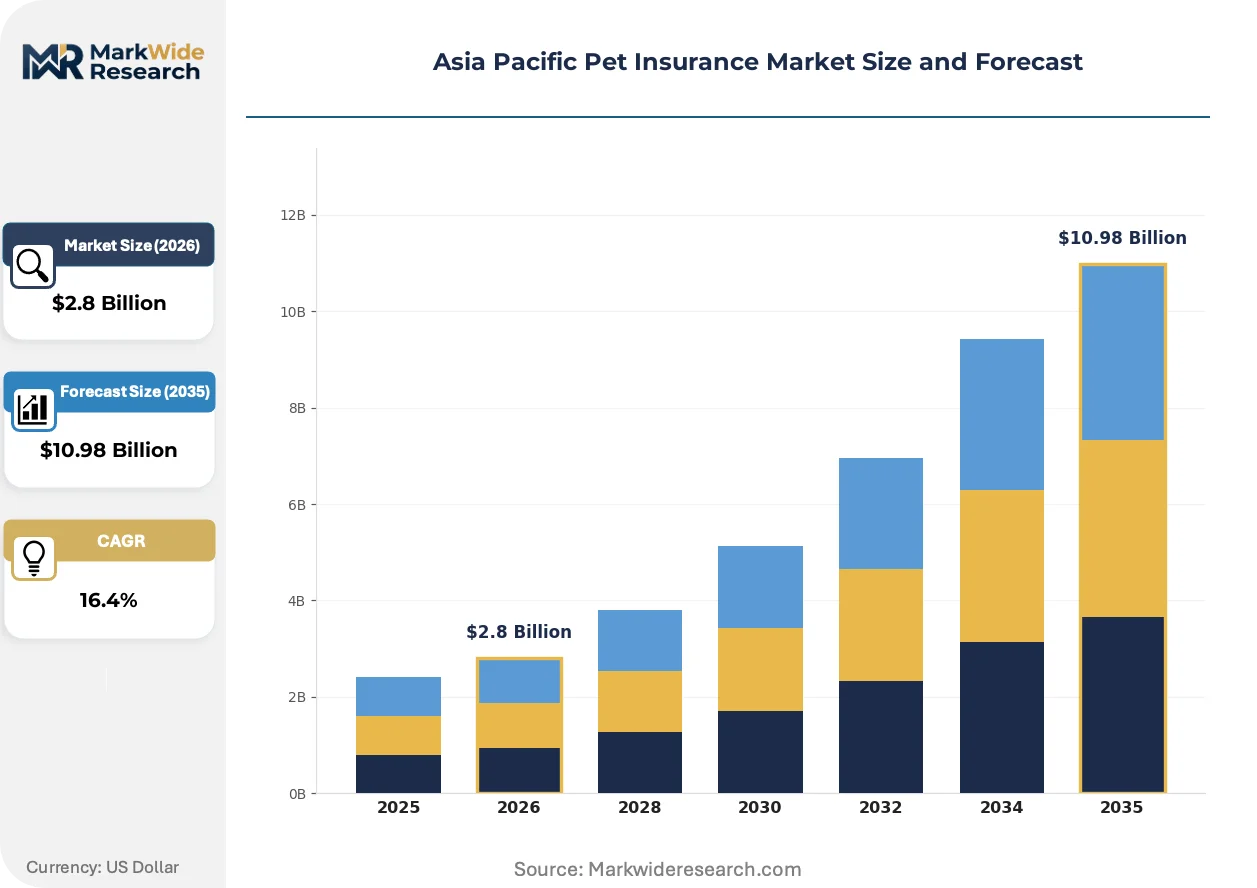
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accident Coverage, Health Coverage, Wellness Plans, Multi-Pet Policies Customer Type: Pet Owners, Veterinary Clinics, Pet Specialty Retailers, Online Platforms Coverage Type: Comprehensive, Basic, Third-Party Liability, Preventative Care Plan Duration: Annual, Multi-Year, Monthly, Lifetime |
| Companies Covered | Sompo Japan Insurance Inc., Allianz Care, Anicom Holdings Inc, The New India Assurance Company, PetSure, ipet Insurance Co., Ltd., Mitsui Sumitomo Insurance, Medibank Private Limited, Rakuten General Insurance, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pet Insurance Market Strategic Shifts
Embedded distribution partnerships and AI-driven underwriting engines are rewriting competitive economics across the Asia Pacific pet insurance landscape. These shifts compress policy issuance timelines while elevating precision in risk segmentation.
Telematics-enabled wearable devices for companion animals are rewriting claims verification protocols. Collar-mounted activity monitors and GPS trackers now feed behavioral data directly to underwriting algorithms. Australian direct-to-consumer carriers deploy these streams to validate wellness plan compliance and adjust renewal pricing dynamically.
Japan's Financial Services Agency has tightened solvency reporting intervals for pet-specific underwriters, forcing more frequent capital adequacy disclosures. This regulatory compression elevates operational overhead for mono-line specialists while reinforcing multi-line incumbents with existing compliance infrastructure. Tokyo-based carriers respond by consolidating back-office functions across life and pet divisions.
Subscription-based preventive care bundling is displacing traditional indemnity structures among first-time adopters in Seoul and Singapore. Younger policyholders prioritize predictable monthly outlays over catastrophic coverage alone. This preference rotation favors carriers with established veterinary clinic partnerships that can deliver contracted wellness services at fixed cost.
Asia Pacific Pet Insurance Market Segmentation
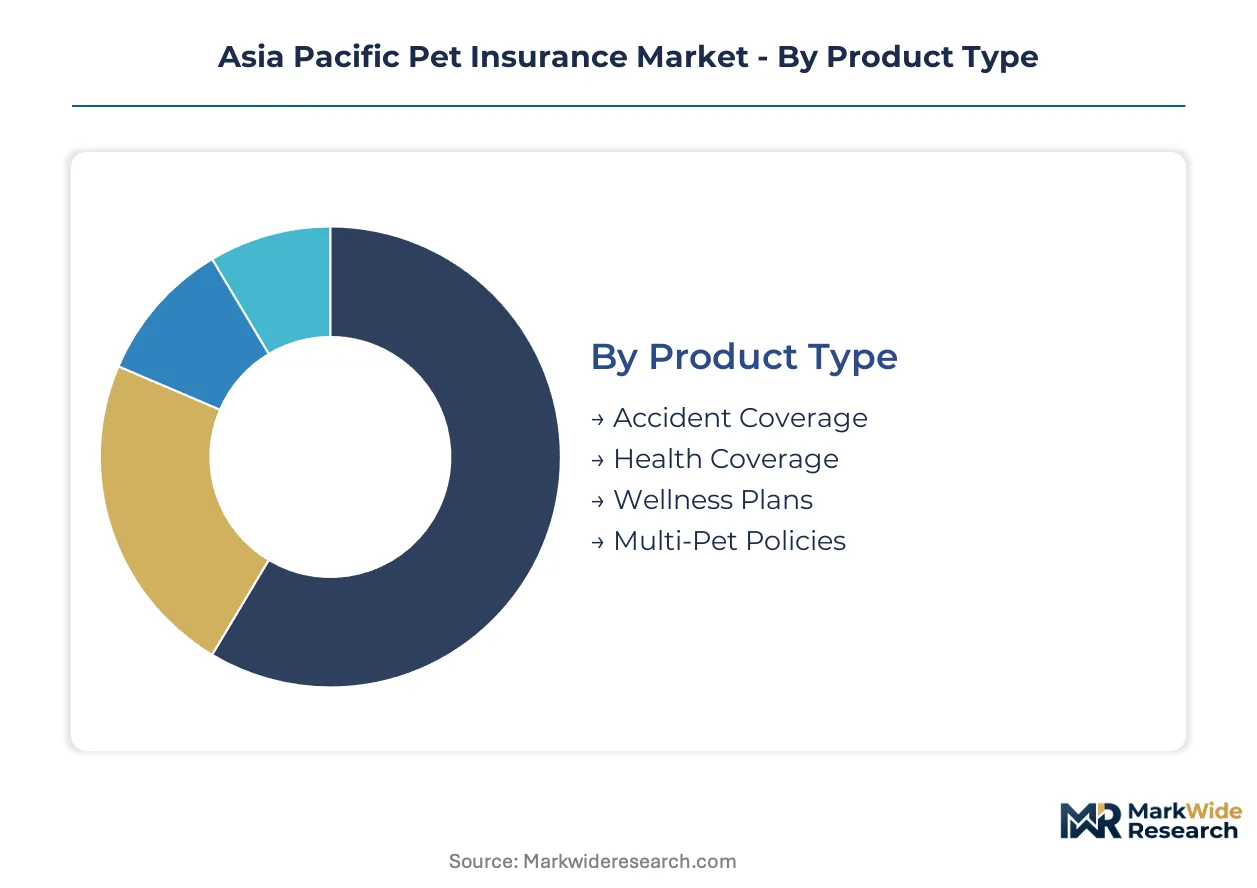
Segmentation in Asia Pacific pet insurance reveals divergent margin profiles across product architectures and distribution channels. Insurers calibrate capital allocation between mature indemnity lines and emerging wellness bundles as veterinary cost inflation reshapes policy economics.
Product Type:
Upgrade cycles accelerate as pet owners shift from single-risk accident policies toward comprehensive health portfolios that absorb specialist treatment costs.
- Accident Coverage:Indemnity contracts covering trauma, fractures, and acute injuries with fixed benefit ceilings and minimal underwriting friction. Demand concentrates in Japanese prefectures with decades of market maturity, though premium growth stalls as policyholders migrate toward broader protection.
- Health Coverage:Comprehensive veterinary treatment reimbursement spanning diagnostics, surgery, and chronic disease management with recurring premium structures. Australian metropolitan clusters drive volume as specialist fee inflation elevates perceived value among risk-averse millennial owners.
- Wellness Plans:Preventive care bundles covering vaccinations, dental cleaning, and routine examinations through fixed monthly subscriptions. Seoul and Singapore first-time adopters favor predictable outlays over catastrophic coverage alone.
- Multi-Pet Policies:Household-level contracts extending discounted rates across multiple companion animals with consolidated administration. Dense urban ownership clusters in Tokyo and Sydney generate network effects that lower per-pet acquisition costs.
Health Coverage sits at the top of the volume ranking, with Wellness Plans climbing the fastest.
Customer Type:
Cost tier differentiation separates mass-market direct channels from high-touch intermediary relationships that command premium placement fees.
- Pet Owners:Individual policyholders purchasing coverage through direct digital platforms, agency networks, or employer-sponsored voluntary benefits. Australian millennial cohorts in Sydney and Melbourne dominate online acquisition metrics.
- Veterinary Clinics:Point-of-sale distribution partnerships where clinic staff recommend carrier products during consultations. Anicom Holdings controls dense referral networks across Japanese university hospitals that limit competitor access.
- Pet Specialty Retailers:Big-box pet store chains embedding insurance offers within retail transactions. Southeast Asian markets show nascent penetration as retailers build veterinary service adjacencies.
- Online Platforms:Pure-play digital aggregators and insurtech portals reducing friction through automated quote comparison. South Korean KakaoTalk super-app ecosystems enable embedded distribution bypassing traditional cost structures.
Pet Owners generate the deepest premium pools, though Online Platforms are expanding most quickly.
Coverage Type:
Application-specific design separates catastrophic indemnity from routine care contracts with divergent claims predictability.
- Comprehensive:Broad-spectrum protection combining accident, illness, and wellness benefits with annual limit structures. Japanese FSA disclosure standards elevate consumer trust indices for complex bundled products.
- Basic:Stripped-down coverage limiting reimbursement to essential treatments with higher co-payment ratios. Price-sensitive first-time adopters in emerging Southeast Asian markets favor lower entry premiums.
- Third-Party Liability:Legal protection against injury or property damage caused by insured animals. Australian strata housing regulations in Sydney and Melbourne drive mandatory coverage requirements for certain breeds.
- Preventative Care:Standalone riders covering vaccinations, parasite control, and early disease screening. Singapore veterinary clinics report underdeveloped penetration relative to Japanese wellness benchmarks.
Comprehensive coverage commands the largest installed base, with Preventative Care gaining share fastest.
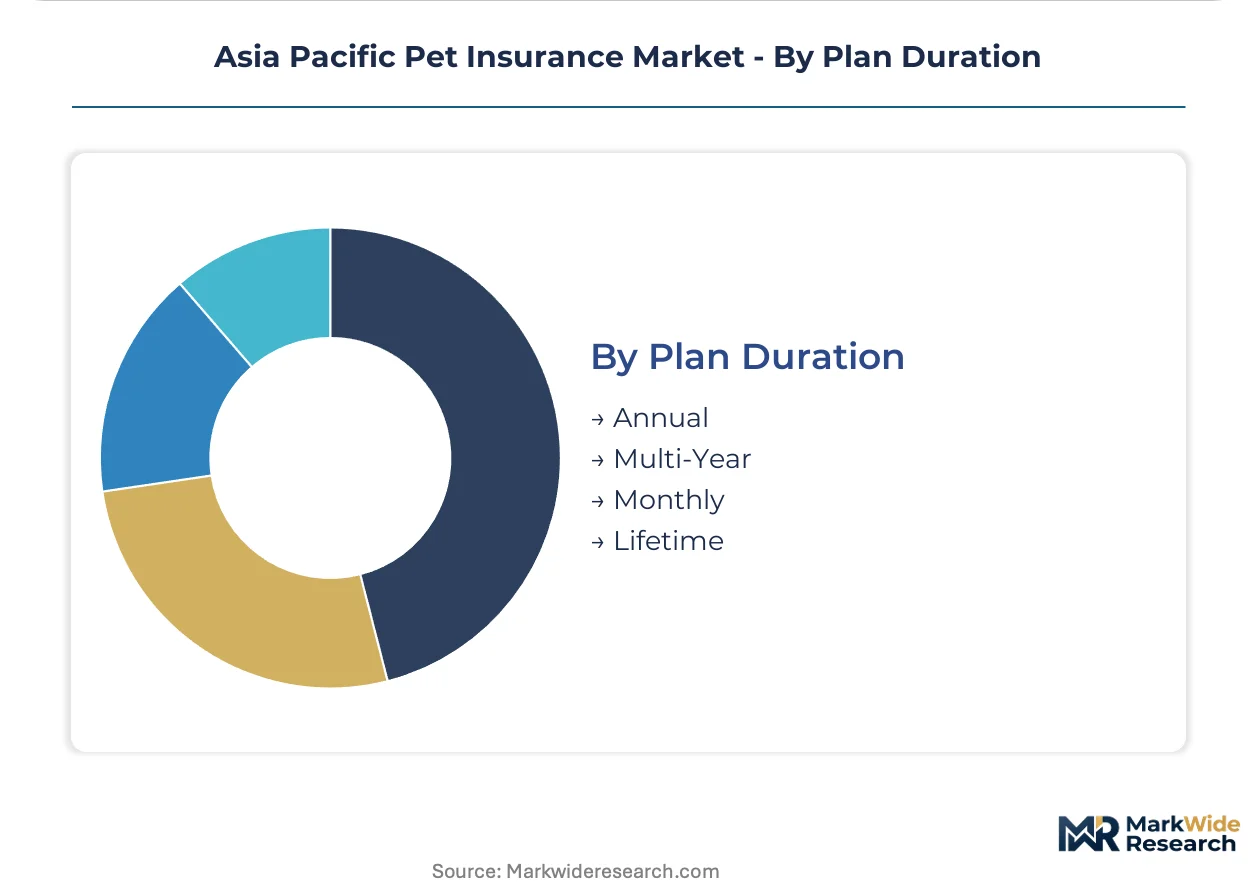
Plan Duration:
Maturity gradients separate established annual renewal cycles from experimental lifetime products with unproven actuarial performance.
- Annual:Twelve-month renewable contracts with rate adjustment flexibility and standard waiting periods. Australian APRA-regulated carriers rely on annual structures to manage claims inflation exposure.
- Multi-Year:Fixed-premium commitments spanning two to five years with guaranteed renewal terms. Japanese incumbents with established loss ratio data offer multi-year products to reduce churn.
- Monthly:Subscription-style billing with cancellation flexibility attracting digitally native younger policyholders. Seoul-based insurtechs deploy monthly models to lower adoption barriers.
- Lifetime:Guaranteed renewable coverage without age-based exclusion, subject to premium adjustment clauses. Limited availability reflects actuarial uncertainty around chronic disease cost trajectories.
Annual plans dominate policy counts, while Monthly billing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuarial talent clusters in Sydney and Tokyo anchor product development capacity across the Asia Pacific pet insurance corridor. Veterinary economist concentrations in Australian university hospitals and Japanese research institutes supply pricing model inputs that shape regional policy design.
Japan
Specialist veterinarian density in Tokyo and Osaka prefectures drives demand for high-value comprehensive policies. The Financial Services Agency mandates quarterly solvency disclosures that elevate operational overhead for mono-line carriers. Dense referral networks at university hospitals in Kanto region concentrate distribution control among incumbent underwriters with established clinic partnerships.
Australia
Millennial pet ownership clusters in Sydney and Melbourne generate network effects that accelerate direct-channel customer acquisition. The Prudential Regulation Authority enforces granular claims-handling transparency standards that reduce policy comparison friction. Specialist veterinary wage inflation in capital cities compresses loss ratios and forces product redesign toward higher co-payment structures.
South Korea
Digital-native pet owners in Seoul Capital Area favor subscription-style monthly billing over traditional annual renewals. The country's financial regulator maintains licensing frameworks for embedded insurance distribution through super-app ecosystems. KakaoTalk-integrated carriers in Gangnam and Jongno districts bypass legacy agency cost structures entirely.
Singapore
Preventive care awareness among first-time adopters in the city-state creates white space for wellness plan expansion. The Monetary Authority of Singapore oversees digital insurance licensing pathways that enable insurtech market entry. Veterinary clinic partnerships in Orchard and Novena medical clusters remain underdeveloped relative to Japanese benchmarks.
India
Price-sensitive first-time adopters in Mumbai and Delhi favor basic coverage with higher co-payment ratios over comprehensive products. The Insurance Regulatory and Development Authority enforces solvency standards that filter out undercapitalized entrants. Emerging distribution partnerships with pet specialty retailers in Bangalore and Hyderabad show nascent penetration.
Asia Pacific Pet Insurance Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates premium volume in Japanese and Australian metropolitan clusters. Tiered competition separates multi-line incumbents with existing compliance infrastructure from digital-native challengers attacking acquisition cost economics. Two strategic archetypes dominate: domestic carriers leveraging dense veterinary clinic networks, and international players deploying direct-to-consumer platforms. M&A activity targets veterinary telehealth capabilities, while capacity expansion concentrates in Southeast Asian digital distribution.
Among Japan-based underwriters, Sompo Japan Insurance Inc. and Anicom Holdings Inc. exemplify the clinic-network archetype, with the latter anchoring its position through exclusive veterinary partnerships. Allianz Care represents the international direct-channel model, competing through digital platforms that reduce friction across Southeast Asian markets. These three occupy distinct competitive positions that reflect divergent bets on distribution economics versus referral network control.
| Leading Market Players |
|---|
| Sompo Japan Insurance Inc. |
| Allianz Care |
| Anicom Holdings Inc |
| The New India Assurance Company |
| PetSure |
| ipet Insurance Co., Ltd. |
| Mitsui Sumitomo Insurance |
| Medibank Private Limited |
| Rakuten General Insurance |
| Others |
Value Chain & Pricing Dynamics
Comprehensive policy premiums in Tokyo and Sydney diverge sharply from basic accident coverage in emerging Southeast Asian markets, with this bifurcation driving parallel supply chain configurations that concentrate high-value underwriting talent in Australian and Japanese actuarial hubs while pushing standardized digital distribution infrastructure into lower-cost regional centers. APRA-mandated disclosure standards in Australia and FSA solvency requirements in Japan elevate compliance costs that filter into premium pricing, whereas nascent markets in Indonesia and Thailand absorb these overheads through embedded super-app partnerships that bypass traditional agency networks.
Pricing Analysis
Capacity additions in Seoul's insurtech sector are reshaping price floors across monthly subscription products, forcing incumbent Japanese carriers to compress margins on annual renewable contracts. Pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in co-payment ratios and annual benefit ceilings rather than brand positioning. Cost compression in basic coverage intensifies because direct-to-consumer digital entrants in South Korea bypass legacy commission structures. Mass-market first-time adopters in India and Indonesia exhibit highest price sensitivity, while comprehensive policyholders in Australian metropolitan clusters prioritize claims service quality over premium minimization.
Supply Chain Analysis
Freight costs for veterinary pharmaceutical imports into Australia and Japan exert modest pressure on claims reserves, though this pales against labor cost escalations for specialist veterinarians in Sydney and Melbourne. Underwriting capacity concentrates in Japan, Australia, and South Korea, with actuarial talent and veterinary economist clusters anchoring regional product development. Raw material dependencies center on veterinary diagnostic equipment, proprietary claims management software, and reinsurance capacity from Lloyd's and Singapore hubs. Single-source vulnerability in reinsurance treaty renewals poses structural risk. Distribution runs through three channels: direct digital platforms, exclusive veterinary clinic partnerships, and embedded super-app ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where millennial pet owners in Tokyo and Sydney rotate spending toward comprehensive policies with specialist oncology coverage and wellness bundling, displacing basic accident-only products that dominated prior adoption waves.
For Market Incumbents: Deploy exclusive veterinary clinic partnerships as a defensive moat against digital-native challengers. Deepen integration with university hospital referral networks in Japan's Kanto region to limit competitor access to high-value policyholders. Counter APRA-mandated claims transparency requirements by accelerating real-time claims automation investments that reduce operational overhead. Address specialist veterinarian wage inflation in Australian capital cities through telehealth platform acquisitions that expand addressable provider pools without geographic concentration. For New Entrants and Emerging Players: MAS digital insurance licensing pathways in Singapore open a window for wellness plan specialization targeting first-time adopters in Orchard and Novena medical clusters. KakaoTalk-embedded distribution in South Korea's Seoul Capital Area offers the most penetrable go-to-market angle, bypassing legacy agency cost structures entirely. Target preventive care riders in Singapore where penetration lags Japanese benchmarks by a substantial margin. Pursue veterinary telehealth convergence as a differentiated acquisition hook that enables real-time claims pre-authorization. For Investors and Strategic Acquirers: Consolidation pressure builds where mono-line pet specialists face FSA quarterly solvency disclosure burdens that multi-line incumbents absorb through existing compliance infrastructure. Long-term viability favors carriers with diversified product portfolios spanning life, health, and pet lines that share back-office functions. Acquisition targets should display dense veterinary clinic partnerships or proven super-app integration capabilities. Watch for inflection signals in embedded insurance licensing approvals across Thailand and Indonesia, which would validate regional digital distribution expansion theses.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telehealth Acquisition | Enables real-time claims pre-authorization and reduces fraud exposure across Australian direct-to-consumer platforms. |
| Super-App Embedded Distribution | KakaoTalk and LINE integration in South Korea bypasses traditional agency cost structures entirely. |
| Wellness Plan Product Launch | Singapore's underdeveloped preventive care penetration creates first-mover advantage for bundled vaccination offerings. |
| Exclusive Clinic Partnership Expansion | Anicom Holdings' dense Japanese university hospital networks demonstrate referral control that limits competitor access. |
| Multi-Year Policy Introduction | Japanese incumbents with established loss ratio data leverage guaranteed renewal terms to reduce customer churn. |
Study Parameters
Bottom-up pet owner demand modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with veterinary clinic operations managers, pet insurance product directors at major underwriters, regulatory affairs specialists at APRA and FSA, and claims administrators at direct-to-consumer platforms supplied forward-looking pricing and distribution intelligence. Secondary validation drew from APRA prudential filings, FSA solvency disclosure registers, veterinary workforce surveys from Australian university hospitals, and embedded insurance licensing announcements from Singapore's MAS. Triangulation between policyholder adoption patterns and carrier premium volume reconciles demand-side and supply-side estimates.
Input-output matrices map veterinary service cost inflation, millennial household formation rates in metropolitan clusters, and regulatory compliance burden indices against projected policy issuance volumes across the analysis window. Segmentation dimensions encompass product architecture, customer acquisition channel, coverage comprehensiveness, and plan duration structure. CAGRs emerge from curve-fitting historical premium growth trajectories against modeled penetration ceilings in each national market. Forecast inputs include specialist veterinarian wage indices in Australian capital cities and super-app user engagement metrics in South Korea's digital ecosystem.
Revisions become necessary when regulatory licensing pathways in Thailand and Indonesia materialize with unexpected speed or when veterinary labor cost inflation in Japan's Kanto region accelerates beyond historical trends. Forecasts reflect assumptions about millennial pet ownership persistence and telehealth platform adoption curves that could shift with macroeconomic conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Buy Now Pay Later Platform Market
Investment Analysis and Financial Strategies
Global Healthcare Equipment Leasing Market
Investment Analysis and Financial Strategies
NPL Servicing Market
Investment Analysis and Financial Strategies
Gold Derivatives and Futures Market
Investment Analysis and Financial Strategies
China Payments Market
Investment Analysis and Financial Strategies
Factory and Warehouse Insurance Market
Investment Analysis and Financial Strategies
Student Loan Market
Investment Analysis and Financial Strategies
Financial Fraud Detection Software Market
Investment Analysis and Financial Strategies
India POS Terminals Market
Investment Analysis and Financial Strategies
Trust Accounting Software Market
Investment Analysis and Financial Strategies
E-Wallet Market
Investment Analysis and Financial Strategies
Contract for Difference Broker Market
Investment Analysis and Financial Strategies
US Buy Now Pay Later Services Market
Investment Analysis and Financial Strategies
Healthcare Asset Management Market
Investment Analysis and Financial Strategies
B2B2C Insurance Market
Investment Analysis and Financial Strategies
Micro Lending Market