
 Asia-Pacific Management Consulting Services Market | 2026-2036
Asia-Pacific Management Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Management Consulting Services Market Insights
Strategy-to-implementation revenue is fragmenting across the Asia-Pacific management consulting services landscape as clients unbundle advisory scopes. McKinsey & Company anchors its position through deep relationships with state-owned enterprises in China. Deloitte Consulting leverages its regulatory compliance capabilities across ASEAN financial hubs. Boston Consulting Group dominates digital transformation mandates for technology sector clients.
Management consulting services encompass structured advisory engagements delivered by professional services firms to improve organizational performance, spanning diagnostic assessment, solution design, and change management implementation with engagement durations typically ranging from eight weeks to multi-year transformations. Operations consulting and IT consulting command the deepest margin pools as clients prioritize execution over pure strategy formulation. Financial advisory services are accelerating fastest among startups seeking venture capital optimization and pre-IPO restructuring across the region's technology corridors.
India's SEBI mandates reshape financial advisory demand through tightened disclosure requirements for publicly listed entities. China's SAMR intensifies antitrust scrutiny of platform economies, redirecting strategy consulting toward compliance-oriented engagements. Australia's TGA and Japan's METI standards for healthcare and industrial policy respectively filter market access for specialized consultancies. Stakeholders must track how ASEAN regulatory harmonization initiatives alter cross-border service delivery models and talent mobility frameworks.
Market Dynamics
The Asia-Pacific management consulting services market is experiencing fundamental restructuring as clients unbundle strategy-to-implementation scopes, fragmenting advisory engagements into discrete diagnostic, design, and execution phases.
Growth Catalysts
- India's PLI scheme:Manufacturing incentives are accelerating demand for operations consulting as firms scale capacity and optimize supply chains under the production-linked incentive framework.
- Financial services digital mandates:Southeast Asian banks are expanding advisory budgets for core system modernization and regulatory technology integration.
- Singapore's wealth hub concentration:Asset management and family office formation is concentrating demand for financial advisory and compliance consulting services.
Market Restraints
- Regulatory friction from China's SAMR:Intensified antitrust scrutiny of platform economies is redirecting strategy consulting toward compliance-heavy engagements with narrower margins.
- Talent concentration risk in Mumbai and Singapore:Premium consulting talent pools concentrate in two cities, creating wage inflation and retention pressure.
- Technical limitation in cross-border data flows:ASEAN's fragmented data localization requirements restrict seamless delivery of cloud-based analytics and AI-enabled advisory tools.
Strategic Opportunities
- Underpenetrated Vietnam and Philippines:Manufacturing diversification from China is creating first-mover openings for supply chain and operations advisory in emerging industrial corridors.
- Technology convergence of AI and ESG reporting:Automated sustainability disclosure platforms are opening new advisory revenue streams as CSRD-aligned requirements reach Asia-Pacific subsidiaries.
- Japan's METI industrial policy:Semiconductor and battery manufacturing subsidies are generating demand for site selection, incentive negotiation, and workforce transition consulting.
Industry Challenges
- Skill scarcity in data engineering:Consulting firms struggle to recruit sufficient talent for AI implementation and advanced analytics delivery at scale.
- Certification timeline compression:India's SEBI disclosure mandates and Australia's TGA healthcare standards are shortening client compliance windows, straining project staffing.
- Integration complexity with legacy ERP systems:Digital transformation mandates require consultants to navigate heterogeneous technology stacks across client portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Management Consulting Services Market |
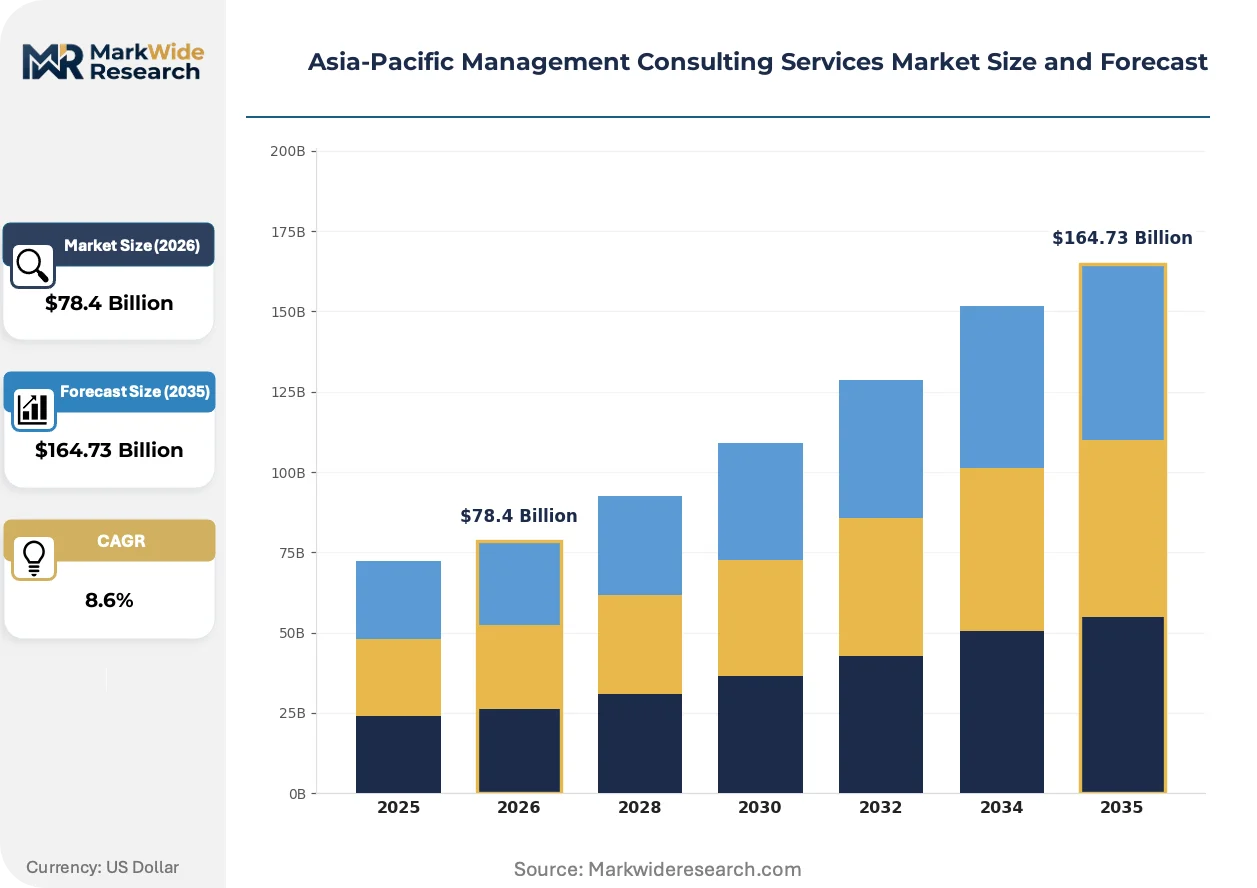
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Operations Consulting, Financial Advisory, IT Consulting Client Type: Corporations, Government Agencies, Non-profits, Startups Industry Vertical: Healthcare, Technology, Finance, Manufacturing Engagement Model: Project-based, Retainer, Ad-hoc, Outsourcing |
| Companies Covered | Roland Berger, Boston Consulting Group, Bain & Company, Accenture, Deloitte Consulting, Oliver Wyman, McKinsey & Company, Arthur D. Little, Kearney, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Management Consulting Services Market Trends and Innovations
Advisory delivery models are transforming as generative AI tools compress diagnostic phases and clients demand embedded implementation support rather than static recommendations.
Generative AI is digitizing traditional consulting workflows by automating market research synthesis, financial modeling, and presentation generation. Mid-tier advisory firms in India and Southeast Asia are adopting these tools fastest to compete with established players. The technology is digitizing entry-level analyst roles and compressing project timelines from twelve weeks to six for standard diagnostic engagements.
Japan's METI and Australia's TGA are tightening industrial and healthcare compliance standards respectively, forcing consultancies to build specialized regulatory capabilities. METI's semiconductor reshoring requirements and TGA's digital health device frameworks are creating premium advisory niches. Technology sector clients in Tokyo and Sydney are responding by procuring combined strategy and compliance services from single providers.
Enterprise buyers are unbundling advisory scopes and awarding implementation-only contracts to niche specialists rather than full-service firms. Financial services clients in Singapore and Hong Kong are separating strategy formulation from change management execution. This pattern is most visible among asset managers and insurers modernizing core systems under compressed regulatory deadlines.
Asia-Pacific Management Consulting Services Market Segmentation
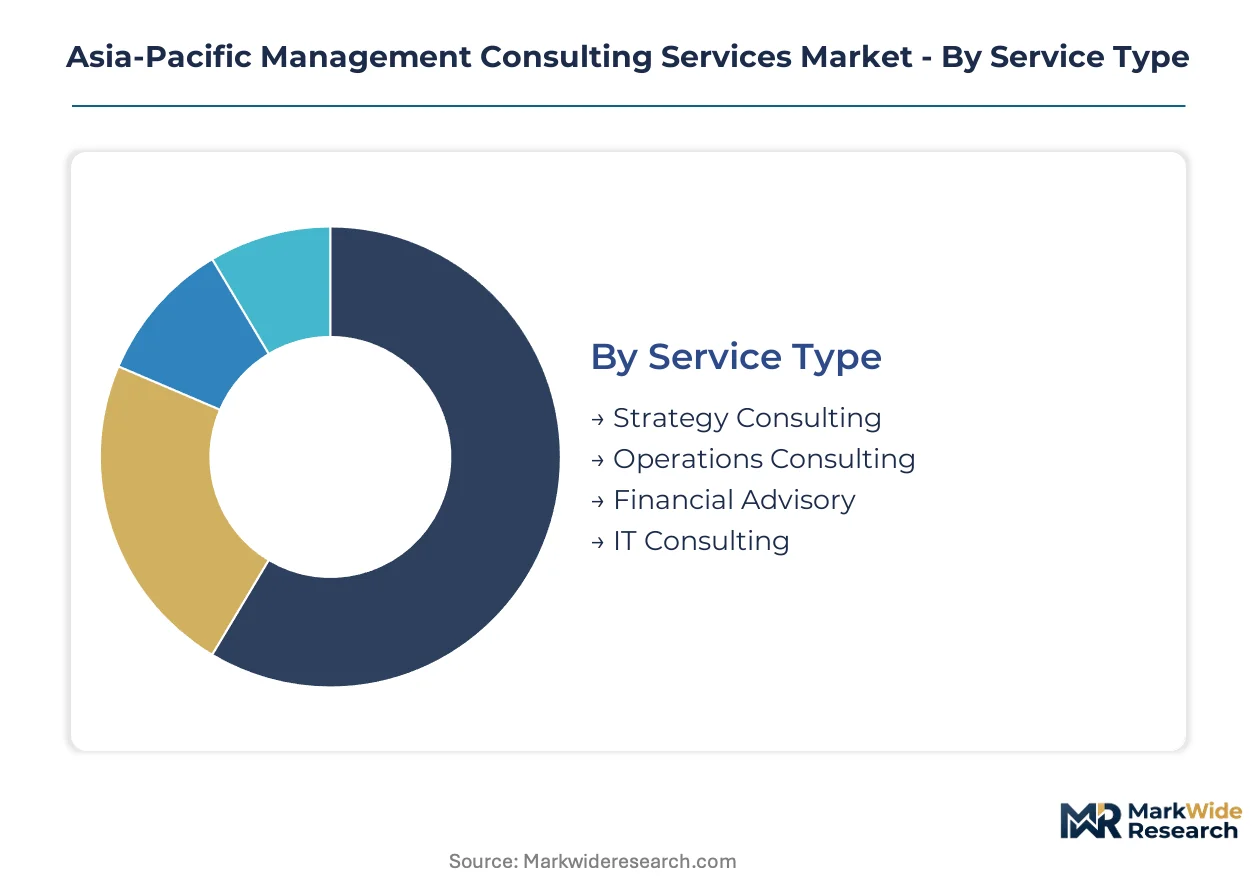
Segmentation reveals how consulting demand fragments across service maturity levels, client sophistication tiers, and delivery complexity. Each dimension exposes distinct margin structures and competitive dynamics that shape firm positioning across the Asia-Pacific region.
Service Type:
Mature advisory disciplines anchor revenue stability while emerging specializations capture expansion premiums across Southeast Asia and India's industrial corridors.
- Strategy Consulting:High-level organizational design and competitive positioning engagements. Demand concentrates among conglomerates in Singapore and state-owned enterprises in China navigating SAMR antitrust compliance, though margin compression intensifies as clients unbundle advisory scopes.
- Operations Consulting:Supply chain optimization, process reengineering, and manufacturing excellence programs. India's PLI scheme accelerates procurement across automotive and electronics clusters in Tamil Nadu and Gujarat as firms scale capacity under production-linked incentive frameworks.
- Financial Advisory:Transaction support, valuation, and capital structure optimization. Startups in Bengaluru's technology corridors and pre-IPO entities in Mumbai drive engagement volume for venture capital optimization and restructuring mandates.
- IT Consulting:Core system modernization, cloud migration, and regulatory technology integration. Southeast Asian banks in Singapore and Jakarta expand procurement for compliance-heavy digital transformation under compressed regulatory deadlines.
Operations Consulting retains volume leadership; IT Consulting holds the steepest expansion curve.
Client Type:
Procurement sophistication varies sharply across the client base, with institutional buyers demanding outcome-based contracts and emerging segments accepting standardized delivery models.
- Corporations:Large enterprises with formalized vendor management and multi-year framework agreements. Multinational manufacturers in Japan and diversified conglomerates in South Korea procure combined strategy and implementation services from single providers.
- Government Agencies:Public sector entities with regulated procurement processes and extended sales cycles. India's central ministries and Australian state governments drive demand for policy implementation and digital service delivery.
- Non-profits:Development organizations and social enterprises with constrained budgets and mission-driven metrics. International NGOs operating across ASEAN member states procure capacity-building advisory for program scale-up.
- Startups:Venture-backed and bootstrapped entities with compressed decision horizons and equity-compensation tolerance. Technology founders in Ho Chi Minh City and Manila seek rapid organizational design and fundraising preparation.
Corporations dominate current revenue contribution; Startups are expanding most quickly as venture formation accelerates across the region's technology corridors.
Industry Vertical:
Sector-specific regulatory density and capital intensity determine consulting procurement patterns and pricing power.
- Healthcare:Provider network optimization, clinical workflow design, and regulatory compliance. Australia's TGA digital health device frameworks and Japan's aging-care infrastructure investments concentrate demand in Sydney and Tokyo metropolitan areas.
- Technology:Platform strategy, AI implementation, and organizational scaling for high-growth entities. China's SAMR scrutiny redirects advisory toward compliance-oriented engagements with narrower margins for e-commerce and fintech clients.
- Finance:Core banking modernization, risk management, and wealth advisory infrastructure. Singapore's asset management licensing surge and Hong Kong's family office formation create concentrated procurement for regulatory technology and compliance consulting.
- Manufacturing:Smart factory deployment, supply chain resilience, and workforce transition. Japan's METI semiconductor reshoring subsidies and Vietnam's industrial zone expansion generate site selection and incentive negotiation mandates.
Finance commands premium pricing tiers; Manufacturing is gaining share fastest on industrial policy tailwinds across Northeast and Southeast Asia.
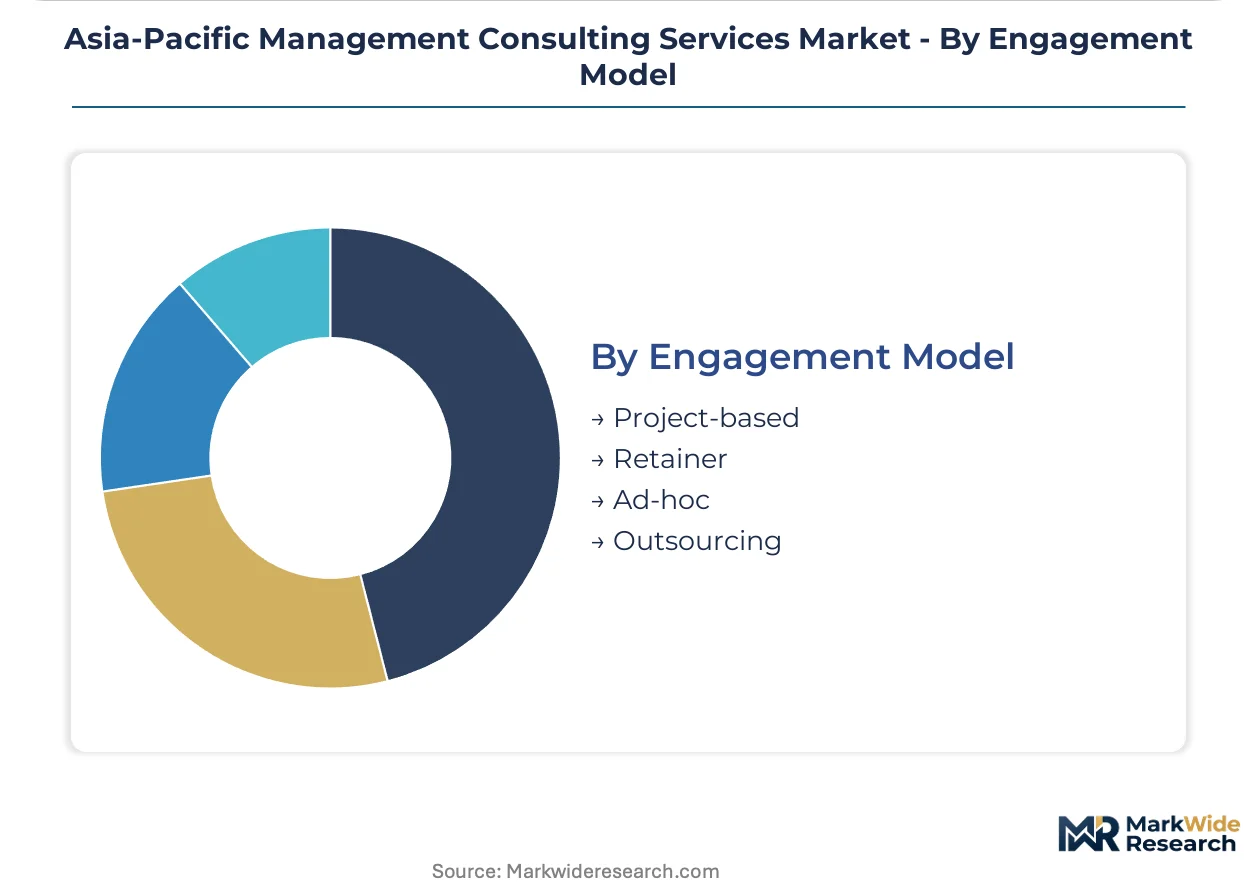
Engagement Model:
Contract structures reflect client risk tolerance and the degree of outcome accountability demanded from advisory providers.
- Project-based:Fixed-scope engagements with defined deliverables and timeline boundaries. Standard diagnostic and solution design work for mid-market manufacturers in Thailand and Indonesia typically spans eight to twelve weeks.
- Retainer:Ongoing advisory access with monthly or quarterly fee structures. Singapore-based asset managers and regional headquarters of multinational corporations procure continuous regulatory monitoring and strategic counsel.
- Ad-hoc:Situational, non-recurring engagements for specific events or crises. Restructuring mandates and regulatory defense work for Chinese platform companies facing SAMR investigation exemplify this pattern.
- Outsourcing:Transfer of ongoing business functions to advisory-managed delivery teams. Finance and accounting operations outsourcing for Australian healthcare providers and Japanese industrial firms illustrates this model.
Project-based structures retain transaction volume leadership; Retainer arrangements show the strongest pricing resilience as clients prioritize relationship continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific management consulting services landscape. Singapore's financial institutions procure continuous regulatory counsel through retainer structures. India's manufacturing conglomerates favor project-based operations advisory tied to government incentive programs. Australia's healthcare providers demand compliance-heavy implementation support.
Singapore
Asset managers and family offices drive sustained demand for financial advisory and regulatory technology consulting. The Monetary Authority of Singapore's digital banking licensing framework compels institutions to modernize core infrastructure. Marina Bay's concentration of regional headquarters generates retainer-based procurement for ongoing strategic counsel.
India
Manufacturing scale-up under PLI schemes and startup pre-IPO restructuring dominate advisory procurement. SEBI's tightened disclosure mandates for listed entities compress compliance timelines and strain consultant staffing. Bengaluru's technology corridors and Mumbai's financial districts concentrate venture capital optimization mandates.
Japan
Semiconductor reshoring subsidies and battery manufacturing incentives generate site selection and workforce transition consulting. METI's industrial policy standards filter market access for specialized advisory firms. Tokyo metropolitan areas concentrate demand for combined strategy and compliance services.
Australia
Healthcare providers procure provider network optimization and digital health device compliance consulting. TGA's tightening standards for medical technology create premium advisory niches with specialized regulatory capabilities. Sydney's healthcare infrastructure investments concentrate clinical workflow design mandates.
Vietnam
Manufacturing diversification from China creates first-mover openings for supply chain and industrial zone advisory. The government's industrial development policies in northern provinces attract foreign direct investment requiring site selection support. Ho Chi Minh City and emerging industrial corridors in Bac Ninh drive procurement from entrants establishing regional operations.
Asia-Pacific Management Consulting Services Market Competitive Landscape
Capability concentration sits with strategy specialists; scale advantage sits with professional services networks. The Asia-Pacific management consulting services market structures around three tiers: global strategy houses with deep enterprise relationships, technology-enabled implementation firms with delivery scale, and emerging specialists targeting regulatory niches. Competitive dynamics center on unbundling resistance and talent retention rather than price-based rivalry. Firms defend position through embedded client relationships and specialized regulatory capabilities.
Within the strategy-specialist tier, McKinsey & Company and Boston Consulting Group exemplify archetypes built on state-owned enterprise relationships and digital transformation mandates respectively. Among technology-enabled implementers, Accenture occupies a position representing delivery scale across cloud migration and regulatory technology integration. Deloitte Consulting anchors the compliance-capability vector across ASEAN financial hubs. Roland Berger and Arthur D. Little sit within the mid-tier specialist category serving industrial policy and manufacturing excellence programs.
| Leading Market Players |
|---|
| Roland Berger |
| Boston Consulting Group |
| Bain & Company |
| Accenture |
| Deloitte Consulting |
| Oliver Wyman |
| McKinsey & Company |
| Arthur D. Little |
| Kearney |
| Others |
Pricing and Supply Chain Analysis
Talent concentration risk in Mumbai and Singapore determines both the spread between premium and standard advisory tiers and the geographic configuration of delivery centers across the Asia-Pacific consulting landscape. Firms absorb wage inflation in these hubs while building secondary talent pools in Bengaluru and Ho Chi Minh City to moderate cost structures.
Pricing Analysis
Project-based contracts dominate advisory procurement, with retainer structures commanding premium positioning among Singapore asset managers and regional headquarters seeking continuous regulatory counsel. Price differentiation hinges on certification depth—SEBI-licensed financial advisors and METI-specialized industrial consultants capture tier-one rates—while unbundling trends compress margins for pure strategy diagnostics. Cost compression in standard-tier implementation work is intensifying because mid-tier Indian and Southeast Asian firms deploy generative AI tools to compress delivery timelines. Startups and mid-market manufacturers in Vietnam and Indonesia exhibit the highest price sensitivity; conglomerates in Japan and diversified groups in South Korea accept premium rates for combined strategy-implementation scopes.
Supply Chain Analysis
Tariff exposure between China and ASEAN member states dominates supply chain risk planning for manufacturing advisory practices serving industrial diversification mandates. Talent supply concentrates in India, Singapore, and Japan, with secondary pipelines emerging in Vietnam and the Philippines. Advisory delivery draws from three critical inputs: specialized regulatory expertise, data engineering capability, and sector-specific implementation experience. Single-source vulnerability sits with premium talent pools in Mumbai and Singapore, where retention pressure creates wage spiral dynamics. Distribution runs through direct partner-led relationships for enterprise clients and platform-mediated marketplaces for startup segments seeking rapid organizational design support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific management consulting services market rewards firms that control scarce implementation capabilities—AI engineering talent and specialized regulatory credentials—while penalizing those trapped in commoditized diagnostic work. The capability gap between strategy formulation and execution-ready advisory is widening fastest in India's manufacturing corridors and Southeast Asia's financial hubs.
For Market Incumbents: Pre-empt talent defection by embedding equity-linked compensation structures for senior data engineers and regulatory specialists in Mumbai and Singapore. Build captive delivery capabilities in Vietnam's northern industrial provinces before manufacturing advisory demand matures. The threat of mid-tier AI-enabled competitors from India compressing project timelines demands counter-investment in proprietary automation tools. For New Entrants and Emerging Players: Vietnam's industrial zone advisory remains structurally underpenetrated, offering first-mover positioning for supply chain and site selection specialists serving manufacturing relocations from China. The Philippines' emerging technology corridors present parallel whitespace for venture formation and pre-IPO restructuring services. A go-to-market angle anchored in SEBI compliance automation for India's listed mid-caps bypasses direct competition with established strategy houses. For Investors and Strategic Acquirers: ASEAN regulatory harmonization initiatives reshape the acquisition landscape by privileging consultancies with cross-border licensing frameworks and established talent mobility protocols. Target acquisition archetypes combine specialized regulatory capabilities with embedded client relationships in financial services or industrial policy verticals. The signal to watch is METI subsidy allocation velocity—accelerated semiconductor reshoring disbursements would validate premium valuations for Japanese manufacturing advisory specialists.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Diagnostic Automation | Compresses project timelines for Bengaluru mid-tier firms competing with global strategy houses. |
| SEBI Compliance Specialization | Captures premium pricing from listed entities facing compressed disclosure timelines under tightened mandates. |
| Vietnam Delivery Center Buildout | Positions firms for manufacturing diversification advisory as industrial zones attract FDI inflows. |
| METI Regulatory Certification | Filters market access for semiconductor and battery manufacturing consulting under Japanese industrial policy. |
| Cross-Border Talent Mobility Framework | Enables seamless project staffing across Singapore, India, and emerging ASEAN delivery hubs. |
Research Methodology
The analysis maps strategy consulting, operations consulting, financial advisory, and IT consulting sub-sectors, each validated through managing partners at regional advisory firms, procurement officers at multinational corporations, and regulatory affairs specialists at financial institutions. Primary interviews with these stakeholders combined with secondary validation from SEBI disclosure filings, METI industrial policy documents, Monetary Authority of Singapore licensing records, and ASEAN regulatory harmonization frameworks. Bottom-up engagement volume estimates triangulated against top-down market size assessments across service type, client type, and industry vertical dimensions.
The forecast framework holds macroeconomic growth trajectories, regulatory implementation timelines, and technology adoption curves within baseline assumptions while varying industrial policy intensity and cross-border data flow restrictions across sensitivity scenarios. Segmentation dimensions modeled include service maturity level, client sophistication tier, delivery complexity, and geographic regulatory cluster. CAGRs derived from trend extrapolation of historical advisory procurement patterns adjusted for identified structural shifts. Industry-specific forecast inputs incorporate PLI scheme disbursement velocity and digital banking licensing progression under MAS frameworks.
The forecast holds incumbent behavior within observed patterns; aggressive capability acquisition by technology-enabled implementers or accelerated regulatory unification across ASEAN would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
Corporate eLearning Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Frontline Workers Training Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Global Outplacement Services Market
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Private Tutoring Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
France Outplacement Services Market