
 Asia-Pacific Connected Cars Market | 2026-2036
Asia-Pacific Connected Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Connected Cars Market Outlook
The divergence between premium and commodity tiers in Asia-Pacific connected vehicles is hardening. Toyota Motor Corporation leverages its embedded telematics platform to sustain dominance in Japanese domestic fleet contracts. Hyundai Motor Group anchors its position through proprietary V2X stacks in South Korean smart highway pilots. Denso Corporation specializes in sensor fusion modules that differentiate its supply relationships with regional OEMs.
Connected cars integrate cellular, satellite, and dedicated short-range communications to enable real-time data exchange between vehicles, infrastructure, and cloud platforms; these systems rely on multi-band antenna arrays, edge computing gateways, and cybersecurity protocols to deliver navigation optimization, predictive maintenance, and automated emergency response. Passenger vehicles occupy the largest installed base across the region, though electric vehicles represent the fastest-expanding product category as battery platforms natively accommodate high-bandwidth connectivity architectures. Telematics commands the most mature revenue pool among technology segments, while V2X communication captures accelerating investment from municipal smart-city budgets.
Japan's METI issues type certification for automated driving systems, while China's MIIT governs cross-border data transmission from connected vehicle platforms under national security frameworks; South Korea's MFDS coordinates with transport regulators on cybersecurity standards for intelligent vehicle networks. Stakeholders must monitor how diverging data localization requirements across these jurisdictions reshape cloud architecture decisions and supplier qualification timelines.
Market Dynamics
China's MIIT intelligent connected vehicle standards are forcing a wholesale recertification of telematics platforms across the Asia-Pacific supply base, compressing product development timelines and redrawing supplier qualification hierarchies.
Growth Catalysts
- Smart highway infrastructure:South Korea's nationwide C-ITS deployment creates captive demand for V2X-enabled fleets in freight corridors linking Seoul to Busan.
- MIIT cross-border data rules:China's national security frameworks mandate localized cloud architecture, accelerating domestic edge computing investments.
- Telematics penetration in commercial fleets:Southeast Asian logistics operators deploy real-time vehicle monitoring to optimize fuel consumption and route efficiency.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance system chips depend on fabrication capacity concentrated in Taiwan and South Korea, exposing OEMs to allocation volatility.
- Cellular module cost structure:5G NR automotive-grade modems carry premium pricing that compresses margins in economy passenger segments.
- Data localization compliance:Divergent national storage requirements across Japan, China, and South Korea fragment cloud architecture economics.
Strategic Opportunities
- Indonesia's archipelago logistics:Island-hopping freight networks remain underpenetrated by connected fleet solutions, offering first-mover positioning.
- Battery-electric platform convergence:Native high-voltage architectures accommodate integrated connectivity stacks without retrofit complexity.
- Japan's METI automated driving certification:Type approval pathways for Level 3 systems create regulatory tailwind for sensor fusion suppliers.
Industry Challenges
- Cybersecurity engineering scarcity:Automotive network security expertise concentrates in Tokyo and Seoul, constraining supplier scaling.
- Multi-standard certification timelines:Parallel MIIT, METI, and MFDS approval processes extend product launch windows by 8-14 months.
- Legacy fleet integration:Aftermarket telematics retrofits face CAN bus protocol fragmentation across Japanese and Korean OEM generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Connected Cars Market |
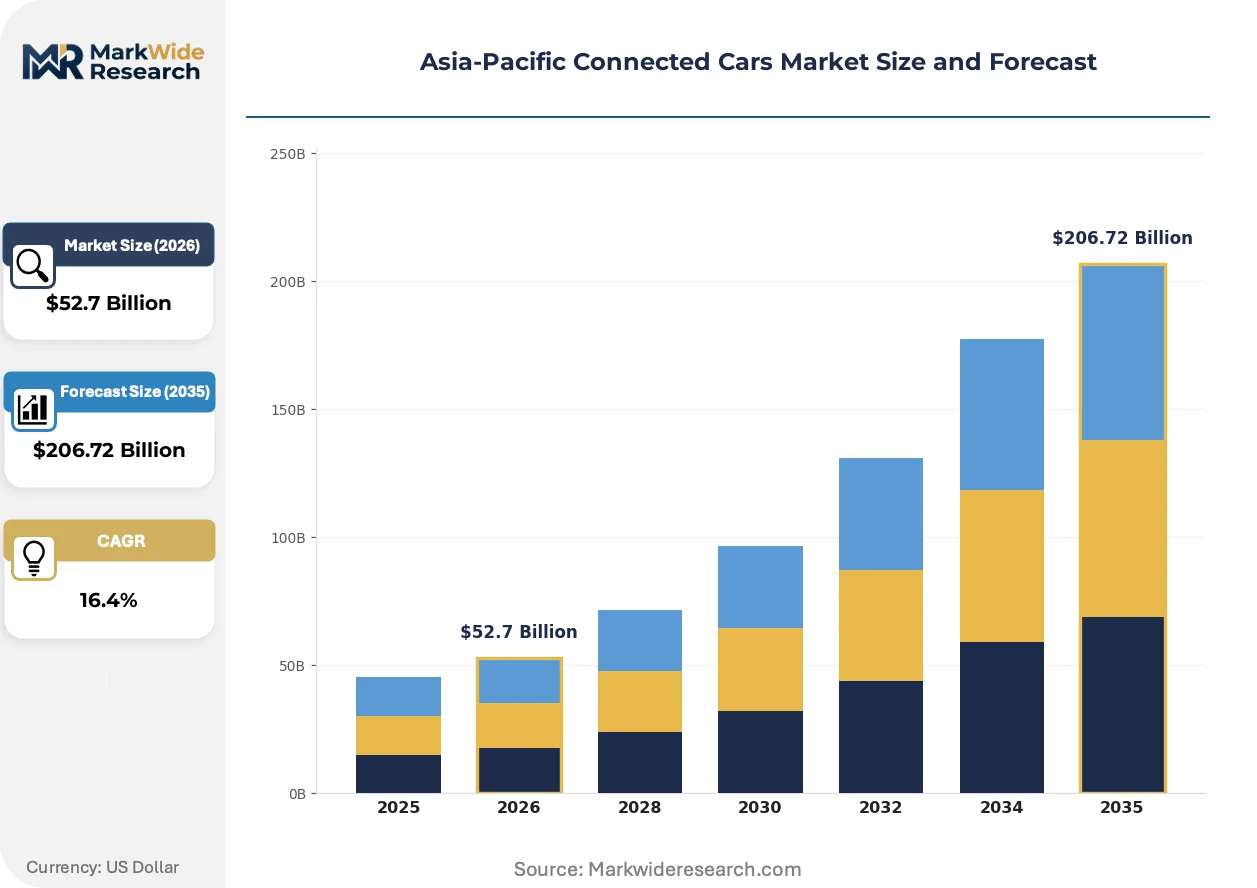
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $206.72 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Cars Technology: Telematics, V2X Communication, Sensor Technology, Infotainment Systems End User: Fleet Operators, Individual Consumers, Car Manufacturers, Insurance Companies Service Type: Emergency Services, Navigation Services, Maintenance Services, Entertainment Services |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Group, Honda Motor Co. Ltd., Nissan Motor Corporation, Continental AG, Robert Bosch GmbH, ZF Friedrichshafen, Denso Corporation, SAIC Motor Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Connected Cars Market Strategic Shifts
Software-defined vehicle architectures are collapsing the traditional boundary between infotainment and powertrain control domains, enabling over-the-air feature monetization that reshapes automotive revenue models.
Cellular V2X is electrifying roadside-to-vehicle communication protocols. South Korean smart highway pilots deploy 5.9 GHz DSRC alternatives that municipalities in Gyeonggi Province now mandate for new infrastructure contracts. This technology compression is forcing Tier-1 suppliers to sunset proprietary short-range radio development.
Japan's METI type certification framework for automated driving systems now requires documented cybersecurity management systems aligned with ISO/SAE 21434. Tier-2 sensor suppliers in Aichi Prefecture are reconfiguring quality management to satisfy these audit protocols. The regulation most acutely affects vision-system providers seeking domestic OEM qualification.
Fleet procurement patterns now prioritize outcome-based uptime guarantees over hardware ownership. Southeast Asian logistics operators contract directly with telematics platform providers for vehicle availability metrics, bypassing traditional dealer channels. This disintermediation concentrates in Indonesia's mining and plantation transport sectors where asset utilization drives contract awards.
Asia-Pacific Connected Cars Market Segmentation
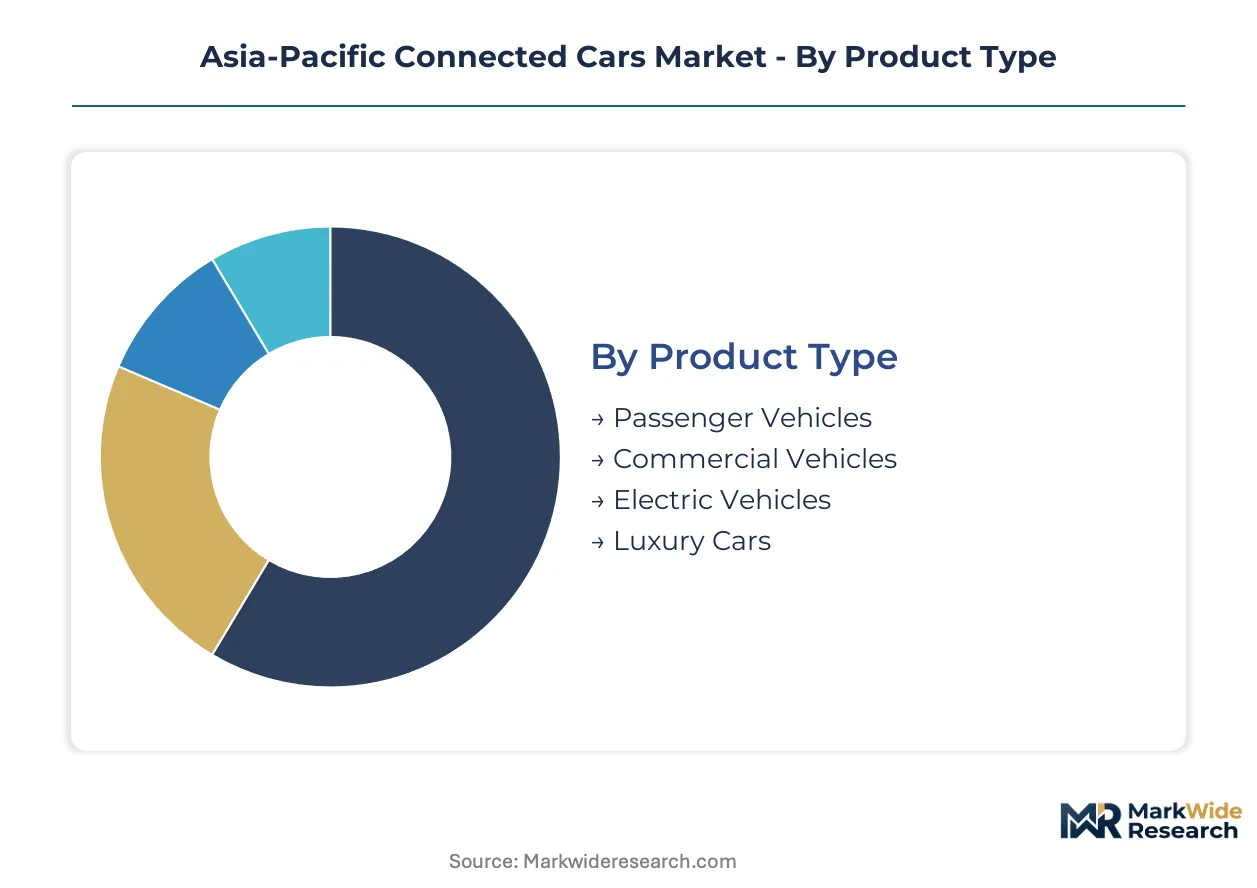
Segmentation in Asia-Pacific connected vehicles exposes divergent certification burdens across product tiers. MIIT mandates for intelligent connected vehicles reshape which segments require localized cloud architecture versus cross-border data compliance.
Product Type:
MIIT type certification applies differentially across vehicle categories, with electric vehicles facing the most stringent cybersecurity audit protocols while luxury cars navigate dual METI-MIIT approval pathways.
- Passenger Vehicles:Embedded telematics platforms dominate this installed base, with Japanese domestic OEMs integrating Denso sensor fusion modules. Fleet procurement in Nagoya and Toyota City concentrates demand for standardized connectivity stacks that satisfy METI automated driving certification.
- Commercial Vehicles:Real-time vehicle monitoring systems optimize fuel consumption across Southeast Asian logistics corridors. Indonesian mining and plantation transport sectors contract directly with platform providers for uptime guarantees, bypassing traditional dealer networks.
- Electric Vehicles:Native high-voltage architectures accommodate integrated connectivity without retrofit complexity. Battery platforms from Korean and Chinese OEMs natively support high-bandwidth telematics.
- Luxury Cars:Premium segments absorb 5G NR automotive-grade modem costs through three-tier pricing structures.
Passenger vehicles sit at the top of the volume ranking, with electric vehicles climbing the fastest.
Technology:
Cost tier stratification separates mature revenue pools from emerging investment categories, with telematics commanding established margins while V2X captures municipal smart-city budgets.
- Telematics:The most mature revenue pool among technology segments, delivering predictive maintenance and route optimization. Southeast Asian logistics operators deploy these systems across freight corridors linking Seoul to Busan, with Hyundai Motor Group anchoring supply through proprietary platforms.
- V2X Communication:Cellular V2X electrifies roadside-to-vehicle protocols. South Korea's nationwide C-ITS deployment creates captive demand, forcing Tier-1 suppliers to sunset proprietary short-range radio development.
- Sensor Technology:Denso Corporation specializes in fusion modules that differentiate regional OEM supply relationships. METI type certification now requires ISO/SAE 21434-aligned cybersecurity management systems.
- Infotainment Systems:Software-defined architectures collapse boundaries with powertrain control domains, enabling over-the-air monetization.
Telematics maintains the largest revenue base, though V2X communication gains share fastest on municipal infrastructure spending.
End User:
Application focus shifts hardware procurement from ownership models to outcome-based contracting, particularly in asset-intensive sectors where utilization metrics determine vendor selection.
- Fleet Operators:Accelerating adoption of telematics-enabled vehicles across Southeast Asia. These stakeholders prioritize vehicle availability metrics over hardware ownership, concentrating procurement power in Indonesia's archipelago logistics networks.
- Individual Consumers:Demand concentrates in Japan's automotive electronics corridor, with Toyota's embedded platforms sustaining domestic market dominance.
- Car Manufacturers:Face compressed product development timelines from MIIT recertification requirements.
- Insurance Companies:Emerging demand segment leveraging real-time driving data for risk-adjusted pricing models.
Fleet operators occupy the dominant procurement volume, with insurance companies expanding most quickly as data monetization matures.
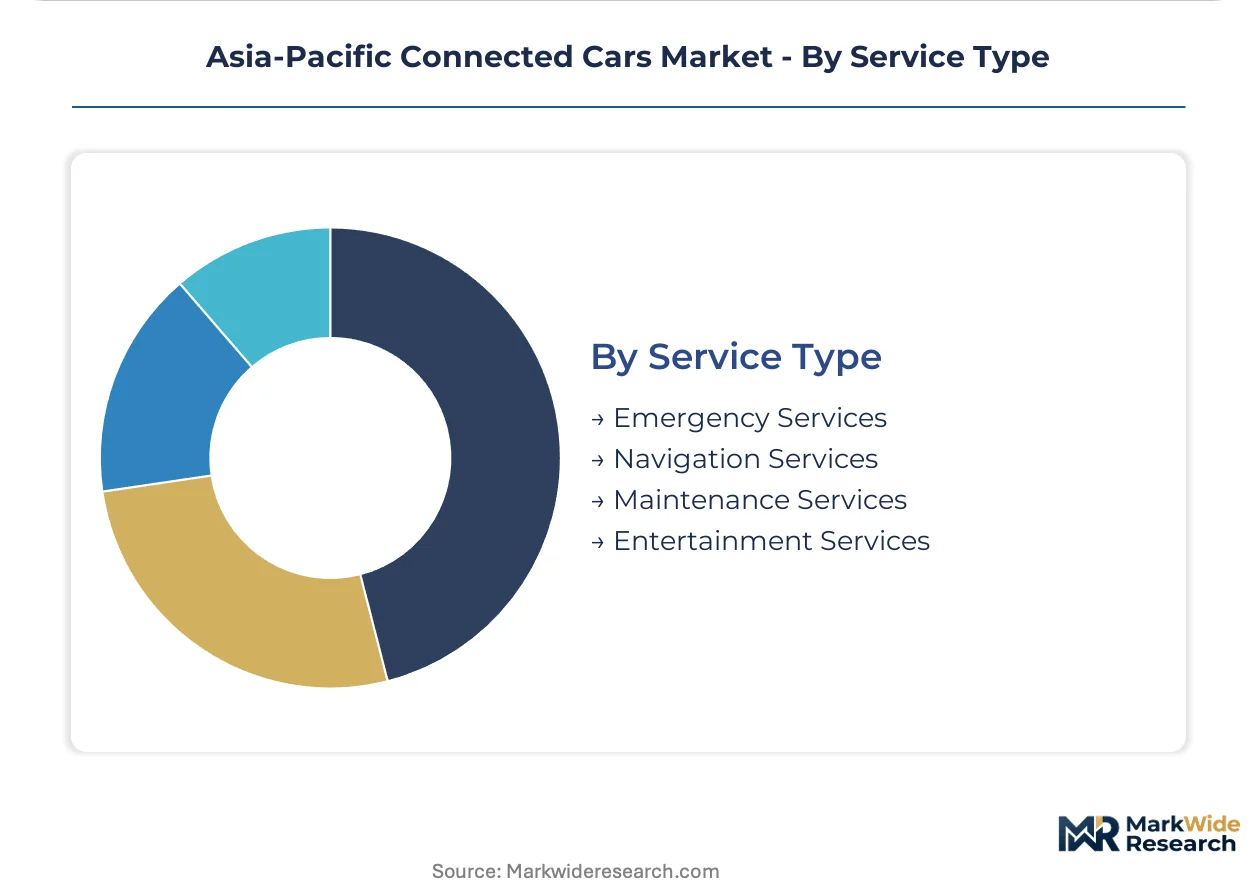
Service Type:
Customer type differentiation separates safety-critical from convenience-oriented offerings, with emergency services facing the strictest latency requirements and regulatory oversight.
- Emergency Services:Automated emergency response systems rely on multi-band antenna arrays and edge computing gateways. These services face the most stringent certification requirements under METI and MFDS cybersecurity coordination frameworks.
- Navigation Services:Real-time data exchange between vehicles and cloud platforms optimizes routing across South Korean smart highway pilots. 5.9 GHz DSRC alternatives in Gyeonggi Province now mandate specific protocol compliance.
- Maintenance Services:Predictive algorithms reduce downtime for commercial fleets. Southeast Asian operators deploy these to optimize asset utilization in mining and plantation transport.
- Entertainment Services:Over-the-air feature monetization reshapes automotive revenue models as software-defined architectures mature.
Emergency services command the highest regulatory burden, while entertainment services follow the steepest expansion trajectory on consumer software spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive connectivity engineering talent clusters around Nagoya, Seoul, and Shanghai, anchoring the region's product development pipelines. These workforce concentrations shape how MIIT, METI, and MFDS standards propagate through supplier networks.
China
Domestic OEMs and international joint ventures drive demand for intelligent connected vehicle platforms. MIIT mandates for cross-border data transmission force localized cloud architecture investments. Shanghai and Shenzhen host the densest concentrations of telematics software engineering teams serving both passenger and commercial vehicle programs.
Japan
Embedded telematics platforms sustain dominance in domestic fleet contracts through standardized connectivity stacks. METI type certification for automated driving systems requires ISO/SAE 21434-aligned cybersecurity management. Aichi Prefecture's sensor fusion specialists reconfigure quality protocols to satisfy these audit requirements.
South Korea
Smart highway pilots create captive demand for V2X-enabled fleets along freight corridors linking Seoul to Busan. MFDS coordination with transport regulators shapes cybersecurity standards for intelligent vehicle networks. Hyundai Motor Group anchors supply relationships through proprietary V2X stack development.
Indonesia
Island-hopping freight networks remain underpenetrated by connected fleet solutions, attracting first-mover platform providers. Mining and plantation transport sectors contract directly with telematics providers for uptime guarantees. Jakarta and Surabaya concentrate logistics operator procurement decisions.
India
Commercial fleet operators accelerate real-time vehicle monitoring adoption to optimize fuel consumption across highway corridors. BIS standards for automotive electronics create compliance pathways for connectivity module suppliers. Bangalore and Pune host emerging engineering centers serving both domestic OEMs and export programs.
Asia-Pacific Connected Cars Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific connected vehicle ecosystem. Integrated automotive groups with captive electronics divisions face pressure from specialized telematics platform developers. The competitive terrain separates into three archetypes: domestic OEMs with embedded connectivity stacks, global Tier-1 suppliers with multi-client sensor portfolios, and pure-play software vendors targeting fleet outcome contracts. Dominant competitive moves include strategic partnerships for smart highway pilot access and portfolio diversification into battery-electric native architectures.
Within the domestic OEM tier, Toyota Motor Corporation and Hyundai Motor Group exemplify integrated platform strategies, while Denso Corporation occupies a specialist position in sensor fusion modules. These three entities represent contrasting approaches to regulatory compliance—captive certification resources versus supplier-network coordination—across the MIIT-METI-MFDS approval landscape.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Group |
| Honda Motor Co. Ltd. |
| Nissan Motor Corporation |
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen |
| Denso Corporation |
| SAIC Motor Corporation |
| Others |
Value Chain & Pricing Dynamics
Automotive-grade 5G NR modem unit costs cascade through Asia-Pacific connected vehicle supply chains, compressing margins in economy passenger segments while premium tiers absorb premiums through extended service bundling. This input cost structure stratifies final platform pricing across MIIT certification tiers, with localized cloud architecture investments adding further differentiation between China-compliant and export-oriented configurations.
Pricing Analysis
Bundled telematics service contracts dominate fleet procurement, while unbundled hardware-plus-SaaS tiers prevail in individual consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified sensor fusion platforms from baseline connectivity modules. Pricing pressure stems from 5G NR automotive-grade modem premiums that erode economy segment viability. Fleet operators in Southeast Asia exhibit highest price sensitivity due to asset utilization metrics driving vendor selection, while luxury OEMs absorb costs through extended warranty and over-the-air feature monetization.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and Korean OEMs mandate multi-supplier qualification for cellular modems and edge computing gateways, fragmenting procurement concentration. Semiconductor fabrication capacity clusters in Taiwan and South Korea, with sensor fusion module assembly concentrated in Aichi Prefecture and Shanghai. Raw material dependencies span lithium-ion battery substrates, multi-band antenna substrates, and automotive-grade silicon. Single-source vulnerability concentrates in advanced driver-assistance system chip allocation. Distribution runs through captive OEM electronics divisions and specialized Tier-1 platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play: MIIT-mandated localized cloud architecture investments in China create cost differentials against Japan's METI certification pathways, rewarding suppliers with dual-jurisdiction qualification capabilities.
For Market Incumbents: Cement dominance through captive certification resources spanning MIIT, METI, and MFDS approval frameworks. Deepen backward integration into sensor fusion module production to offset Tier-2 supplier cybersecurity engineering scarcity. Prioritize battery-electric native architecture investments that eliminate retrofit complexity and compress rival qualification timelines. For New Entrants and Emerging Players: Begin with Indonesia's archipelago logistics networks, where island-hopping freight corridors remain underpenetrated by connected fleet solutions. Target mining and plantation transport sectors with outcome-based uptime guarantees that bypass established dealer channels. Pursue direct contracting models with asset-intensive operators seeking vehicle availability metrics over hardware ownership. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play telematics platform developers possessing ISO/SAE 21434-aligned cybersecurity management systems and multi-jurisdiction certification track records. Long-term viability hinges on software-defined vehicle architecture positioning that enables over-the-air feature monetization. Watch for inflection when municipal smart-city V2X deployment budgets accelerate beyond pilot-phase commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables over-the-air monetization that collapses infotainment-powertrain boundaries for Japanese OEMs. |
| MIIT Certification Pre-Qualification | Accelerates product launch windows by 8-14 months versus parallel METI-MFDS approval processes. |
| Smart Highway Pilot Partnership | Secures captive demand in South Korean C-ITS corridors linking Seoul to Busan freight networks. |
| Edge Computing Localization | Satisfies China's cross-border data rules while reducing latency for automated emergency response systems. |
| Battery-Electric Platform Convergence | Eliminates retrofit complexity for Korean and Chinese OEM high-voltage architectures. |
Study Parameters
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, fleet operations directors, and municipal transport planners grounded qualitative assessments. Secondary validation drew from MIIT intelligent connected vehicle filings, METI automated driving type certification records, vehicle production databases, and smart-city infrastructure procurement disclosures. Bottom-up and top-down triangulation reconciled segment-level demand with aggregate market sizing across the analysis window.
Bottom-up modeling aggregated unit economics across vehicle class, propulsion architecture, and regional production cluster dimensions. Top-down validation cross-referenced regulatory mandate timelines and municipal infrastructure budget trajectories. CAGRs derived from slope-intercept analysis of certification-driven replacement cycles and fleet penetration saturation curves. Forecast inputs incorporated MIIT recertification compression effects and V2X municipal deployment acceleration patterns.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor fabrication capacity, abrupt shifts in MFDS-METI cybersecurity coordination frameworks, and battery-electric platform adoption trajectories diverging from high-voltage architecture assumptions. Deviation in MIIT cross-border data rule enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Electric Vehicle Infotainment Market