
 Asia-Pacific Affordable Housing Market | 2026-2036
Asia-Pacific Affordable Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Affordable Housing Market Insights
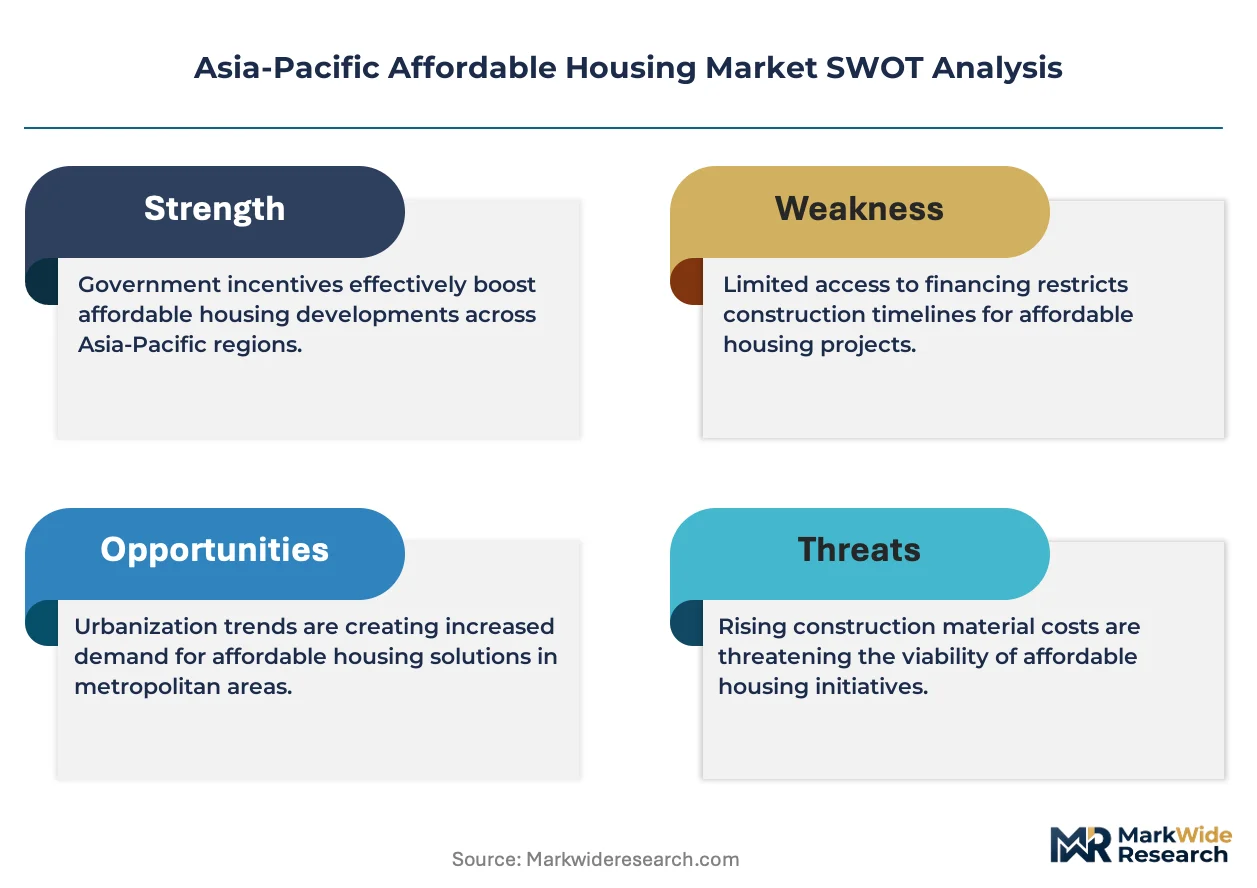
Land assembly and site preparation revenue is reconfiguring margin pools across the Asia-Pacific affordable housing value chain, shifting returns from pure construction toward early-stage development capabilities. China Vanke Co., Ltd. leverages its municipal land-bank relationships to secure contiguous parcels at below-market resettlement terms. DLF India anchors its affordable portfolio through in-house soil remediation and infrastructure provisioning that reduces third-party dependency. Tata Housing Development Company Limited differentiates via integrated township models that bundle commercial cross-subsidies with residential units.
Asia-Pacific affordable housing encompasses residential dwellings priced below median household income thresholds, typically constructed with load-bearing masonry or reinforced concrete frames achieving compression strengths of 20-25 MPa, designed to shelter households earning 30-80% of area median income. Low-cost housing dominates volume across India and Southeast Asia where per-unit construction costs must compress below $150 per square meter to maintain affordability ceilings. Modular homes and prefabricated units represent the fastest-expanding construction method segment as factory-based panel production cuts on-site labor dependence and compresses build cycles from eighteen to ten months in markets facing skilled mason shortages.
India's Ministry of Housing and Urban Affairs enforces PMAY eligibility criteria that mandate carpet-area limits and beneficiary income caps, directly shaping product specifications developers must meet for interest-subsidy access. China's Ministry of Housing and Urban-Rural Development supervises rental housing quotas within mixed-income developments, influencing project feasibility models across Sunac China Holdings Limited and Seazen Holdings Co., Ltd. portfolios. Stakeholders must monitor how municipal land-use rezoning in Ho Chi Minh City, Jakarta, and Manila alters developable supply corridors before committing capital to multi-year project pipelines.
Market Dynamics
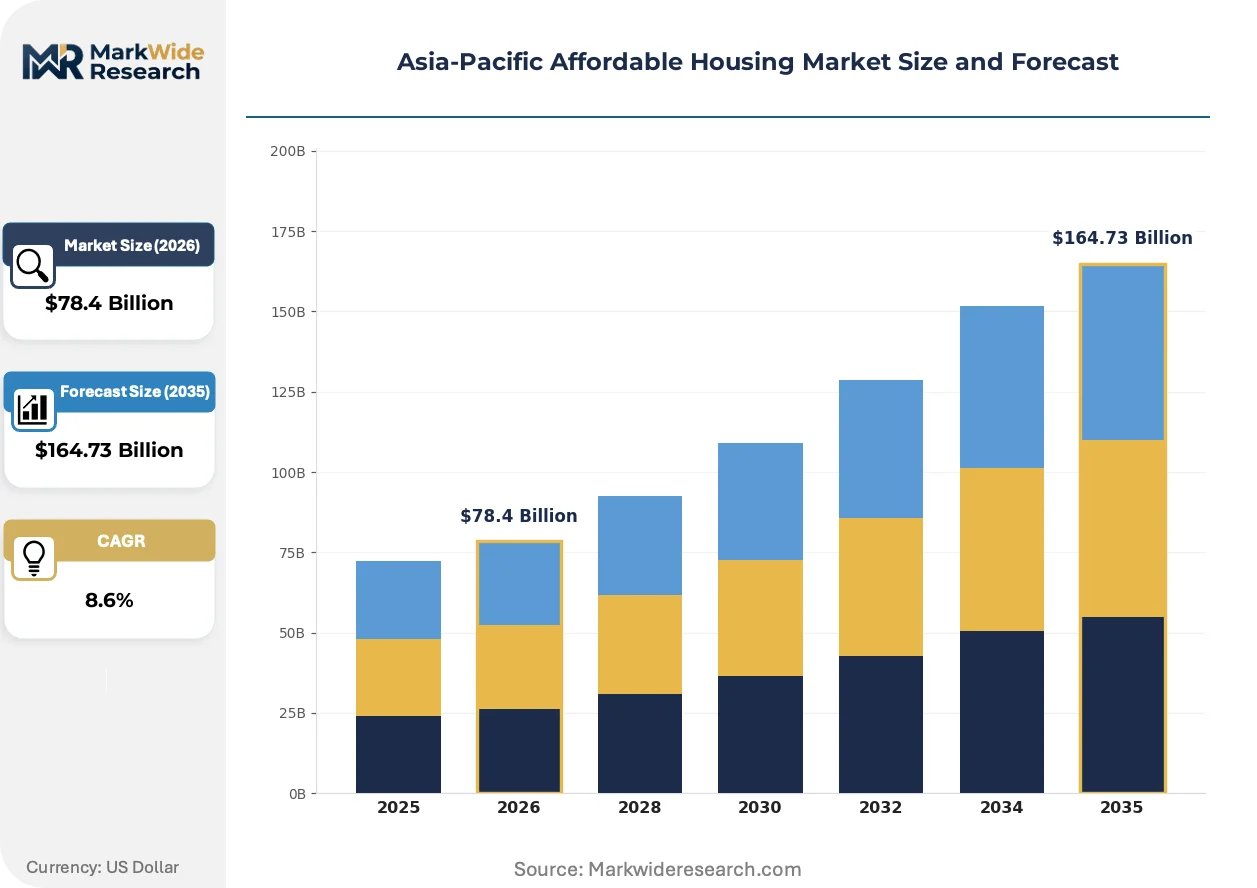
India's Pradhan Mantri Awas Yojana subsidy scheme is compressing the formalization timeline for informal housing settlements, forcing developers to reconfigure project economics around interest-rate subsidies rather than speculative land appreciation.
Growth Catalysts
- Central subsidy schemes:India's PMAY interest subvention reduces effective mortgage rates for low-income borrowers, expanding addressable demand in tier-2 urban centers.
- Prefabricated panel systems:Factory-based production cuts skilled mason dependence and compresses build cycles, enabling faster inventory turnover in labor-scarce Southeast Asian markets.
- Vietnam:Ho Chi Minh City's municipal rezoning of industrial peripheries into residential corridors is unlocking contiguous land parcels for mass housing development.
Market Restraints
- Rebar and cement price volatility:Input cost swings erode fixed-price contract margins for developers locked into subsidy-capped selling prices.
- Land banking concentration:State-owned enterprises in China control prime urban parcels, limiting private developer access to affordable housing-zoned sites.
- Carpet-area caps:India's PMAY eligibility mandates maximum unit sizes that constrain design flexibility and cross-subsidy generation.
Strategic Opportunities
- Indonesia:Jakarta's peripheral satellite cities remain underpenetrated by formal affordable housing supply, presenting greenfield development potential.
- Modular-microgrid convergence:Integration of prefabricated units with decentralized solar-plus-storage systems addresses infrastructure gaps in Philippine peri-urban settlements.
- Rental housing quotas:China's Ministry of Housing and Urban-Rural Development mandates are creating dedicated revenue streams within mixed-income projects.
Industry Challenges
- Soil remediation expertise:Brownfield site preparation requires specialized geotechnical capabilities that remain scarce in India's tier-2 contractor base.
- Beneficiary verification bottlenecks:India's Aadhaar-linked income certification delays subsidy disbursement and extends working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Affordable Housing Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Cost Housing, Modular Homes, Prefabricated Units, Social Housing End User: First-Time Buyers, Low-Income Families, Non-Profit Organizations, Government Agencies Construction Method: Traditional Building, 3D Printing, Steel Frame, Eco-Friendly Techniques Funding Source: Public Grants, Private Investments, Microfinance, NGO Contributions |
| Companies Covered | China Vanke Co., Ltd., China Resources Land Co., Ltd., Sunac China Holdings Limited, Seazen Holdings Co., Ltd., China Evergrande Group, New World Development Co. Ltd, Wheelock and Company, DLF India, Tata Housing Development Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Affordable Housing Market Trends and Innovations
Construction methodology and project financing models are diverging across the Asia-Pacific region as labor availability, land tenure systems, and subsidy architectures create distinct innovation pathways.
Building Information Modeling software is digitizing design-to-fabrication workflows for prefabricated housing producers. Malaysian and Thai developers are adopting cloud-based coordination platforms to synchronize factory panel production with just-in-time site delivery. This compression of information latency is digitizing supply chain orchestration and reducing on-site inventory holding costs.
India's Ministry of Housing and Urban Affairs is tightening PMAY carpet-area compliance verification through mandatory geo-tagged construction progress photography. Developers now embed digital audit trails into project management systems to satisfy disbursement checkpoints. Smaller regional builders lacking enterprise IT infrastructure face exclusion from subsidy-accessible contracts.
First-time buyers in Vietnam and Indonesia are gravitating toward rent-to-own structures that bridge informal rental tenure and formal mortgage eligibility. Property technology platforms are intermediating these hybrid contracts, substituting for traditional bank origination channels. Ho Chi Minh City and Surabaya exhibit the highest conversion rates from rental to ownership under these arrangements.
Asia-Pacific Affordable Housing Market Segmentation
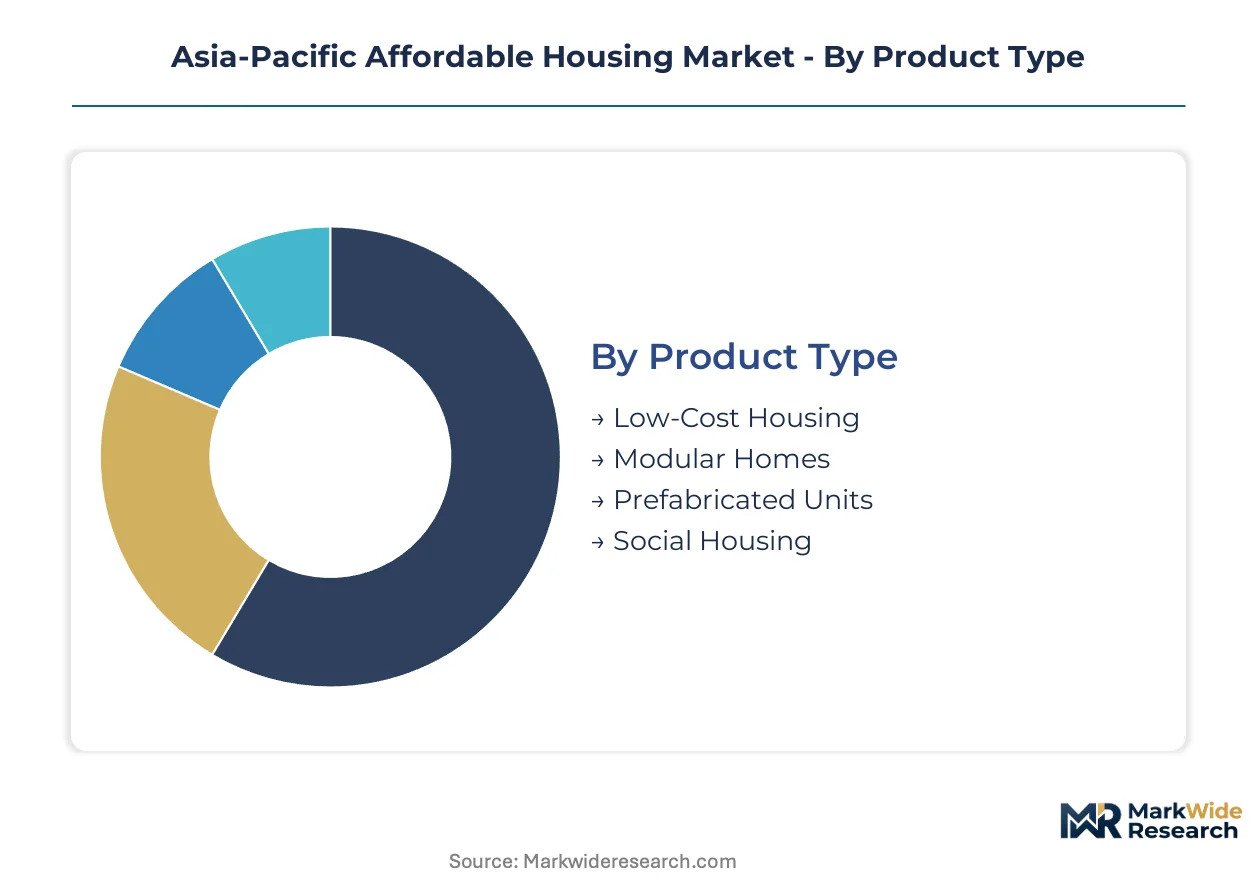
Segmentation in the Asia-Pacific affordable housing market reveals how subsidy eligibility, construction economics, and beneficiary profiles shape project feasibility across divergent national frameworks. Developers must align product specifications with funding source requirements to unlock capital access.
Product Type:
Mature mass-housing formats coexist with emerging factory-built systems as labor costs and delivery timelines reshape competitive positioning.
- Low-Cost Housing:Load-bearing masonry and reinforced concrete frames achieving 20-25 MPa compression strengths dominate India's tier-2 urban corridors where India's Ministry of Housing and Urban Affairs enforces PMAY carpet-area caps. Demand concentrates among households earning 30-50% of area median income in cities like Indore and Lucknow where land assembly costs remain sub-$50 per square meter.
- Modular Homes:Factory-based panel production cuts on-site labor dependence and compresses build cycles from eighteen to ten months, addressing skilled mason shortages in Vietnam and Thailand. Ho Chi Minh City developers are converting industrial peripheries into modular production zones to serve peri-urban settlements.
- Prefabricated Units:Pre-cast concrete and steel composite systems enable rapid deployment in Philippine disaster-relief zones and Indonesian tsunami-prone coastlines.
- Social Housing:State-subsidized rental stock with income-linked tenure security serves China's urban migrant populations under Ministry of Housing and Urban-Rural Development rental quotas.
Low-cost housing handles the majority of throughput; modular homes are gaining share fastest as Southeast Asian labor scarcity deepens.
End User:
Beneficiary verification complexity and subsidy access tiers fragment addressable demand across income strata and institutional channels.
- First-Time Buyers:Young urban households in Vietnam and Indonesia leverage rent-to-own platforms to bridge informal rental tenure toward formal mortgage eligibility, with Surabaya and Ho Chi Minh City showing highest conversion rates.
- Low-Income Families:India's Aadhaar-linked income certification determines PMAY interest subvention access, though verification bottlenecks extend working capital cycles for developers serving this segment.
- Non-Profit Organizations:Habitat for Humanity and local NGOs deploy volunteer labor to reduce per-unit construction costs below $100 per square meter in rural Myanmar and Laos.
- Government Agencies:China's state-owned enterprises control prime urban land banks, limiting private developer participation in affordable housing-zoned sites.
Low-income families anchor volume absorption; first-time buyers are expanding most quickly through fintech-enabled origination channels.
Construction Method:
Technology maturity curves diverge sharply between labor-intensive traditional methods and capital-intensive automated systems.
- Traditional Building:On-site masonry and cast-in-situ concrete persist across India's tier-2 contractor base where soil remediation expertise remains scarce and brownfield preparation delays project starts.
- 3D Printing:Contour crafting of cementitious mixtures achieves wall deposition rates of 10 square meters per hour in Chinese pilot projects, though material certification lags behind equipment capability.
- Steel Frame:Light-gauge galvanized systems enable seismic-resistant construction in Japan's affordable rental stock and Philippine fault-line corridors.
- Eco-Friendly Techniques:Compressed stabilized earth blocks and bamboo-composite panels reduce embodied carbon in Indonesian and Vietnamese greenfield townships seeking carbon credit monetization.
Traditional building commands current deployment scale; 3D printing holds the steepest expansion trajectory as Chinese equipment costs decline.
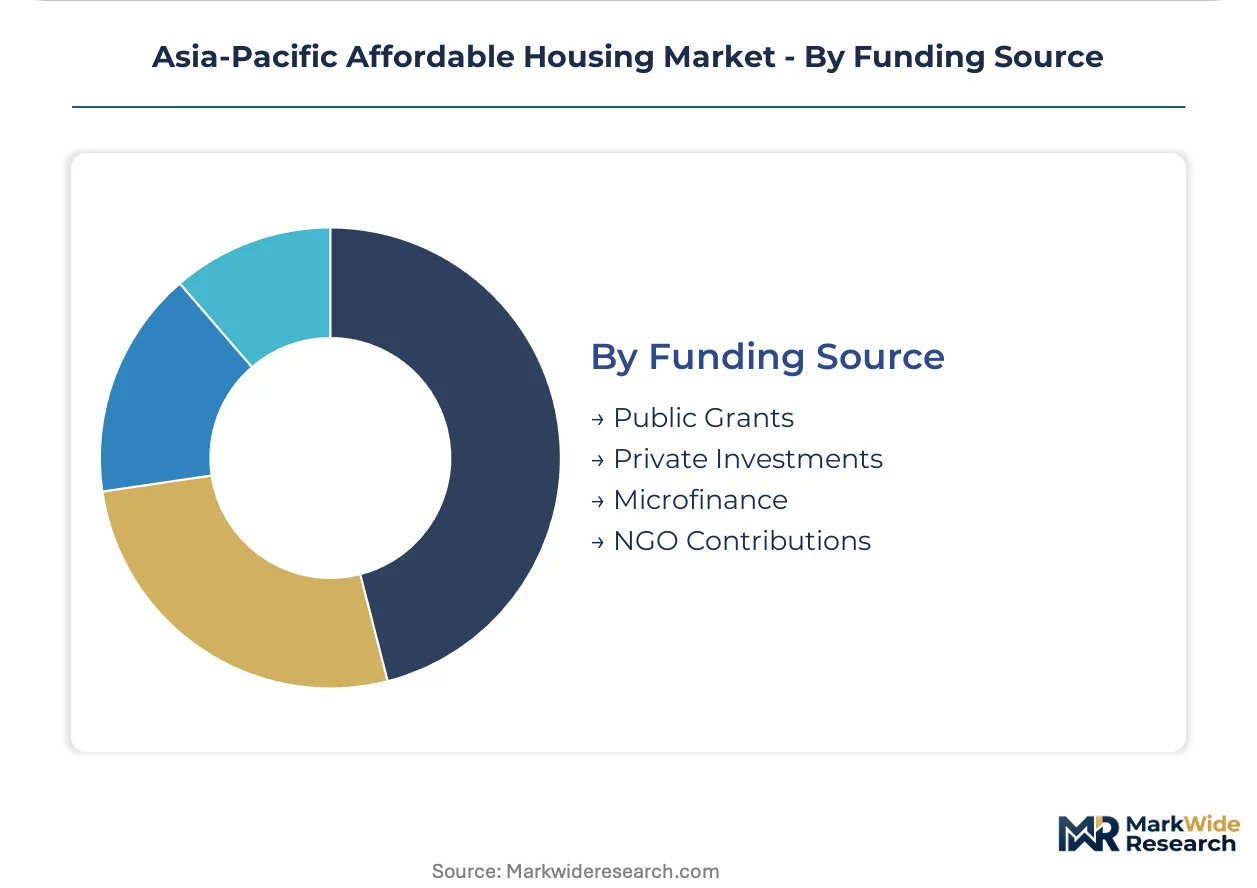
Funding Source:
Capital stack composition determines project velocity and beneficiary reach across public, private, and alternative finance channels.
- Public Grants:India's PMAY central subsidy scheme and China's rental housing mandates channel fiscal resources toward income-capped developments with prescribed unit specifications.
- Private Investments:Malaysian and Thai institutional investors deploy capital into build-to-rent affordable portfolios yielding 6-8% net operating income in Kuala Lumpur and Bangkok peripheral zones.
- Microfinance:Grameen-style rotating credit funds enable incremental home construction among Bangladesh's landless rural households outside formal banking reach.
- NGO Contributions:Bilateral development agencies and faith-based organizations pre-finance community land trusts in Pacific Island nations facing climate displacement.
Public grants dominate committed capital; microfinance is climbing the fastest as digital disbursement platforms reduce transaction costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity peaks in India's tier-2 urban corridors where subsidy-dependent buyers face absolute affordability ceilings, while Vietnam's emerging middle class shows greater elasticity for quality upgrades. China's state-controlled land allocation dampens developer margin pressure through below-market resettlement terms.
India
Low-income families in tier-2 cities like Indore and Lucknow drive absorption where land assembly costs remain sub-$50 per square meter. The Ministry of Housing and Urban Affairs enforces PMAY carpet-area caps and income eligibility criteria that shape product specifications. DLF India and Tata Housing Development Company Limited anchor supply in Delhi-NCR and Mumbai peripheral zones through integrated township models.
China
Urban migrant populations sustain rental housing demand under Ministry of Housing and Urban-Rural Development quotas embedded in mixed-income developments. State-owned enterprises control prime urban land banks, constraining private developer site access. China Vanke Co., Ltd. leverages municipal relationships in Shenzhen and Shanghai to secure contiguous parcels at favorable resettlement terms.
Vietnam
First-time buyers in Ho Chi Minh City gravitate toward rent-to-own structures bridging informal tenure toward mortgage eligibility. Municipal rezoning of industrial peripheries unlocks contiguous parcels for mass housing development. Developers are converting Binh Duong and Dong Nai industrial zones into modular production corridors serving peri-urban settlements.
Indonesia
Jakarta's peripheral satellite cities remain underpenetrated by formal affordable housing supply, presenting greenfield development potential. The national government maintains subsidy frameworks for low-income formalization though disbursement velocity lags demand. Surabaya exhibits the highest rent-to-own conversion rates as property technology platforms intermediate hybrid contracts.
Philippines
Disaster-relief zones and fault-line corridors require seismic-resistant construction methods for affordable rental stock. Prefabricated units enable rapid deployment in tsunami-prone coastlines where infrastructure gaps persist. Cebu and Davao clusters attract modular-microgrid convergence integrating factory-built systems with decentralized solar-plus-storage.
Asia-Pacific Affordable Housing Market Competitive Landscape
Capability concentration sits with developers possessing municipal land-bank relationships and in-house soil remediation expertise; scale advantage sits with diversified conglomerates spanning multiple city clusters. The market structures around three tiers: state-linked land aggregators, integrated township specialists, and regional contractors dependent on third-party site preparation. Strategic differentiation flows through backward integration into land assembly and cross-subsidy generation from commercial bundling.
Within the state-linked tier, China Vanke Co., Ltd. and China Resources Land Co., Ltd. occupy positions shaped by proximity to municipal planning authorities. Among India-based integrated developers, DLF India and Tata Housing Development Company Limited exemplify archetypes combining captive land reserves with commercial cross-subsidy mechanics. Sunac China Holdings Limited and Seazen Holdings Co., Ltd. represent scale-driven models operating across multiple provincial markets under China's rental housing quota framework.
| Leading Market Players |
|---|
| China Vanke Co., Ltd. |
| China Resources Land Co., Ltd. |
| Sunac China Holdings Limited |
| Seazen Holdings Co., Ltd. |
| China Evergrande Group |
| New World Development Co. Ltd |
| Wheelock and Company |
| DLF India |
| Tata Housing Development Company Limited |
| Others |
Pricing and Supply Chain Analysis
China's rebar and cement production clusters anchor input cost volatility that compresses fixed-price contract margins for developers locked into subsidy-capped selling prices across India and Southeast Asia. This upstream concentration forces margin pools toward early-stage land assembly and site preparation capabilities rather than pure construction execution.
Pricing Analysis
After-sales service revenue from maintenance contracts and facility management drives lifetime value capture in affordable housing portfolios. Three-tier pricing structure across premium, standard, and economy levels segments buyers by income eligibility and carpet-area compliance, with India's PMAY subsidy tiers creating rigid price ceilings. Cost compression in standard-tier units intensifies because rebar and cement price swings erode developer margins on fixed-price contracts. Low-income families in tier-2 Indian cities exhibit highest price sensitivity, while Vietnam's emerging middle-class buyers show greater elasticity for quality upgrades.
Supply Chain Analysis
Extended payment terms from Chinese state-owned cement producers and supply-chain finance facilities from Indian NBFCs shape working capital cycles across the value chain. Factory-based panel production draws from China, Thailand, and Vietnam manufacturing bases, with prefabricated systems resting on steel composite inputs, pre-cast concrete, and engineered timber. Single-source vulnerability concentrates in Chinese rebar supply for Southeast Asian markets. Distribution runs through municipal land-bank relationships in China and third-party site preparation contractors in India's tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific affordable housing sits in early-cycle expansion as India's PMAY subsidy scheme accelerates formal housing access for low-income urban households. Penetration remains below 40% of addressable demand in Indonesia's peripheral satellite cities and Philippine peri-urban settlements.
For Market Incumbents: Harden municipal land-bank relationships to secure contiguous parcels at below-market resettlement terms before rezoning announcements. Deepen backward integration into in-house soil remediation and infrastructure provisioning to reduce third-party dependency and capture margin pools shifting toward early-stage development capabilities. For New Entrants and Emerging Players: Pursue rent-to-own platform partnerships in Vietnam and Indonesia where property technology intermediation bridges informal rental tenure toward formal mortgage eligibility. Jakarta's peripheral satellite cities present the most penetrable geography given underpenetrated formal supply. Lead with modular-microgrid convergence offerings that address infrastructure gaps in disaster-prone Philippine coastlines. For Investors and Strategic Acquirers: Capital is best deployed toward integrated township specialists possessing captive land reserves and commercial cross-subsidy mechanics across multiple city clusters. Long-term viability over the next decade hinges on exposure to subsidy-accessible contract pipelines and in-house site preparation capabilities. Monitor Aadhaar-linked income certification velocity as the inflection indicator for working capital cycle compression in Indian developments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Land Assembly | Captures margin pools shifting from construction toward early-stage site preparation and soil remediation. |
| Modular Production Zone Development | Ho Chi Minh City's industrial periphery conversion cuts build cycles and addresses skilled mason shortages. |
| Rent-to-Own Platform Partnership | Property technology intermediation in Surabaya and Jakarta bridges informal tenure toward mortgage eligibility. |
| Integrated Township Model Expansion | Commercial cross-subsidies bundled with residential units improve project feasibility under subsidy caps. |
| Microgrid Infrastructure Bundling | Decentralized solar-plus-storage integration addresses electricity gaps in Philippine peri-urban settlements. |
Research Methodology
Initial hypotheses were tested against primary input from project development executives, municipal planning officers, affordable housing finance specialists, and prefabricated systems manufacturers and refined through secondary validation. Construction progress databases, Ministry of Housing and Urban Affairs PMAY disbursement records, municipal rezoning notifications, and cement and rebar trade flow data anchored the evidence base. Bottom-up project pipeline enumeration triangulated against top-down subsidy allocation forecasts.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type, construction method, end-user income tier, and funding source dimensions. CAGRs were derived from fitted trend extrapolation moderated by policy velocity assumptions. India's Aadhaar verification bottleneck severity and China's rental housing quota enforcement rigor served as key forecast inputs.
Sensitivities concentrate around rebar and cement price volatility, municipal rezoning timeline shifts, and subsidy disbursement velocity revisions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Australia Flexible Office Space Market
Real Estate
Global Unified Facility Management Market
Real Estate
Facility Management Services Market
Real Estate
Bahrain Luxury Residential Real Estate Market
Real Estate
Saudi Arabia Luxury Residential Real Estate Market
Real Estate
Vietnam Facility Management Market
Real Estate
Warehousing Services Market
Real Estate
North America Office Real Estate Market
Real Estate
Egypt Residential Real Estate Market
Real Estate
Space Planning and Space Management Solutions Market
Real Estate
South Korea Residential Real Estate Market
Real Estate
France Facility Management Market
Real Estate
Puerto Rico Home Mortgage Finance Market
Real Estate
Real Estate Market
Real Estate
Spain Commercial Real Estate Market
Real Estate
Qatar Co-Working Office Spaces Market