
 Artificial Fur Market | 2026-2036
Artificial Fur Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Fur Market Intelligence
Biodegradable polymer engineering is reshaping artificial fur manufacturing, replacing petroleum-based acrylics with plant-derived alternatives that decompose within industrial composting cycles. ECOPPEL leverages European sourcing partnerships to control premium fiber supply chains from polymerization through weaving. PELTEX FIBRES SARL anchors North African production capacity, serving southern European garment makers with shorter lead times than Asian competitors. Shannon Fabrics specializes in ultra-plush pile constructions for home décor channels, differentiating through texture depth rather than price positioning.
Artificial fur denotes synthetic textile piles engineered from modacrylic, acrylic, or polyester fibers, tufted or knitted to mimic natural pelage density and directional lay, typically achieving 15-50 mm pile heights for apparel and 20-80 mm for upholstery applications. The material serves as a cruelty-free thermal insulator and aesthetic surface across fashion, interior, and performance costume industries. Faux Fur dominates volume throughput due to established acrylic supply chains and color-fast dyeing protocols, while Eco-friendly Fur captures expanding margin pools as REACH-compliant bio-based polymers achieve commercial scale. Within End User segments, Fashion Industry absorbs the largest share of high-value output, though Automotive seating applications are gaining specification traction among electric vehicle interiors seeking weight reduction alongside tactile luxury.
The European Chemicals Agency enforces REACH substance restrictions on persistent organic pollutants in synthetic fiber finishing, compelling reformulation of flame-retardant backcoatings across export-oriented mills. China's Ministry of Ecology and Environment implements GB standards for wastewater discharge from dye houses serving the Yangtze Delta artificial fur corridor, raising compliance costs for smaller weavers. California's Proposition 65 labeling requirements extend to textile products sold through US online retail channels, affecting direct-to-consumer distribution strategies. Stakeholders must monitor polymer feedstock volatility and regional extended-producer-responsibility mandates to calibrate capacity investments against shifting compliance burdens.
Market Dynamics
REACH substance restrictions from the European Chemicals Agency are forcing wholesale reformulation of flame-retardant backcoatings across synthetic fiber finishing operations, compelling mills to abandon legacy chemistries and recertify supply chains under compressed timelines.
Growth Catalysts
- EU Green Deal animal-welfare mandates:Luxury fashion houses in Milan and Paris now specify synthetic pelts for ready-to-wear collections, eliminating natural fur from seasonal lines to preempt compliance penalties.
- Biodegradable polymer engineering:Plant-derived fiber alternatives that decompose within industrial composting cycles are capturing specification share from petroleum-based acrylics among sustainability-weighted buyers.
- Yangtze River Delta manufacturing concentration:Integrated fiber-to-fabric operations in this Chinese cluster compress lead times and unit costs for global apparel brands seeking volume responsiveness.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and modacrylic polymer prices swing with crude oil derivatives, compressing margin visibility for converters lacking long-term supply contracts.
- Asian supply concentration risk:Overreliance on Yangtze Delta dye houses exposes brands to GB standard wastewater compliance disruptions and forced production pauses.
- Performance ceiling versus natural pelage:Synthetic piles still fail to match directional hair lay and thermal breathability of premium natural fur, limiting specification in ultra-luxury outerwear.
Strategic Opportunities
- Automotive seating specification:Electric vehicle interiors seeking weight reduction alongside tactile luxury are specifying artificial fur for headliner and seat applications previously served by leather or woven textiles.
- California Proposition 65 channel restructuring:Direct-to-consumer brands are building dedicated US fulfillment infrastructure to manage labeling compliance without ceding margin to third-party retailers.
- North African nearshoring:PELTEX FIBRES SARL and comparable operators in Morocco and Tunisia offer southern European garment makers shorter lead times than Asian competitors for mid-volume runs.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for REACH-compliant bio-based backcoatings concentrates in a handful of European research institutes, constraining scaling timelines for compliant mills.
- Extended producer responsibility capex burdens:EU member states are implementing textile take-back mandates requiring artificial fur producers to fund collection and recycling infrastructure.
- Dual certification complexity:Brands serving both EU and California markets must maintain parallel testing protocols for ECHA substance restrictions and Proposition 65 labeling, duplicating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Fur Market |
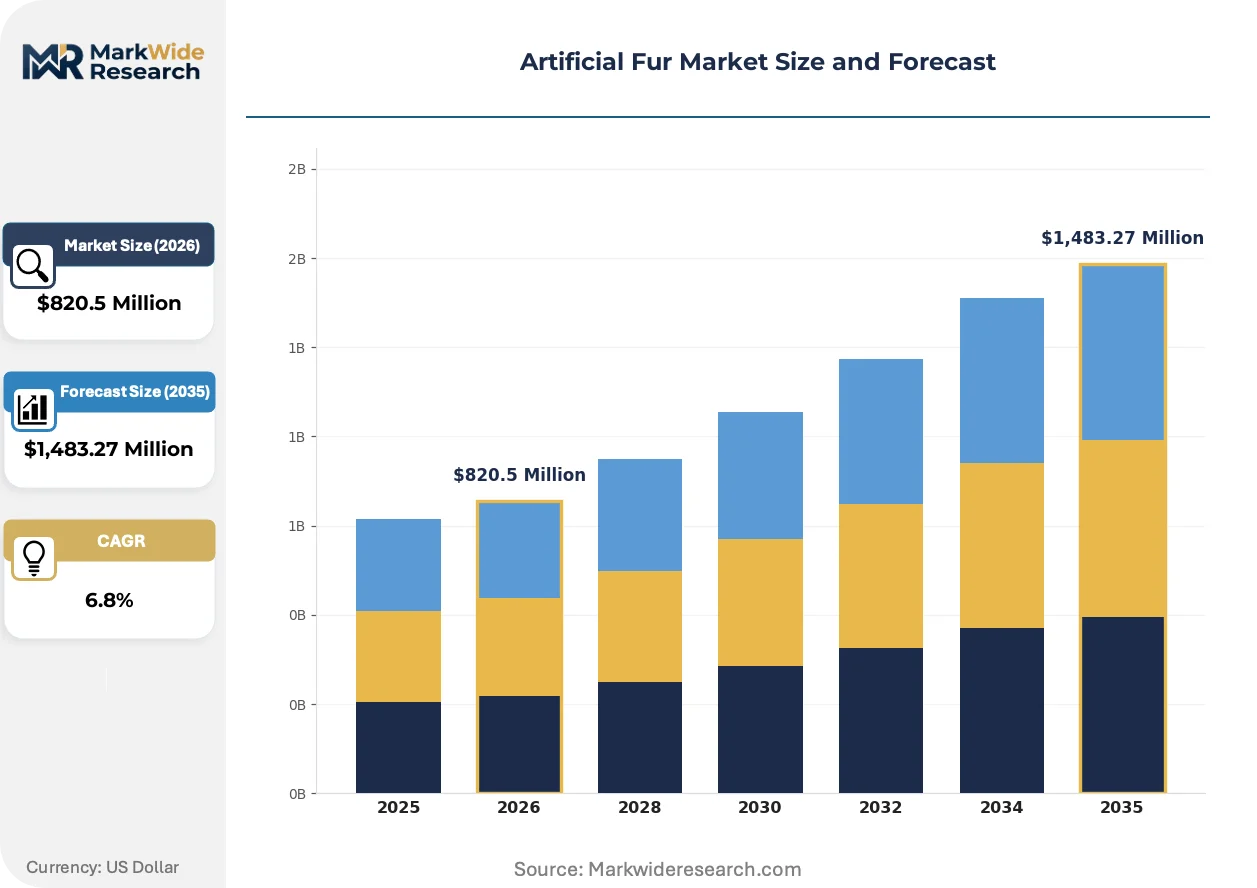
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faux Fur, Eco-friendly Fur, Recycled Fur, Luxury Fur End User: Fashion Industry, Home Decor, Automotive, Entertainment Application: Clothing, Upholstery, Accessories, Costumes Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | DealTask, PELTEX FIBRES SARL, Sommers Plastic Products, Aono Pile Co., Ltd., FIM, ECOPPEL, Texfactor Textiles, Ningbo Tenglong Fur, Shannon Fabrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Fur Market Strategic Shifts & Innovations
Artificial fur manufacturing is migrating from petroleum-dependent chemistries toward bio-engineered alternatives, while regulatory pressure on persistent organic pollutants intensifies and procurement patterns favor suppliers with demonstrated compliance transparency.
Plant-derived polymer engineering is migrating from pilot-scale demonstration to commercial textile production. Modacrylic fiber producers in the Netherlands and Germany are scaling fermentation-based polyesters that achieve comparable pile resilience to fossil-derived equivalents. Automotive seating specifiers at BMW and Mercedes-Benz are qualifying these materials for interior applications, compressing the certification timeline from laboratory validation to production release.
The European Chemicals Agency's 2023 update to REACH Annex XVII restrictions on halogenated flame retardants is compelling Turkish and Portuguese finishing mills to abandon brominated chemistries. Reformulated backcoatings using phosphorus-nitrogen synergists now dominate new product development pipelines. Home décor channels serving the UK and German markets are absorbing the steepest cost pass-throughs as Shannon Fabrics and comparable suppliers rebuild inventory with compliant materials.
Specification decisions are consolidating around suppliers with pre-certified compliance documentation. Fashion industry buyers in Paris and Milan now require ECHA registration dossiers and third-party compostability attestations before advancing to sampling phases. This behavioral shift favors ECOPPEL and comparable European-sourced operators over Yangtze Delta competitors lacking equivalent transparency infrastructure, compressing the supplier base for premium contract awards.
Artificial Fur Market Segmentation
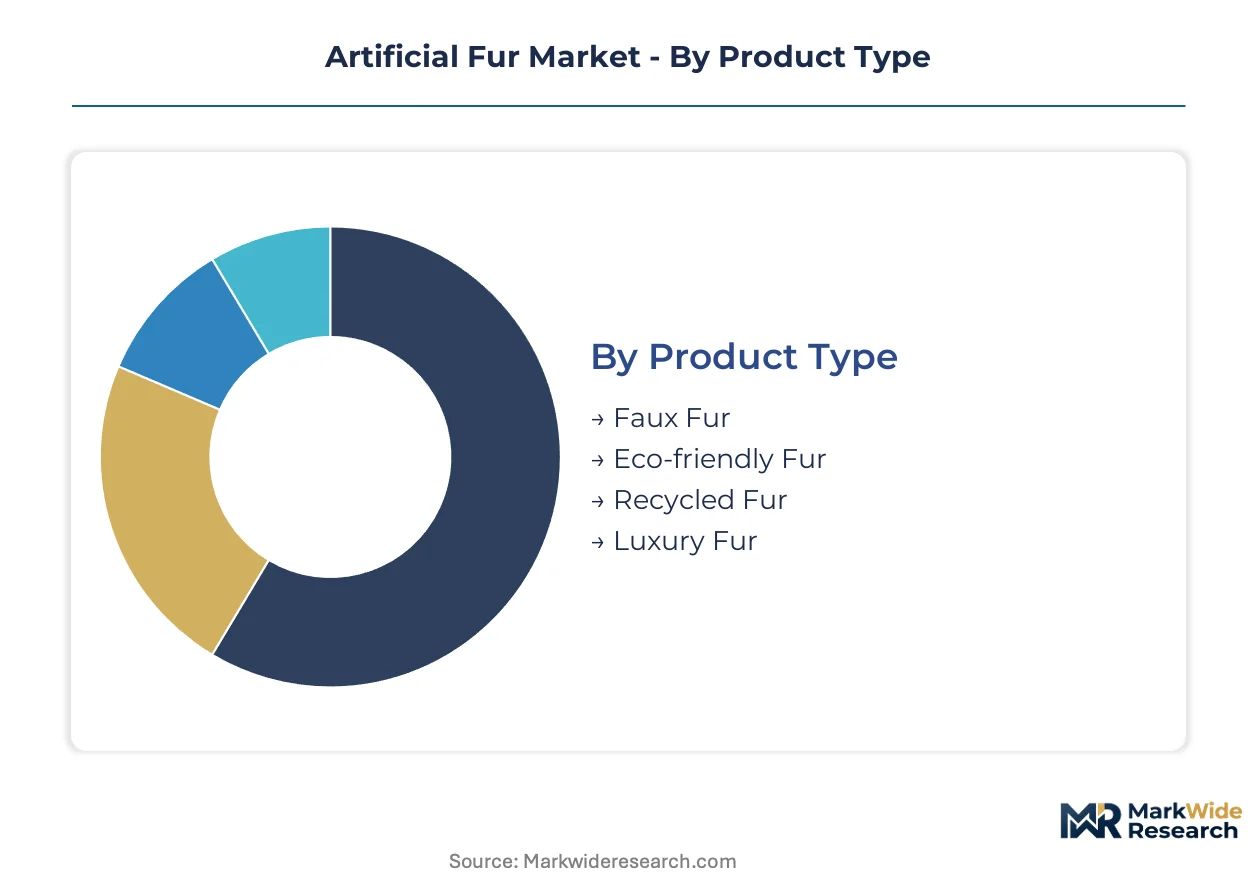
Artificial fur procurement patterns diverge sharply across product grades and end-use specifications. Buyers in Milan and Paris luxury houses demand certified bio-based fibers with full ECHA documentation, while Yangtze Delta mass-market converters prioritize acrylic supply security and dye-fastness guarantees.
Product Type:
After-sales service intensity escalates with fiber complexity and certification burden. Bio-based alternatives require technical support for composting infrastructure and traceability documentation, whereas commodity acrylics need minimal post-sale engagement beyond color matching.
- Faux Fur:Petroleum-derived acrylic and modacrylic fibers dominate volume production through established polymerization and tufting infrastructure. Fashion Industry buyers in the Yangtze River Delta specify these piles for ready-to-wear outerwear where cost positioning outweighs biodegradability mandates.
- Eco-friendly Fur:Plant-derived polymers engineered for industrial composting cycles command specification share among EU Green Deal-compliant brands. REACH-registered bio-based alternatives from Dutch and German fermentation facilities capture sustainability-weighted contracts from Paris and Milan houses seeking preemptive animal-welfare compliance.
- Recycled Fur:Post-consumer polyester and acrylic reclamation serves mid-tier home décor channels with lower purity requirements than apparel applications.
- Luxury Fur:Ultra-plush pile constructions with 40-80 mm heights and directional hair lay mimic premium natural pelage for boutique outerwear and accessories.
By volume, Faux Fur leads. By growth pace, Eco-friendly Fur is ahead.
End User:
Cost tier stratification separates specification-grade buyers from commodity converters. Premium fiber engineering concentrates in automotive and luxury fashion verticals willing to absorb REACH-compliant backcoating premiums, while home décor and entertainment segments prioritize pile density per dollar.
- Fashion Industry:Ready-to-wear and couture houses specify pile heights, color fastness, and compostability certifications before sampling. Milan and Paris buyers now require ECHA registration dossiers alongside third-party biodegradability attestations, compressing the qualified supplier base to European-sourced operators with transparency infrastructure.
- Automotive:Electric vehicle interior specifiers at BMW and Mercedes-Benz qualify artificial fur for headliner and seat applications where weight reduction and tactile luxury displace leather or woven textiles. Bio-based polymer certification timelines from laboratory validation to production release are compressing as these OEMs accelerate sustainability targets.
- Home Decor:Ultra-plush pile constructions for upholstery and throws prioritize texture depth and flame-retardant compliance over biodegradability, with UK and German markets absorbing steepest cost pass-throughs from reformulated phosphorus-nitrogen backcoatings.
- Entertainment:Performance costume and prop applications demand color range breadth and rapid sample turnaround rather than certification depth.
Fashion Industry absorbs the largest revenue share. Automotive is expanding most quickly as EV interior specifications proliferate.
Application:
Volume concentration tilts toward standardized pile constructions where dye house scale economies dominate. Custom-engineered directional lays and thermal-bonded backings for technical applications command narrower supplier pools with specialized tufting equipment.
- Clothing:Apparel applications span 15-50 mm pile heights with modacrylic and acrylic fiber dominance in mass-market outerwear. EU Green Deal animal-welfare mandates are eliminating natural fur from seasonal lines, redirecting specification toward synthetic alternatives with documented supply chain transparency.
- Upholstery:20-80 mm pile heights with flame-retardant backcoatings serve residential and contract furniture markets. REACH Annex XVII halogenated flame retardant restrictions are forcing Turkish and Portuguese finishing mills to rebuild inventory with phosphorus-nitrogen synergists, extending lead times for compliant material.
- Accessories:Collars, trims, and bag linings demand color-matching precision and shorter production runs than garment-scale orders.
- Costumes:Theatrical and film production applications prioritize rapid availability and theatrical wash durability over long-term pile resilience.
Clothing maintains volume leadership. Upholstery faces the steepest compliance-driven cost restructuring.
Distribution Channel:
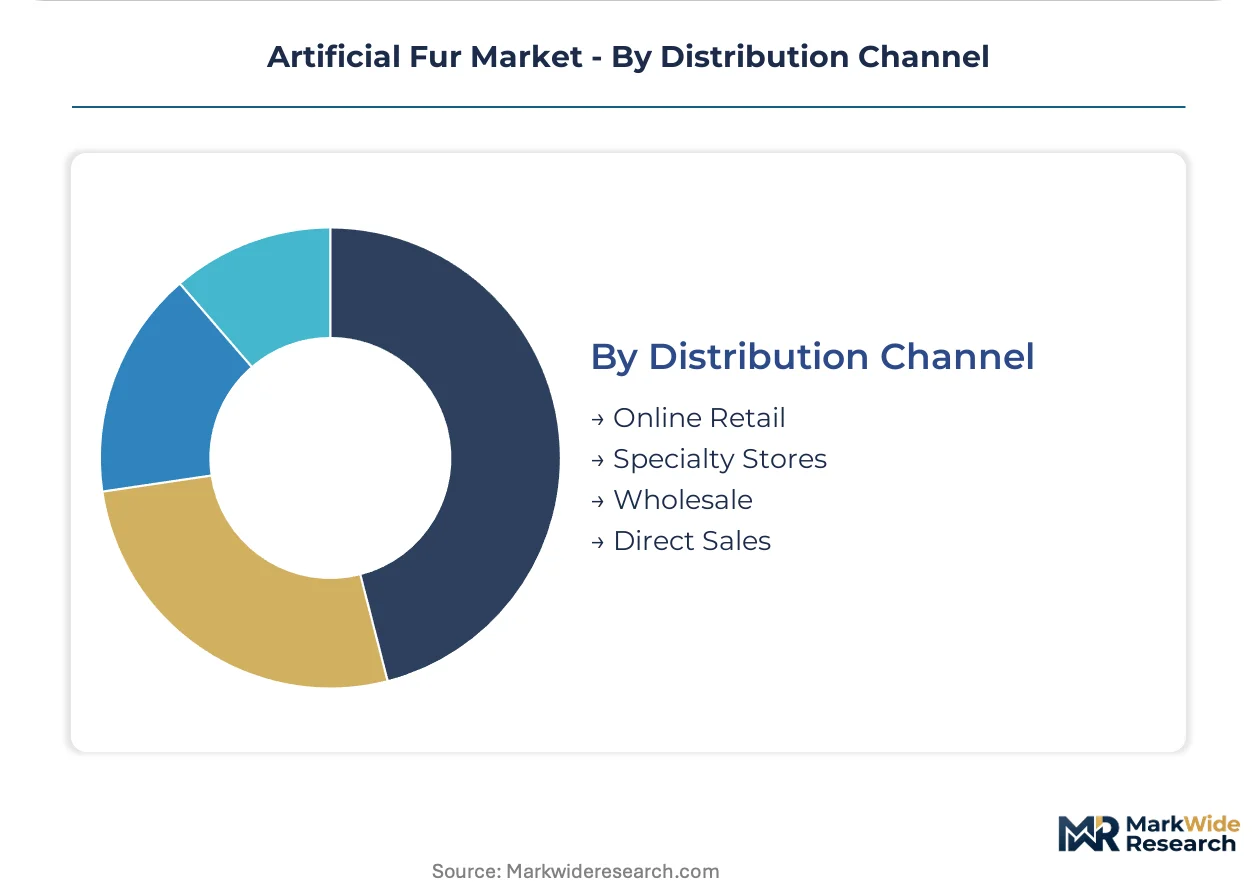
Margin structure varies with certification handling and fulfillment infrastructure intensity. Direct and specialty channels absorb documentation burdens for REACH and California Proposition 65 compliance, while wholesale and online retail compete on price transparency and logistics speed.
- Online Retail:Direct-to-consumer brands are building dedicated US fulfillment infrastructure to manage Proposition 65 labeling compliance without ceding margin to third-party retailers. California's requirements extend to textile products sold through e-commerce channels, affecting inventory segmentation and packaging workflows.
- Specialty Stores:Boutique fabric retailers and luxury material showrooms in Paris, Milan, and London provide tactile sampling and technical consultation for high-specification buyers. These channels concentrate bio-based and recycled fiber assortments where certification storytelling supports price positioning.
- Wholesale:Volume converters in the Yangtze Delta supply global apparel brands through established fiber-to-fabric relationships with compressed lead times and unit cost advantages.
- Direct Sales:Automotive OEMs and major fashion houses contract directly with fiber producers and finishing mills for specification-controlled material with locked polymer formulations.
Wholesale channels move the highest volume tonnage. Online Retail is gaining specification share fastest as direct-to-consumer brands internalize compliance infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports synthetic fiber piles from the Yangtze River Delta to European luxury houses in Milan and Paris, establishing the dominant trade-flow corridor for artificial fur supply chains.
China
Yangtze River Delta dye houses supply volume throughput for global apparel brands seeking compressed lead times. The Ministry of Ecology and Environment enforces GB standards for wastewater discharge from finishing operations, raising compliance costs for smaller weavers. Shanghai and Suzhou host integrated fiber-to-fabric operations that serve mass-market converters with acrylic and modacrylic supply security.
Italy
Milan-based luxury fashion houses specify REACH-registered bio-based polymers for ready-to-wear collections eliminating natural fur. The EU Green Deal animal-welfare framework tightens compliance timelines for seasonal lines. Lombardy textile districts concentrate specification-grade finishing capacity for premium outerwear brands.
France
Paris couture buyers demand ECHA registration dossiers and third-party compostability attestations before sampling phases. The European Chemicals Agency's REACH Annex XVII restrictions on halogenated flame retardants compel reformulation of backcoatings. Lyon and Paris showrooms anchor the high-value procurement channel for certified synthetic pelts.
Germany
Automotive OEMs in Stuttgart and Munich qualify artificial fur for electric vehicle headliner and seat applications. BMW and Mercedes-Benz accelerate sustainability targets that compress bio-based polymer certification timelines. Bavaria hosts fermentation-based polyester research facilities scaling plant-derived alternatives to fossil-derived fibers.
United States
California Proposition 65 labeling requirements extend to textile products sold through direct-to-consumer e-commerce channels. Direct-to-consumer brands build dedicated US fulfillment infrastructure to manage compliance without ceding margin to third-party retailers. Los Angeles and New York Metro concentrate specialty fabric retailers serving tactile sampling demands for high-specification buyers.
Artificial Fur Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base stratifies between Yangtze Delta volume converters with fiber-to-fabric integration and European-sourced operators with transparency infrastructure. Three archetypes dominate: integrated Chinese manufacturers, REACH-compliant European specialists, and North African nearshoring operators. Competitive moves concentrate on M&A for polymerization capacity and strategic partnerships for bio-based feedstock security.
Among European-sourced operators, ECOPPEL anchors premium fiber supply chain control from polymerization through weaving. PELTEX FIBRES SARL occupies a position within the North African nearshoring tier serving southern European garment makers. Shannon Fabrics exemplifies the texture-depth specialist archetype for home décor channels. These three represent distinct competitive positioning vectors based on geographic sourcing, compliance infrastructure, and end-use specialization.
| Leading Market Players |
|---|
| DealTask |
| PELTEX FIBRES SARL |
| Sommers Plastic Products |
| Aono Pile Co., Ltd. |
| FIM |
| ECOPPEL |
| Texfactor Textiles |
| Ningbo Tenglong Fur |
| Shannon Fabrics |
| Others |
Cost & Logistics Intelligence
Shanghai-Rotterdam container freight corridors transmit cost volatility from Yangtze Delta dye houses directly into European landed costs, amplifying price spreads between REACH-certified bio-based grades and commodity acrylic piles while compressing margins for undifferentiated converters lacking long-term polymer offtake agreements.
Pricing Analysis
Acrylic polymer contracts indexed to crude oil derivatives dominate procurement between Yangtze Delta mills and European converters, with price differentiation separating REACH-registered bio-based tiers from standard modacrylic grades. Certification depth and compostability documentation command premiums from Milan and Paris buyers, while mass-market apparel converters absorb the steepest cost compression from petrochemical feedstock swings. Fashion Industry procurement teams show highest price sensitivity, whereas Automotive OEMs prioritize locked formulation supply over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for synthetic fiber distributors serving REACH-compliant markets. Raw material flows draw from petroleum-based acrylic polymerization in the Yangtze Delta, fermentation-based polyester research facilities in Germany and the Netherlands, and modacrylic fiber spinning in Turkey and Portugal. Single-source vulnerability concentrates in GB-standard wastewater-compliant dye houses. Distribution runs through integrated fiber-to-fabric operators for volume apparel, direct mill relationships for automotive specifiers, and specialty fabric showrooms for certification-intensive buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent artificial fur producers face sustained substitution pressure from advanced textile alternatives and bio-engineered leather analogues that threaten specification share in automotive and luxury fashion channels.
For Market Incumbents: Harden polymer supply security through backward integration into fermentation-based polyester production or captive offtake agreements with Dutch and German bio-polymer facilities. Deepen ECHA registration dossier libraries to preempt competitor certification challenges from emerging bio-based entrants. Prioritize locked-formulation contracts with BMW and Mercedes-Benz seating specification teams before rival materials achieve production qualification.
For New Entrants and Emerging Players: Build out North African finishing capacity in Morocco and Tunisia to capture southern European garment maker demand seeking shorter lead times than Yangtze Delta competitors. Target mid-volume ready-to-wear converters in Italy and Spain with REACH-compliant bio-based samples and transparent composting infrastructure documentation. Lead with technical support capabilities for wastewater compliance and backcoating reformulation.
For Investors and Strategic Acquirers: European-sourced operators with pre-certified transparency infrastructure represent the most defensible acquisition archetype as specification decisions consolidate around ECHA documentation. Long-term viability hinges on polymer feedstock diversification away from petroleum dependence. Watch for inflection signals in automotive OEM qualification timelines for plant-derived alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polymer Production | Fermentation-based polyester capacity in Bavaria and the Netherlands secures REACH-compliant feedstock against crude oil volatility. |
| ECHA Pre-Certification Investment | Registration dossier libraries compress sampling timelines for Milan and Paris luxury house procurement teams. |
| North African Finishing Capacity Expansion | Morocco and Tunisia facilities deliver shorter lead times to southern European garment makers than Yangtze Delta competitors. |
| Automotive OEM Direct Contracting | Locked-formulation agreements with BMW and Mercedes-Benz seating teams preempt rival material qualification. |
| Compostability Infrastructure Partnership | Industrial composting cycle documentation supports premium positioning for EU Green Deal-compliant brand mandates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade records, ECHA registration databases, and SEC filings from listed textile chemical producers. Primary interviews engaged polymerization plant managers, procurement leads at Milan and Paris fashion houses, automotive interior specification engineers, and distribution channel partners serving home décor markets. Secondary validation drew from Ministry of Ecology and Environment GB standard disclosures, EU Green Deal implementation documents, and California Proposition 65 regulatory updates. Bottom-up fiber production estimates and top-down end-use demand assessments were cross-referenced for triangulation.
Forecast inputs span product type segmentation across faux fur, eco-friendly fur, recycled fur, and luxury fur grades; end-use dimensions covering fashion industry, automotive, home décor, and entertainment applications; and geographic production clusters including the Yangtze Delta, Lombardy textile districts, and Bavarian research facilities. CAGRs were derived from regression analysis against polymer feedstock price indices, regulatory implementation timelines, and automotive qualification velocity. Industry-specific inputs incorporated REACH Annex XVII reformulation costs and electric vehicle interior content per vehicle trajectories.
Stress conditions across crude oil derivative volatility, ECHA substance restriction expansion, and Yangtze Delta wastewater compliance disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding bio-based polymer scale-up timelines and automotive OEM sustainability target acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles
Bangladesh Textile Manufacturing Market
Textiles
South America Cotton Market
Textiles
Polyester Strap for Manual Grade Market
Textiles
Bamboo Fibers Market
Textiles
Textile Staples Market
Textiles
Rolle Market
Textiles
Mercerized Cotton Market
Textiles
Medical Fabrics Market
Textiles
Europe Digital Clothing Market
Textiles
Europe Fabric Shavers Market
Textiles
Unbleached Twill Tapes Market
Textiles
Antibacterial Washcloth Market
Textiles
Non Woven Printing Machine Market
Textiles
Global Alpaca Fiber Market
Textiles
Cloth Cutting Machines Market
Textiles
Jute Market