
 Art Funds Market | 2026-2036
Art Funds Market Size, Share, and Industry Trends Forecast 2026-2036
Art Funds Market Insights
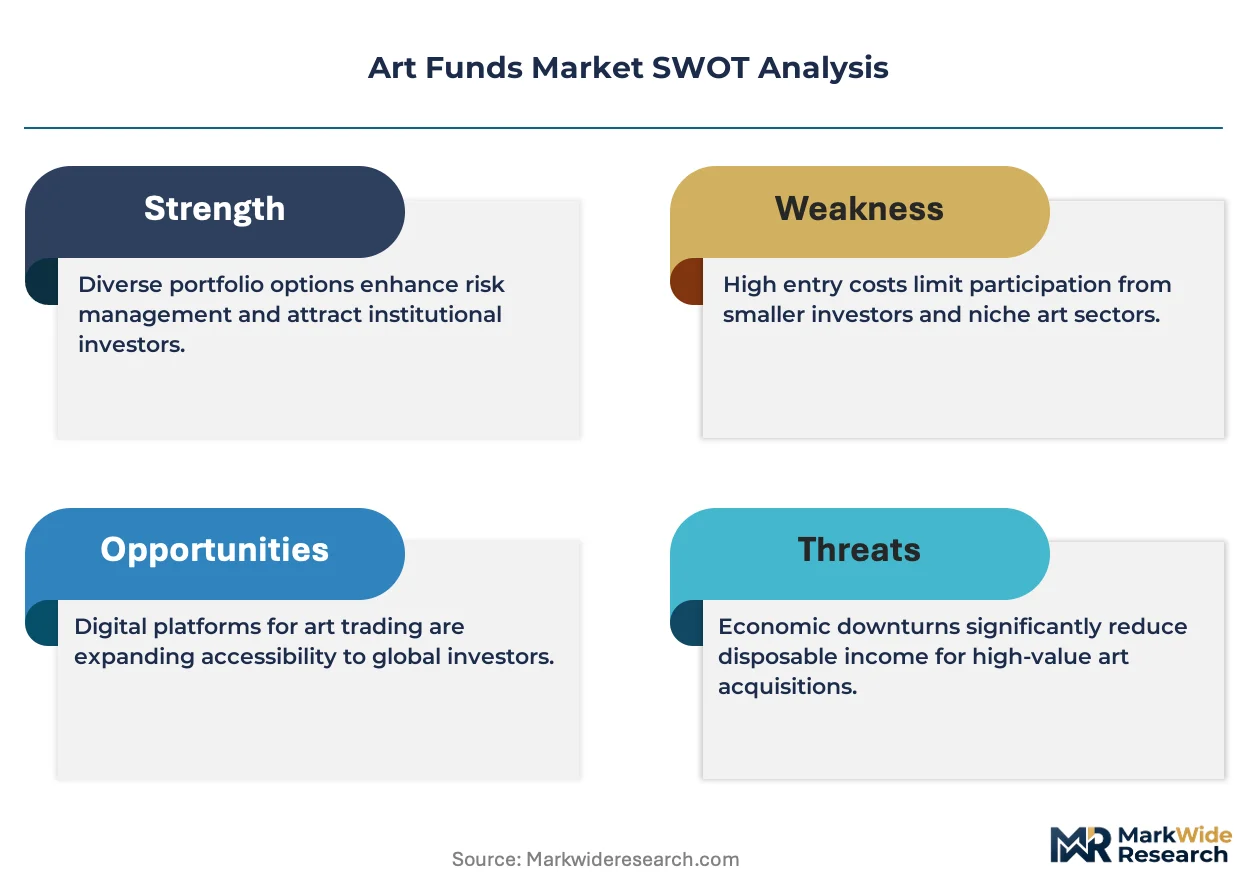
Asset-light securitization models is tilting competitive dynamics toward platforms that can pool fractional interests without bearing full acquisition risk. Masterworks leverages its first-mover infrastructure to dominate retail-accessible fractional blue-chip offerings. The Fine Art Group anchors institutional-grade fund structures with custody and appraisal rigor. Artemundi specializes in Old Masters and nineteenth-century segments where supply scarcity supports pricing power.
Art funds are pooled investment vehicles that acquire, manage, and dispose of fine art assets on behalf of shareholders, typically employing lock-up periods of five to ten years and charging management fees of one to two percent plus performance-based carried interest. Their primary commercial purpose is to deliver uncorrelated returns relative to equity and fixed-income benchmarks while offering portfolio diversification. Closed-ended structures lead the market due to their alignment with illiquid asset holding periods and defined exit timelines through auction or private sale. Digital art funds represent the fastest-growing segment, propelled by blockchain-based provenance verification and NFT-linked custody solutions. Income-oriented strategies remain mature, relying on lending against physical collateral rather than price appreciation.
The U.S. Securities and Exchange Commission regulates art fund offerings under the Investment Advisers Act, while the EU's AIFMD imposes leverage limits and transparency requirements on managers marketing to European professional investors. The UK's Financial Conduct Authority maintains parallel prudential standards post-Brexit, creating a tripartite compliance landscape for cross-border fund sponsors. Stakeholders must monitor evolving custody standards for digital assets and anticipate which jurisdictions will recognize tokenized fund interests as eligible retirement account holdings.
Market Dynamics
Fractional ownership platforms are compressing minimum investment thresholds, drawing retail capital into asset classes historically gated by million-dollar entry points and opaque dealer networks.
Growth Catalysts
- Blockchain Provenance Systems:Distributed ledger technology is eliminating authentication disputes that previously consumed 15-20% of transaction costs in secondary sales. Family offices now deploy capital with reduced due diligence overhead.
- EU AIFMD Passport Expansion:Harmonized marketing rules across member states enable Luxembourg-domiciled funds to access German and French institutional pools without duplicate regulatory filings.
- Wealth Transfer Demographics:Millennial heirs inheriting collections from post-war collectors are liquidating through fund structures rather than consigning to auction houses, feeding pipeline supply.
Market Restraints
- Illiquidity Lock-Up Mismatch:Five-to-seven-year fund terms conflict with investor expectations for quarterly redemption windows shaped by liquid alternatives.
- Appraisal Subjectivity:Absence of exchange-traded pricing forces reliance on auction comparables that lag market sentiment by 90-120 days.
- Storage and Insurance Cost Escalation:Climate-controlled warehousing in Geneva and Delaware freeports commands 2.5-4% of asset value annually, eroding net returns.
Strategic Opportunities
- Tokenized Fund Interests:Singapore's regulatory sandbox is permitting secondary trading of fractional art tokens on licensed exchanges, creating liquidity mechanisms absent in traditional structures.
- Emerging Artist Funds:Early-career segments offer acquisition multiples 60-80% below established blue-chip tiers, with holding periods compressing as auction houses accelerate primary market promotion.
- Art-Backed Lending Vehicles:Collateralized loan funds capture spread between 8-12% lending rates and 3-4% cost of capital, generating income without price-dependent exits.
Industry Challenges
- Specialized Custody Expertise Scarcity:Fewer than 200 professionals globally possess combined art handling and digital asset security credentials required for hybrid physical-NFT funds.
- Valuation Standardization Delays:ISO 23195 guidelines for fair value measurement remain in draft, forcing fund administrators to defend disparate methodologies to auditors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Art Funds Market |
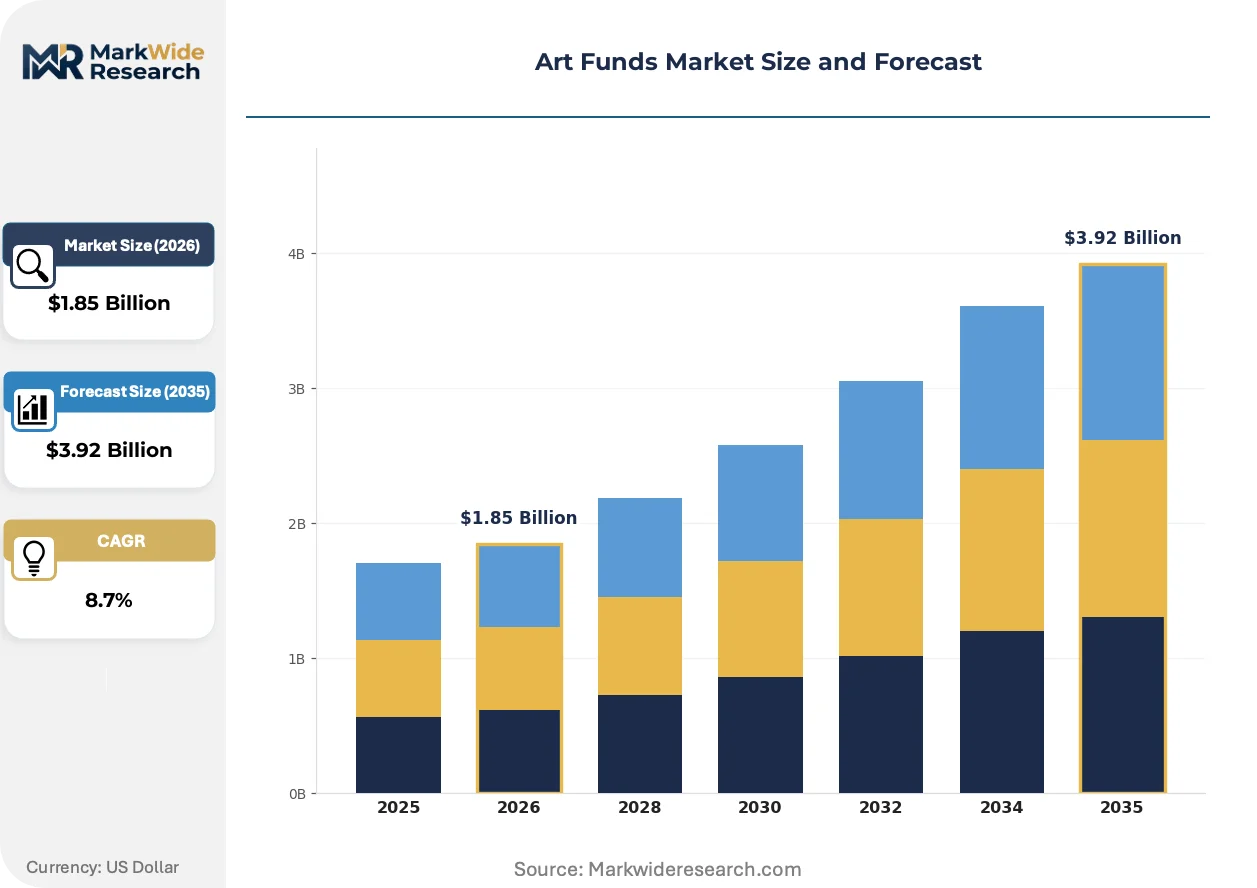
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Structure: Open-Ended, Closed-Ended, Hybrid, Interval, Unit Trust Investment Strategy: Growth-Oriented, Income-Oriented, Balanced, Index-Linked, Value-Based Investor Type: High Net Worth Individuals, Family Offices, Institutional Investors, Private Banks, Wealth Managers Asset Class: Contemporary Art, Modern Art, Classical Art, Digital Art, Sculptures, Prints |
| Companies Covered | Masterworks, Artemundi, The Fine Art Group, Yieldstreet, Arthena, Saatchi Art, Anthea Art Investments, MoneyMade, Dejia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Art Funds Market Trends and Innovations
Digital infrastructure is dissolving traditional intermediaries, enabling direct artist-to-investor relationships and programmable royalty streams that persist across secondary transactions.
Blockchain-based provenance registries are digitizing chain-of-title documentation for works exceeding $50,000 in value. Major auction houses and insurers are mandating digital certificates for consignment eligibility. This shift is digitizing due diligence workflows that previously required weeks of manual archival research.
The EU's Digital Operational Resilience Act imposes cybersecurity audit requirements on fund administrators handling tokenized assets. Luxembourg and Ireland are adapting AIFMD guidance to encompass smart contract governance. Digital art funds with European distribution are restructuring custody arrangements to satisfy these mandates.
Collector-investors are bypassing traditional advisory channels, sourcing allocation opportunities through direct platform relationships. Family offices now conduct 40% of art fund due diligence through proprietary research networks rather than wealth manager intermediation. This pattern concentrates in the United States, where regulatory familiarity supports self-directed investment vehicles.
Art Funds Market Segmentation
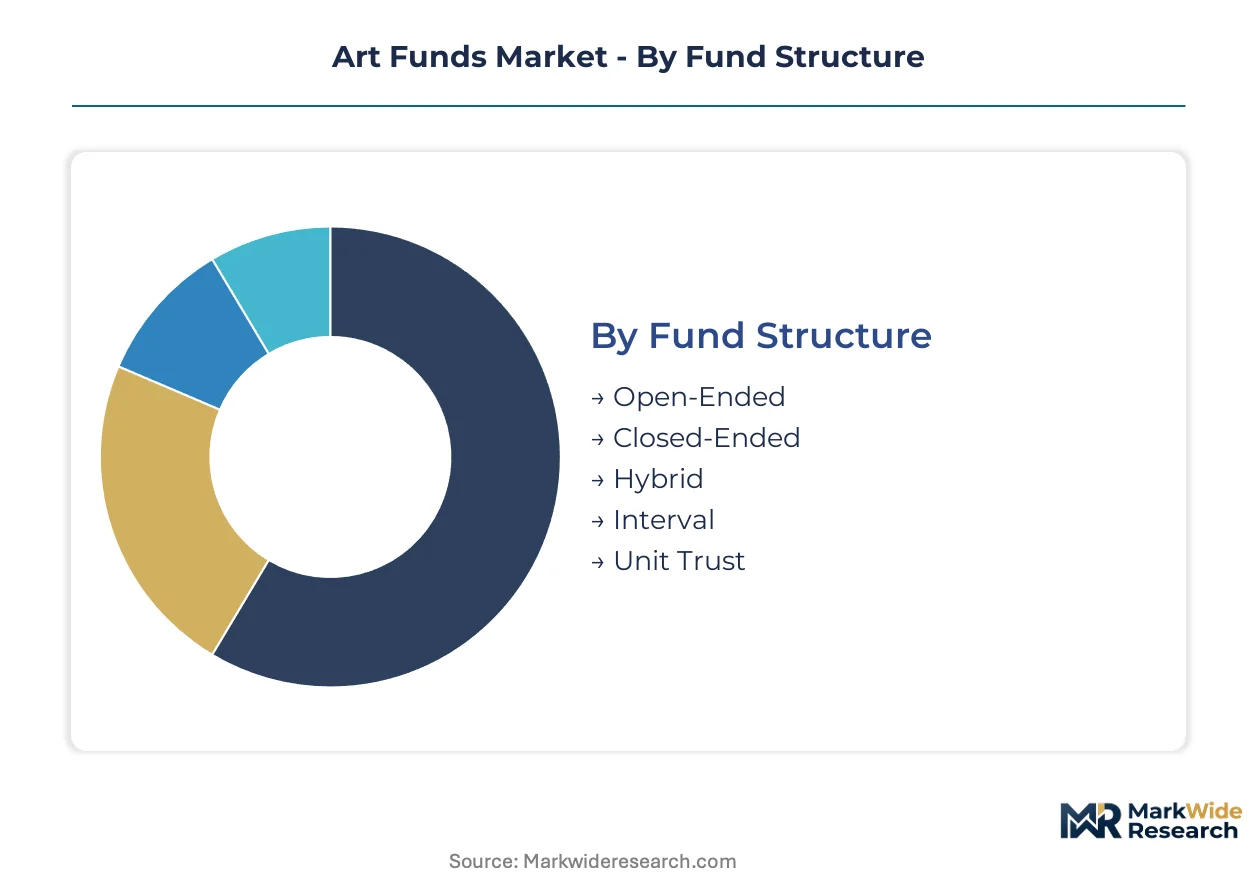
Segmentation in art funds reveals how capital deployment cycles, liquidity terms, and investor sophistication create distinct operational profiles. Each dimension shapes fee structures, custody requirements, and exit pathway design.
Fund Structure:
Cycle times range from perpetual open-ended vehicles to fixed-tenure closed-ended structures, with liquidity windows dictating acquisition and disposal rhythms.
- Closed-Ended:Fixed five-to-seven-year terms align with illiquid asset holding periods and defined auction-based exit timelines. Luxembourg-domiciled vehicles under AIFMD dominate European institutional allocations due to passport harmonization.
- Open-Ended:Perpetual structures with quarterly redemption windows attract retail capital through fractional platforms. Net asset value calculations face appraisal lag risks that erode investor confidence during volatile periods.
- Hybrid:Combines locked core capital with satellite liquidity sleeves. Singapore regulatory sandbox approvals enable secondary trading of tokenized hybrid interests.
- Interval:Periodic repurchase offers at 5-25% of net assets balance liquidity promises with illiquid underlying holdings. Delaware statutory trust formations concentrate in the United States.
- Unit Trust:Collective investment schemes with trustee oversight dominate UK retail distribution post-FCA Consumer Duty implementation.
Closed-ended structures anchor the volume base while hybrid formats gain share at the steepest rate.
Investment Strategy:
Cost tier differentiation separates capital appreciation plays from yield-generating collateralized lending vehicles.
- Growth-Oriented:Acquisition of blue-chip and emerging artist positions for price appreciation. Family offices in the United States deploy through Delaware limited partnerships to optimize carried interest treatment.
- Income-Oriented:Art-backed lending at 8-12% rates against physical collateral. Geneva freeport storage facilities support loan-to-value ratios for secured income streams.
- Balanced:Dual mandate combining appreciation targets with lending income. Luxembourg structures under AIFMD leverage this profile for insurance company allocations.
- Index-Linked:Performance tied to Artprice or Mei Moses indices. Institutional investors favor this for benchmark accountability.
- Value-Based:Distressed acquisition of underappreciated segments. Old Masters specialists exploit supply scarcity in European private collections.
Growth-oriented approaches command the largest capital commitments while income-oriented strategies expand most quickly among yield-focused allocators.
Investor Type:
Customer sophistication determines due diligence depth, fee negotiation leverage, and direct platform access versus intermediary dependence.
- Family Offices:Multi-generational wealth vehicles conduct proprietary research and negotiate bespoke fee structures. Millennial heirs liquidating inherited collections increasingly source fund allocations directly.
- High Net Worth Individuals:Retail-accessible fractional platforms serve minimum investments of $10,000-50,000. Masterworks dominates this segment through first-mover infrastructure.
- Institutional Investors:Pension funds and endowments require AIFMD-compliant structures with audited custody and quarterly reporting. German Spezialfonds channel institutional capital through Luxembourg vehicles.
- Private Banks:UBS and Credit Suisse wealth units structure art fund feeder products for ultra-high-net-worth clients. Swiss regulatory requirements shape product design.
- Wealth Managers:Independent advisors allocate client capital across diversified art fund portfolios. UK FCA authorization requirements limit distribution to qualified investors.
Family offices anchor sophisticated capital deployment while high net worth individuals represent the steepest expansion trajectory for fractional platforms.
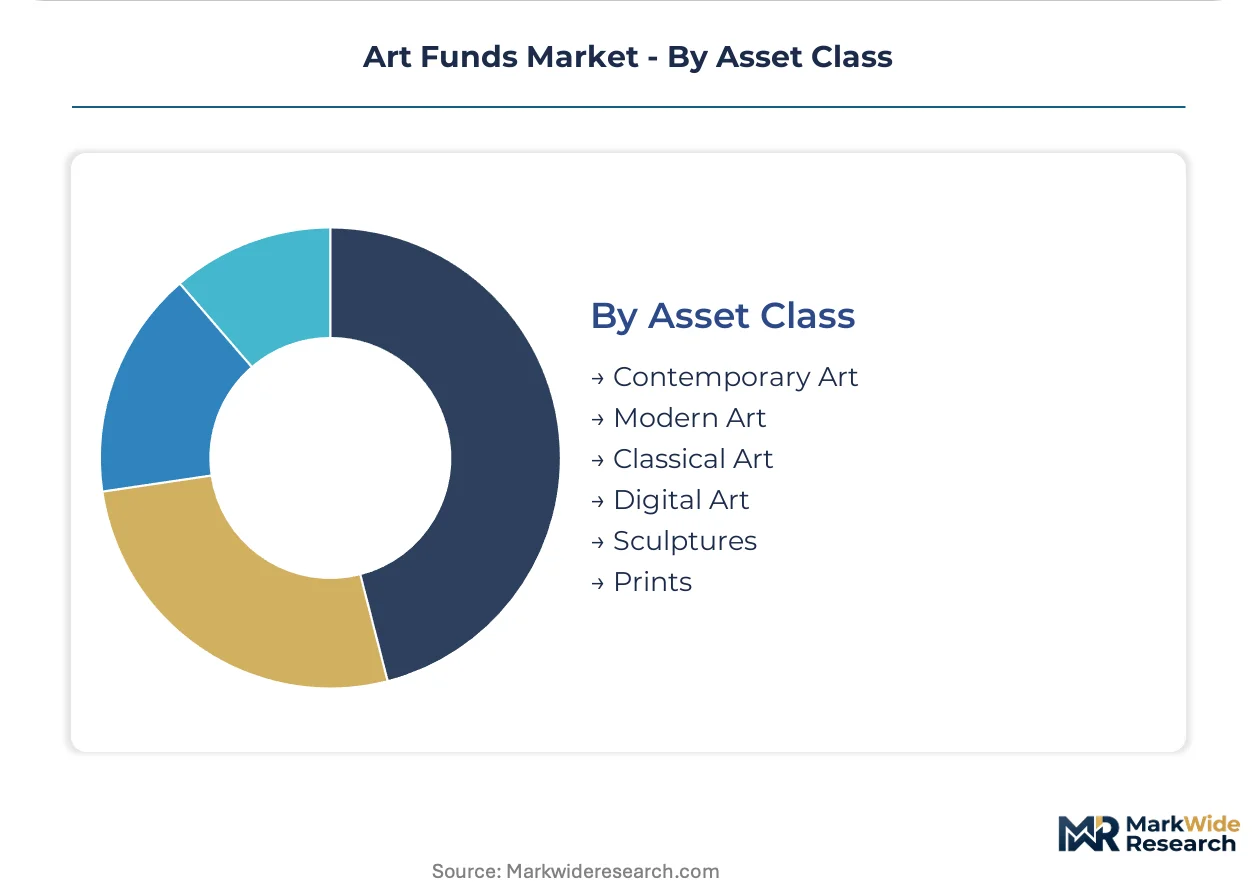
Asset Class:
Supply concentration and authentication complexity create tiered margin profiles across physical and digital categories.
- Contemporary Art:Post-war and living artist positions dominate auction turnover and price transparency. New York and London salesrooms establish benchmark pricing.
- Digital Art:NFT-linked custody and blockchain provenance verification enable fractional ownership at scale. Singapore and Dubai regulatory frameworks support tokenized fund structures.
- Modern Art:Impressionist and early twentieth-century segments attract established collector bases. Provenance research requirements favor funds with archival partnerships.
- Classical Art:Old Masters and antiquities face supply constraints and export restriction complexities. Artemundi specializes in this segment.
- Sculptures:Three-dimensional works command specialized handling, climate-controlled storage, and elevated insurance premiums. Geneva freeports offer consolidated custody solutions.
- Prints:Editioned works provide lower entry points with established authentication protocols. Institutional collections favor this for portfolio diversification.
Contemporary art anchors transaction volume while digital art climbs the fastest among emerging fund categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Art fund capital flows exhibit pronounced asymmetry between net-exporting jurisdictions with established auction infrastructure and net-importing markets building fractional ownership ecosystems. Regulatory arbitrage across Delaware, Luxembourg, and Singapore domiciles shapes cross-border fundraising velocity.
United States
Family offices in New York and Los Angeles deploy the majority of institutional capital into Delaware-domiciled limited partnerships. The SEC's Investment Advisers Act registration requirements create compliance moats that favor established managers. Miami's emergence as a wealth migration destination is spawning satellite fund administration clusters.
Luxembourg
German and French institutional allocators channel capital through Luxembourg vehicles leveraging AIFMD passport harmonization. The Commission de Surveillance du Secteur Financier imposes leverage limits that shape fund structure design. The financial center's custody infrastructure supports specialized art storage arrangements.
United Kingdom
Post-Brexit, the Financial Conduct Authority maintains parallel prudential standards that fragment cross-border marketing with EU vehicles. London's auction houses remain pricing benchmark setters for blue-chip segments. Mayfair-based family offices increasingly self-direct allocations through proprietary research networks.
Singapore
The Monetary Authority of Singapore's regulatory sandbox permits secondary trading of tokenized fractional interests on licensed exchanges. Wealth managers in Southeast Asia leverage this framework for retail-accessible products. The freeport zone offers consolidated custody solutions for regional collectors.
Switzerland
Geneva freeport storage facilities anchor collateralized lending vehicles serving ultra-high-net-worth clients. Swissmedic-equivalent cultural property regulations govern export documentation for Old Masters transactions. Zurich private banks structure feeder products with bespoke fee arrangements.
Art Funds Market Competitive Landscape
On the supply side, the industry is bifurcated between asset-heavy fund sponsors bearing full acquisition risk and asset-light platforms pooling fractional interests without balance-sheet exposure. Established players concentrate around closed-ended institutional structures, while venture-backed entrants dominate retail-accessible digital interfaces. Two strategic archetypes predominate: custody-anchored institutional specialists and technology-enabled fractional aggregators. Competitive intensity manifests through regulatory jurisdiction shopping and proprietary deal pipeline construction.
Within the fractional ownership tier, Masterworks exemplifies first-mover infrastructure scale, while Artemundi occupies a specialist position in supply-constrained Old Masters segments. The Fine Art Group anchors institutional-grade fund structures with integrated custody and appraisal capabilities. These three entities collectively represent the spectrum from retail democratization to bespoke family office service models.
| Leading Market Players |
|---|
| Masterworks |
| Artemundi |
| The Fine Art Group |
| Yieldstreet |
| Arthena |
| Saatchi Art |
| Anthea Art Investments |
| MoneyMade |
| Dejia |
| Others |
Pricing and Supply Chain Analysis
Geneva-Delaware freeport corridors anchor storage logistics for high-value physical art, with climate-controlled warehousing costs at 2.5-4% of asset value annually compressing net returns and forcing fund sponsors toward asset-light securitization models that shift acquisition risk to fractional investors.
Pricing Analysis
Family office buyers anchor fee negotiation leverage across art fund structures, with management fees of 1-2% plus carried interest creating tiered pricing stratification between institutional closed-ended vehicles and retail fractional platforms. Price differentiation rests on custody rigor, AIFMD compliance certification, and direct pipeline access versus platform-mediated sourcing. Pricing pressure intensifies in retail-accessible tiers as venture-backed entrants compete on minimum thresholds. High net worth individuals through fractional platforms exhibit greatest price sensitivity, while multi-generational family offices accept premium fee structures for bespoke service.
Supply Chain Analysis
Upstream artwork sourcing concentrates in United States, United Kingdom, and Switzerland auction infrastructure, with consignment pipelines drawing from post-war collector estate liquidations and millennial heir divestitures. Specialized inputs include archival provenance research, conservation-grade climate systems, and blockchain-based authentication protocols. Supply chain risk centers on single-source authentication disputes that previously consumed 15-20% of secondary transaction costs. Distribution runs through Delaware statutory trusts for US retail, Luxembourg AIFMD vehicles for European institutions, and Singapore sandbox-licensed exchanges for tokenized secondary trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Art fund market fragmentation creates entry niches as digital infrastructure dissolves traditional dealer intermediation and collector-investors bypass advisory channels for direct platform relationships.
For Market Incumbents: Pre-empt platform disintermediation by deepening proprietary pipeline relationships with post-war collector estates before millennial liquidation waves peak. Anchor defensive positioning through integrated custody-certification capabilities that emerging fintech entrants cannot replicate overnight. Prioritize AIFMD passport expansion to lock in German and French institutional allocations ahead of regulatory harmonization completion. For New Entrants and Emerging Players: Build out Singapore-regulated tokenized fund structures to capture secondary trading liquidity premiums absent in traditional closed-ended vehicles. Target emerging artist fund segments where acquisition multiples sit 60-80% below blue-chip tiers and auction house promotion cycles are compressing holding periods. Deploy direct-to-collector digital interfaces that bypass wealth manager intermediation channels where 40% of due diligence now occurs through proprietary networks. For Investors and Strategic Acquirers: Carve-out targets emerge from private bank art advisory divisions seeking to shed non-core fund administration capabilities amid post-Brexit FCA compliance cost escalation. Long-term viability favors hybrid physical-digital custody specialists with combined art handling and NFT security credentials. Monitor ISO 23195 fair value measurement guideline finalization as inflection signal for valuation standardization enforcement that will consolidate administrator market share toward compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Distributed ledger authentication eliminates 15-20% transaction cost drag for secondary sales. |
| AIFMD Passport Expansion | Luxembourg-domiciled vehicles access German institutional pools without duplicate regulatory filings. |
| Tokenized Fund Interest Launch | Singapore sandbox approvals enable licensed exchange trading for fractional liquidity mechanisms. |
| Emerging Artist Fund Development | Early-career segments offer 60-80% discount to blue-chip tiers with compressing promotion cycles. |
| Art-Backed Lending Vehicle Formation | Collateralized structures capture 8-12% lending spreads against Geneva freeport stored collateral. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fund managers, family office investment officers, wealth platform executives, auction house specialists, and regulatory compliance leads. Secondary validation drew from SEC Investment Advisers Act filings, EU AIFMD regulatory notices, FCA post-Brexit guidance updates, and Monetary Authority of Singapore sandbox approvals. Bottom-up pipeline analysis of fund formation filings triangulated against top-down wealth allocation survey data.
Calibration across the analysis window employed closed-ended term structure modeling, open-ended NAV calculation sensitivity testing, and hybrid tokenized liquidity scenario analysis. Segmentation dimensions spanned fund structure type, investment strategy mandate, investor sophistication tier, and asset class category. CAGRs were derived from rolling auction turnover benchmarks and fractional platform subscription velocity. Art-specific inputs included Mei Moses index correlation patterns and freeport storage cost inflation trajectories.
Practitioners should monitor AIFMD guidance evolution on smart contract governance and custody standard finalization for digital assets as early revision triggers. Cross-checking against Artprice and Artnet auction database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Proximity Mobile Payment Market
Investment Analysis and Financial Strategies
Russia Life and Non-Life Insurance Market
Investment Analysis and Financial Strategies
US Healthcare Finance Solutions Market
Investment Analysis and Financial Strategies
Saudi Arabia Retail Banking Market
Investment Analysis and Financial Strategies
Global Risk Management Software Market
Investment Analysis and Financial Strategies
Fuel Cards Market
Investment Analysis and Financial Strategies
Corporate Investigation Services Market
Investment Analysis and Financial Strategies
EMV Card Market
Investment Analysis and Financial Strategies
Russia Student Loan Market
Investment Analysis and Financial Strategies
Australia Gift Card and Incentive Card Market
Investment Analysis and Financial Strategies
Global Backstop Netting Systems Market
Investment Analysis and Financial Strategies
Europe Crowd Lending and Crowd Investing Market
Investment Analysis and Financial Strategies
Global Business Management Consulting Service Market
Investment Analysis and Financial Strategies
Business Analytics in Fintech Market
Investment Analysis and Financial Strategies
Marine Freight Insurance Market
Investment Analysis and Financial Strategies
Global Patient Safety and Risk Management Softwares Market