
 Apparel Software Market | 2026-2036
Apparel Software Market Size, Share, and Industry Trends Forecast 2026-2036
Apparel Software Market Analysis
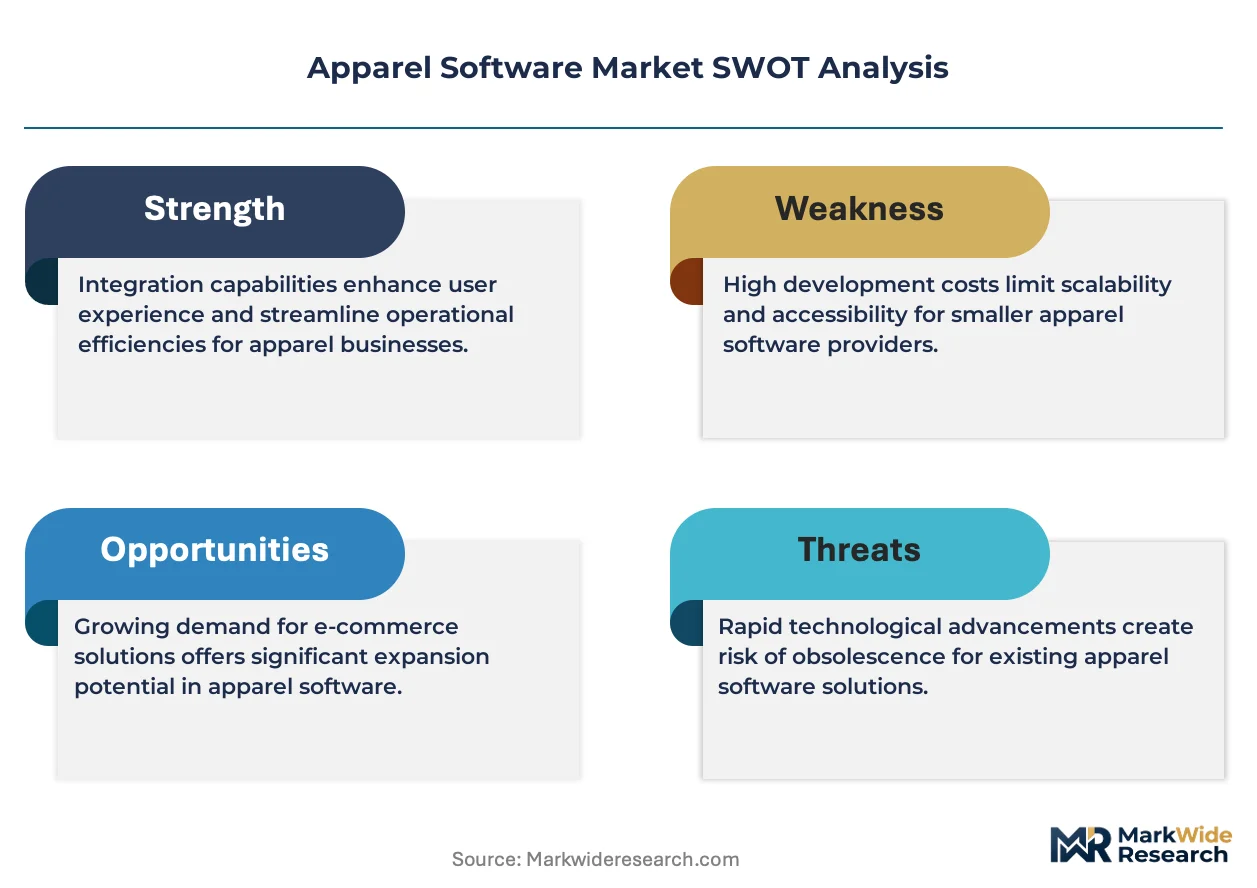
REACH compliance is expanding the cost-of-entry calculus for European apparel software procurement, forcing vendors to embed chemical traceability modules. Oracle Corporation leverages its database architecture to anchor enterprise-grade ERP deployments across multinational fashion houses. Fast React Systems specializes in production planning workflows that dominate Southeast Asian manufacturing hubs. AIMS 360 Apparel Software competes through vertical specialization in North American cut-and-sew operations.
Apparel software encompasses enterprise applications that manage design, sourcing, production, inventory, and distribution workflows for clothing and textile businesses. These platforms integrate CAD-based pattern engineering with real-time supply chain visibility, typically running on cloud-native architectures with API connectivity to factory floor IoT sensors. ERP Solutions and Inventory Management categories currently occupy the largest revenue pools, as manufacturers consolidate fragmented legacy systems. Cloud-Based and SaaS deployment modes represent the fastest-growing structural segment, driven by mid-market fashion brands seeking subscription flexibility without capital-intensive infrastructure.
The EU Green Deal and its digital product passport mandate, enforced through ECHA chemical registration protocols, compels software vendors to build material provenance tracking into core modules. The US EPA and California's Safer Consumer Products regulations further shape product compliance features for North American deployments. Stakeholders must evaluate whether their current platforms can absorb emerging regulatory data requirements without custom development overhead.
Market Dynamics
Cloud-native ERP architectures are compressing deployment timelines for mid-market fashion brands, while ECHA's digital product passport mandate forces material traceability into core software modules. This dual pressure is restructuring vendor competitive positions.
Growth Catalysts
- EU Green Deal digital passport requirements:ECHA enforcement is embedding chemical traceability as a standard feature rather than premium add-on.
- CAD-to-factory-floor integration:Pattern engineering tools with direct IoT sensor connectivity are shortening sample-to-production cycles.
- Southeast Asian manufacturing hub consolidation:Vietnam and Bangladesh production clusters are driving demand for localized planning modules.
Market Restraints
- Legacy system integration costs:On-premise ERP estates in established fashion houses require expensive middleware layers for cloud connectivity.
- Specialized talent scarcity:Software engineers with dual competency in textile engineering and API architecture command premium compensation.
- REACH compliance friction:ECHA chemical registration protocols create data validation bottlenecks for multi-country supply chains.
Strategic Opportunities
- India PLI scheme for textiles:Production-linked incentives are attracting greenfield manufacturing investments requiring modern software stacks.
- Generative AI pattern generation:Machine learning tools trained on historical design archives are compressing concept-to-sample timelines.
- Direct-to-consumer channel expansion:Micro-factory networks serving online-only brands need lightweight MES solutions.
Industry Challenges
- Cross-functional skill gaps:Supply chain analysts fluent in both ESG reporting standards and SQL querying remain scarce.
- Multi-tenant data residency:EU GDPR and China's data localization laws complicate cloud architecture choices for multinational deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apparel Software Market |
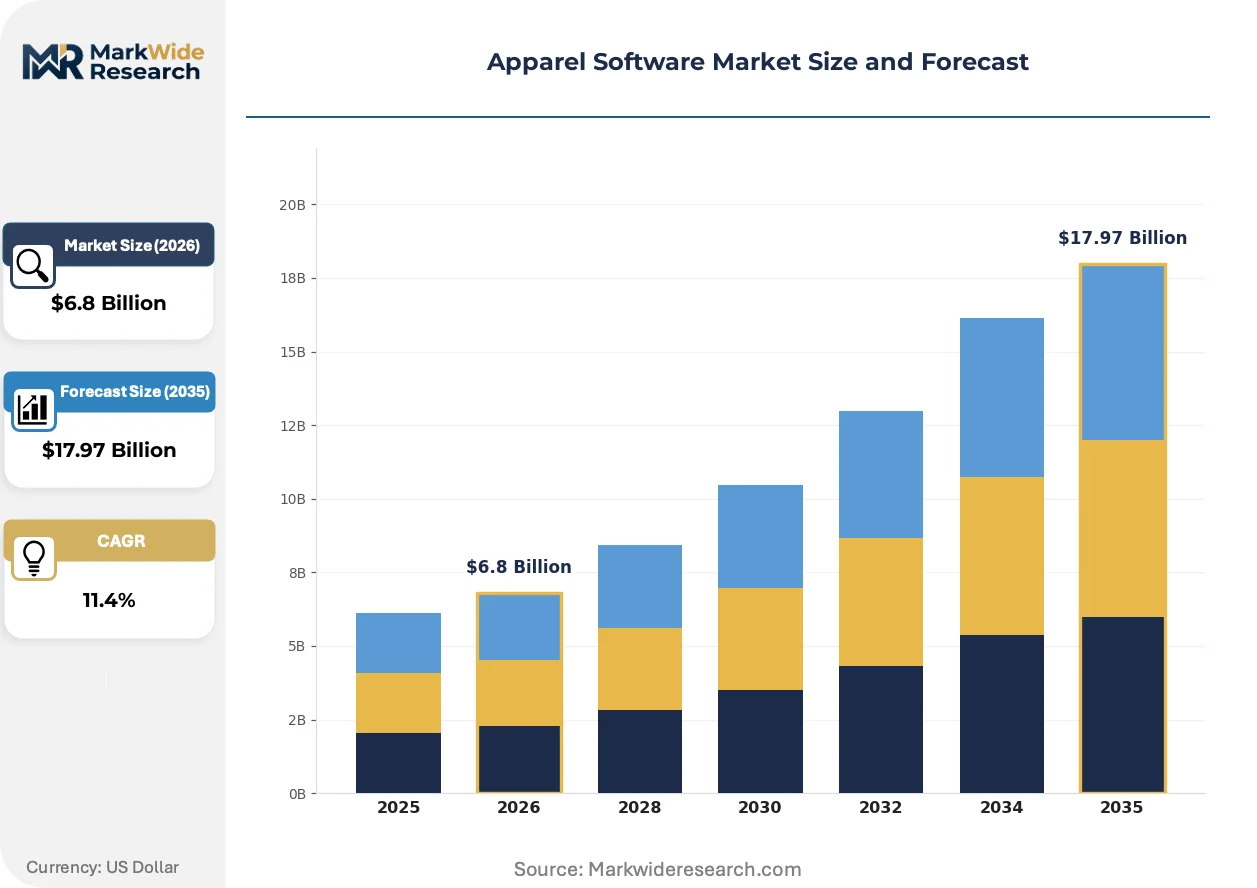
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Tools, ERP Solutions, Inventory Management, E-commerce Platforms End User: Fashion Brands, Manufacturers, Retailers, Wholesalers Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Feature: 3D Visualization, Reporting, Order Management, Supply Chain Optimization |
| Companies Covered | AIMS 360 Apparel Software, ApparelMagic, Apparel Business Systems, Fast React Systems, Aptean, Oracle Corporation, Systech Infovations Pvt. Ltd., Powersoft Computer Solutions Ltd., Computer Generated Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apparel Software Market Emerging Trajectories
Generative design algorithms and blockchain-based provenance tracking are converging to redefine how apparel software captures and validates supply chain data. These capabilities are shifting from experimental features to procurement requirements.
AI-powered pattern generation is expanding into technical design workflows previously reserved for human engineers. Fast-fashion retailers in Spain and Turkey are piloting these tools for rapid style iteration. The technology is expanding into quality prediction modules that flag construction risks before physical sampling.
REACH chemical registration protocols enforced by ECHA are mandating substance-level tracking from fiber origin to finished garment. Software vendors must now maintain updated restricted substance lists across multiple regulatory jurisdictions. European luxury houses are responding by consolidating supplier data into single-source-of-truth platforms.
Subscription pricing for SaaS modules is displacing perpetual license models among mid-tier brands with volatile order books. Buyers in Germany and California now prioritize OpEx flexibility over long-term TCO calculations. This shift is most visible among direct-to-consumer startups lacking balance sheet capacity for upfront capital deployment.
Apparel Software Market Segmentation
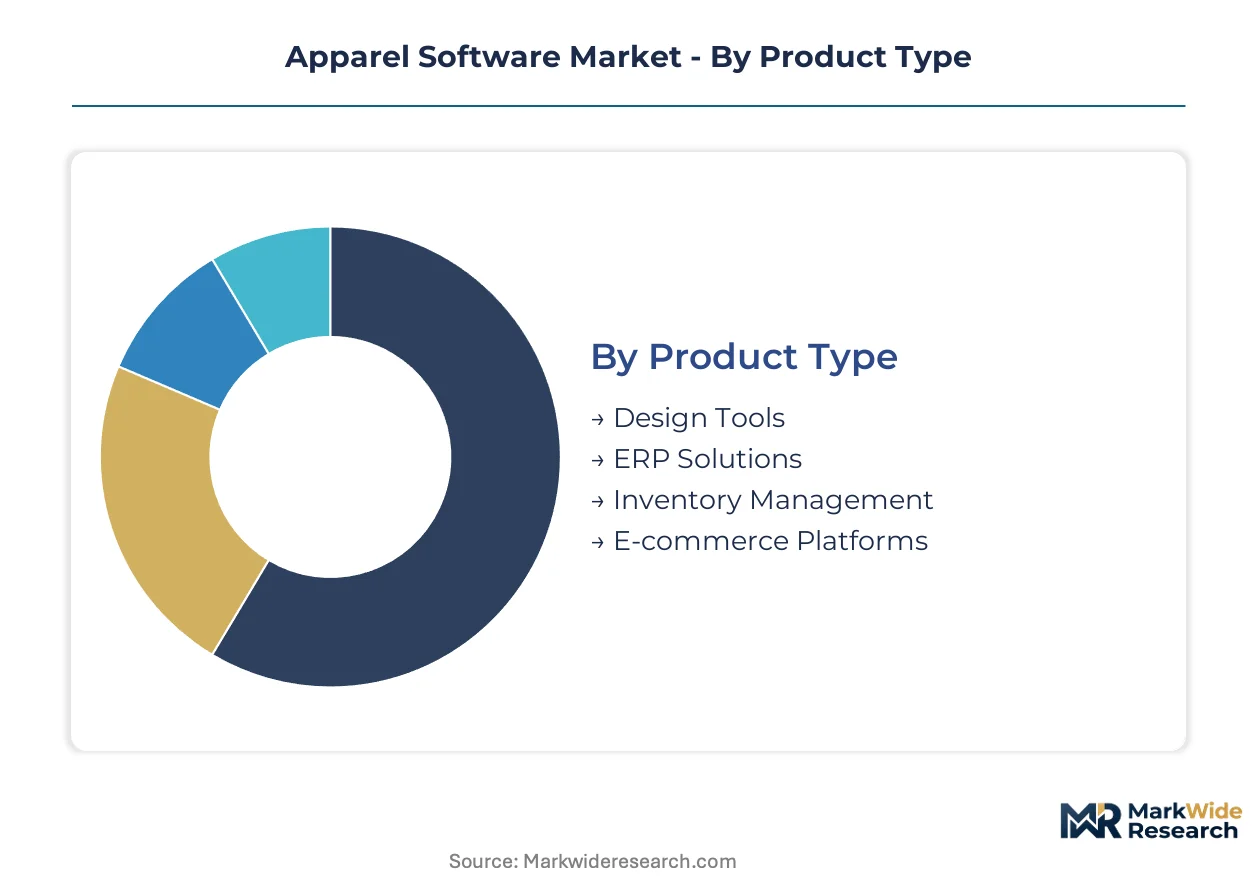
Apparel software procurement decisions hinge on matching regulatory complexity to platform capability. Buyers must map their ECHA, EPA, or BIS compliance burdens against specific feature modules and deployment architectures.
Product Type:
ECHA REACH registration requirements and California Safer Consumer Products mandates dictate which product categories require embedded chemical traceability versus standalone design functionality.
- ERP Solutions:Unified financial, procurement, and production planning systems anchor enterprise technology estates. German and US fashion houses consolidate fragmented legacy systems here to satisfy ECHA digital product passport data requirements and US EPA reporting obligations. Leading the category by volume: ERP Solutions. Growing fastest: Design Tools.
- Design Tools:CAD-based pattern engineering platforms with direct IoT sensor connectivity compress sample-to-production cycles. Spanish and Turkish fast-fashion retailers drive adoption for rapid style iteration.
- Inventory Management:Real-time stock visibility modules with API connectivity to warehouse management systems.
- E-commerce Platforms:Direct-to-consumer order orchestration tools with integrated payment processing and returns management.
ERP Solutions anchor procurement budgets, while Design Tools gain share fastest among mid-market brands seeking concept-to-sample compression.
End User:
Customer scale determines whether buyers prioritize OpEx flexibility through SaaS subscriptions or absorb capital-intensive on-premise deployments for data sovereignty.
- Manufacturers:Production planning and shop-floor control systems dominate procurement in Vietnam and Bangladesh manufacturing clusters. These buyers demand localized modules for cut-and-sew operations with real-time visibility into WIP inventory. Capturing the largest addressable spend: Manufacturers. Expanding most quickly: Fashion Brands.
- Fashion Brands:Cloud-native PLM platforms with generative AI pattern generation and blockchain provenance tracking. Direct-to-consumer channel expansion drives lightweight MES demand.
- Retailers:Omnichannel inventory synchronization and demand forecasting tools.
- Wholesalers:Bulk order management and B2B portal solutions with tiered pricing engines.
Manufacturers command the largest procurement budgets, while Fashion Brands represent the steepest expansion trajectory as direct-to-consumer channels proliferate.
Deployment:
Data residency constraints from EU GDPR and China's localization laws force architecture decisions that trade scalability against compliance control.
- Cloud-Based:Multi-tenant SaaS architectures with subscription pricing displace perpetual licenses among mid-tier brands with volatile order books. German and California buyers prioritize OpEx flexibility over long-term TCO calculations. Dominating current deployment decisions: Cloud-Based. Climbing the fastest: SaaS.
- SaaS:Modular subscription offerings allowing point-solution procurement without enterprise-wide commitments. Direct-to-consumer startups lacking balance sheet capacity drive adoption.
- On-Premise:Single-tenant installations for established fashion houses with legacy ERP estates requiring expensive middleware for cloud connectivity.
- Hybrid:Split architectures with sensitive design data on-premise and transactional workloads in cloud environments.
Cloud-Based deployments lead implementation volumes, while SaaS modules gain share fastest among capital-constrained entrants.
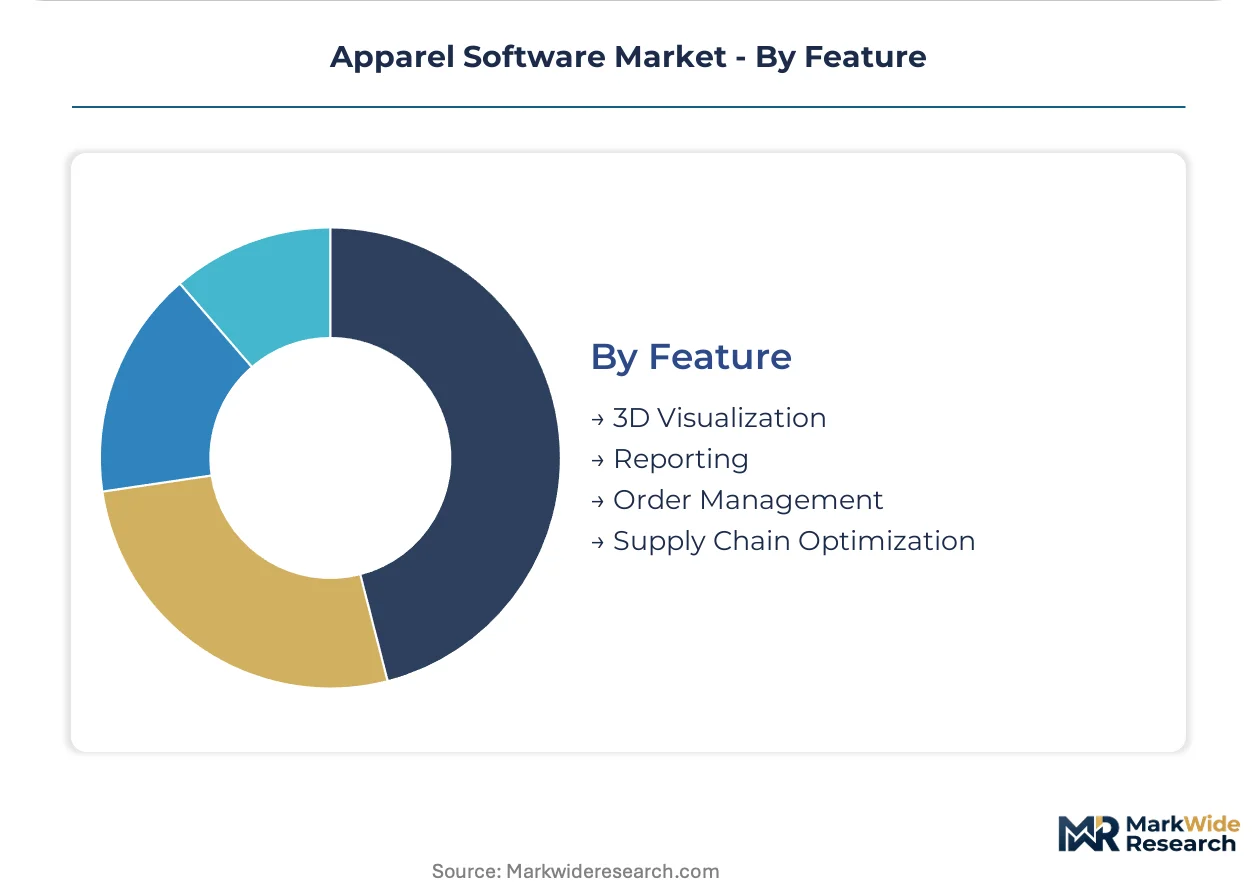
Feature:
Regulatory mandates are elevating supply chain visibility from competitive differentiator to baseline procurement requirement.
- Supply Chain Optimization:End-to-end material provenance tracking with blockchain validation and ECHA-compliant chemical substance registries. European luxury houses consolidate supplier data here to satisfy EU Green Deal digital passport mandates. Commanding the largest feature investment: Supply Chain Optimization. Gaining share fastest: 3D Visualization.
- 3D Visualization:Generative design algorithms and AI-powered pattern generation trained on historical archives. Quality prediction modules flag construction risks before physical sampling.
- Reporting:ESG disclosure dashboards and automated regulatory filing generators.
- Order Management:Multi-channel order orchestration with real-time inventory allocation.
Supply Chain Optimization absorbs the largest development investment, while 3D Visualization accelerates fastest as generative AI matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Bangladesh are concentrating manufacturing software demand, while EU regulatory mandates pull investment toward traceability platforms in Germany and France.
United States
California's Safer Consumer Products regulations and EPA reporting obligations drive procurement of chemical traceability modules. Fashion brands in Los Angeles and New York Metro seek cloud-native PLM platforms with OpEx flexibility. Direct-to-consumer startups in the Pacific Northwest prioritize lightweight MES solutions for micro-factory networks.
Germany
ECHA REACH enforcement and EU Green Deal digital passport requirements anchor enterprise ERP consolidation decisions. Bavaria and North Rhine-Westphalia host luxury houses consolidating supplier data into single-source-of-truth platforms. Stuttgart's automotive-tier suppliers are repurposing traceability architectures for textile applications.
China
MIIT industrial internet policies and dual carbon goals accelerate IoT sensor integration in Yangtze River Delta manufacturing clusters. Guangdong apparel exporters adopt blockchain provenance tracking to satisfy European buyer requirements. Shenzhen's SaaS vendors are localizing planning modules for Southeast Asian contract manufacturers.
Vietnam
Production-linked incentives and EU-Vietnam Free Trade Agreement rules-of-origin compliance expand software procurement in Ho Chi Minh City and Hanoi industrial zones. Cut-and-sew operations demand real-time WIP visibility with API connectivity to European brand headquarters. Localized deployment support is displacing remote implementation models.
India
PLI scheme for textiles attracts greenfield manufacturing investments requiring modern ERP stacks in Tamil Nadu and Gujarat. BIS quality standards and DGFT export documentation mandates shape feature requirements. Bangalore's software services ecosystem is spawning specialized vendors for mid-market fashion brands.
Apparel Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and customer tiers. Oracle Corporation anchors enterprise-grade installations through database architecture advantages, while vertical specialists capture mid-market share through workflow depth. Three archetypes dominate: horizontal ERP extenders, textile-native specialists, and cloud-native challengers. M&A activity concentrates on traceability module tuck-ins, while geographic expansion targets Vietnam and Bangladesh production clusters.
Within the vertical specialist tier, Fast React Systems and AIMS 360 Apparel Software exemplify production-planning depth, with the former representing Southeast Asian manufacturing hub penetration and the latter occupying North American cut-and-sew concentration. Oracle Corporation anchors the diversified conglomerate archetype, leveraging enterprise infrastructure relationships to absorb compliance-driven consolidation mandates. Systech Infovations Pvt. Ltd. sits within the emerging vendor category, reflecting India's software services export capacity repurposed for domestic textile digitization.
| Leading Market Players |
|---|
| AIMS 360 Apparel Software |
| ApparelMagic |
| Apparel Business Systems |
| Fast React Systems |
| Aptean |
| Oracle Corporation |
| Systech Infovations Pvt. Ltd. |
| Powersoft Computer Solutions Ltd. |
| Computer Generated Solutions, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive cloud infrastructure investments by Oracle Corporation and Fast React Systems anchor both supply positioning and pricing power in enterprise ERP deployments. These vertically integrated platform stacks compress implementation timelines while commanding subscription premiums from multinational fashion houses facing ECHA compliance deadlines.
Pricing Analysis
Short lead-time deployments command premium SaaS rates as mid-market fashion brands accelerate cloud migrations to meet EU Green Deal digital passport mandates. Subscription pricing stratifies across enterprise, professional, and essential tiers, with differentiation driven by API connectivity depth and ECHA traceability module inclusion. Cost compression in the essential tier intensifies as Shenzhen-based vendors localize planning modules for Southeast Asian contract manufacturers. Direct-to-consumer startups lacking balance sheet capacity exhibit highest price sensitivity, while European luxury houses prioritize compliance functionality over TCO optimization.
Supply Chain Analysis
Regional distribution centers in Ho Chi Minh City and Hanoi industrial zones anchor hub-and-spoke patterns serving Vietnam's cut-and-sew manufacturing clusters. Software supply concentrates in the United States, Germany, and China, with platform engineering drawing from Bangalore's services ecosystem and Shenzhen's SaaS development capacity. Single-source vulnerability persists in blockchain provenance modules, where European vendor consolidation creates bottleneck risk. Distribution runs through direct enterprise sales for multinational fashion houses and channel partners for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained specialized talent pools prop pricing power as software engineers with dual competency in textile engineering and API architecture command premium compensation across all deployment tiers.
For Market Incumbents: Hedge against cloud-native challengers by embedding generative AI pattern generation into core PLM modules before mid-market brands consolidate purchasing decisions. Acquire traceability specialists to satisfy ECHA digital product passport mandates without custom development overhead. Reinforce data residency architecture to navigate EU GDPR and China's localization law friction. For New Entrants and Emerging Players: The gap between premium enterprise subscriptions and economy-tier essential offerings creates entry space for modular point solutions targeting direct-to-consumer micro-factory networks. Penetrate the India PLI scheme beneficiary segment with lightweight MES deployments in Tamil Nadu and Gujarat greenfield investments. Pursue channel partnerships with Bangalore software services exporters to accelerate localization. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified ERP conglomerates seeking textile vertical depth. Long-term viability hinges on regulatory data architecture adaptability across ECHA, EPA, and BIS jurisdictions. Target acquisition archetypes include blockchain provenance module specialists and generative AI pattern generation startups. Watch for ECHA enforcement intensity as inflection indicator for compliance-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity to factory floor IoT sensors compresses sample-to-production cycles for fast-fashion retailers. |
| Acquisition of Specialist Firm | Traceability module tuck-ins satisfy EU Green Deal digital passport mandates without custom engineering overhead. |
| Geographic Expansion | Localized deployment support in Vietnam and Bangladesh displaces remote implementation models for cut-and-sew operations. |
| Strategic Partnership | Channel alliances with Shenzhen SaaS vendors accelerate planning module localization for Southeast Asian manufacturers. |
| Product Launch | Generative AI pattern generation tools trained on historical archives reduce concept-to-sample timelines for Turkish retailers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with PLM platform engineers, ERP procurement officers at fashion houses, textile supply chain directors, and SaaS channel partners. ECHA substance registration databases, MIIT industrial internet policy documents, SEC 10-K software segment disclosures, and Vietnam Ministry of Industry and Trade investment reports provided validation benchmarks. Bottom-up deployment counts across cloud and on-premise architectures were triangulated against top-down vendor revenue estimates.
Granularity-level modeling captured deployment mode, organization size by employee count, vertical specialization across luxury and fast-fashion segments, integration complexity tiers, and regional adoption patterns shaped by data residency constraints. CAGRs were derived from segmented growth rate assumptions applied across the projection horizon. Forecast inputs included ECHA enforcement trajectory for digital product passports and India PLI scheme textile investment flow projections.
Inputs from ECHA registration databases and MIIT policy circulars were available through the study window; gaps in real-time SaaS pricing disclosure introduce uncertainty bands around subscription revenue estimates. Forecasts reflect documented assumptions regarding regulatory timeline adherence and cloud migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
IT Services Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Global CMDB Software Market
Software & Services
Global Equity Management Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Meditation Management Apps Market
Software & Services
Stock Control Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Non-Profit Donation Software Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
US Digital Marketing Software Market
Software & Services
Casino Management Systems Market
Software & Services
Sports Facility Scheduling and Management Software Market