
 Anti-Skid Films Market | 2026-2036
Anti-Skid Films Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Skid Films Market Outlook
Aftermarket film application services is fragmenting across regional installers and OEM-certified applicators, eroding concentrated margin pools that once favored bulk distributors. 3M leverages its patent portfolio in microreplication technology to sustain premium positioning in industrial flooring segments. Avery Dennison Corporation anchors North American supply chains through direct converter relationships and specialized logistics packaging programs. Sika competes in construction-adjacent applications where chemical compatibility with sealant systems creates specification lock-in.
Anti-skid films are pressure-sensitive or extruded polymer sheets engineered with embossed, coated, or coextruded surface topographies that achieve coefficient-of-friction values typically exceeding 0.5 for slip resistance compliance. These films incorporate polyethylene, vinyl, or polyester substrates with silica or aluminum oxide particulate layers to prevent load shifting, personnel falls, or product damage across industrial and commercial environments. Polyethylene formulations dominate volume production due to cost-efficient extrusion and broad chemical resistance, while polyester variants command technical premiums in aerospace and heavy-duty flooring where dimensional stability under load matters. Vinyl grades sustain growth in consumer goods packaging where conformability to irregular surfaces and printability drive specification. Coextruded technology leads manufacturing investment because multi-layer architectures integrate distinct slip, adhesion, and barrier functions without secondary lamination steps.
FDA food-contact material regulations govern anti-skid films deployed in packaging applications where incidental surface contact with consumables occurs, while OSHA walking-working surface standards mandate slip-resistant treatments in commercial and industrial facilities across the United States. REACH restrictions on persistent organic pollutants and heavy metal additives in Europe are reformulating coating chemistries and tightening supplier qualification protocols. Stakeholders must monitor evolving PFAS restrictions in multiple jurisdictions, as fluorinated slip agents face substitution pressure that will reshape raw material sourcing and product certification requirements.
Market Dynamics
Coextruded multi-layer architectures are displacing secondary lamination across packaging and flooring applications, compressing production steps while integrating slip, adhesion, and barrier functions in single-pass extrusion lines. This structural shift rewards capital-intensive producers with integrated compounding capabilities and locks out toll converters dependent on multi-step processing.
Growth Catalysts
- OSHA Walking-Working Surface Standards:Mandated slip-resistant treatments in US commercial and industrial facilities sustain specification demand for coefficient-of-friction certified films across warehousing, manufacturing, and retail environments.
- China's Export-Oriented Manufacturing Corridors:Pallet stabilization requirements in Yangtze River Delta and Pearl River Delta logistics hubs drive volume consumption of polyethylene-based anti-skid films for containerized freight security.
- Silica-Aluminum Oxide Particulate Coatings:Advanced surface topographies achieving friction values exceeding 0.5 enable compliance with heavy-duty flooring specifications in aerospace maintenance facilities and industrial platforms.
Market Restraints
- Petroleum-Derived Feedstock Volatility:Polyethylene and vinyl substrate costs fluctuate with naphtha and ethylene spot markets, compressing margin visibility for extrusion-dependent producers without long-term resin contracts.
- REACH Persistent Organic Pollutant Restrictions:ECHA reformulation mandates on heavy metal additives and legacy slip agents force coating chemistry redesigns, extending supplier qualification timelines and raising R&D overhead.
- Mechanical Fastening Substitution:Strapping, stretch wrapping, and interlocking pallet systems compete for load security applications in cost-sensitive logistics segments where film application adds processing steps.
Strategic Opportunities
- India's PLI Scheme for Packaging Materials:Production-linked incentives for advanced polymer processing attract greenfield extrusion capacity targeting domestic consumer goods and pharmaceutical export packaging.
- PFAS-Free Formulation White Space:Fluorinated slip agent substitution creates first-mover advantage for particulate and silicone-based alternatives as US EPA and EU ECHA restrictions expand across jurisdictions.
- Digital Print-Compatible Vinyl Grades:Conformable, high-clarity substrates enable on-demand branded packaging with integrated anti-skid functionality, opening consumer electronics and premium retail segments.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:FDA food-contact notifications, REACH substance registrations, and GB standards compliance for China market entry require parallel testing streams that extend product launch cycles.
- Coextrusion Die Engineering Scarcity:Complex multi-layer manifold design and layer distribution control depend on specialized tooling expertise concentrated among European and Japanese equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Skid Films Market |
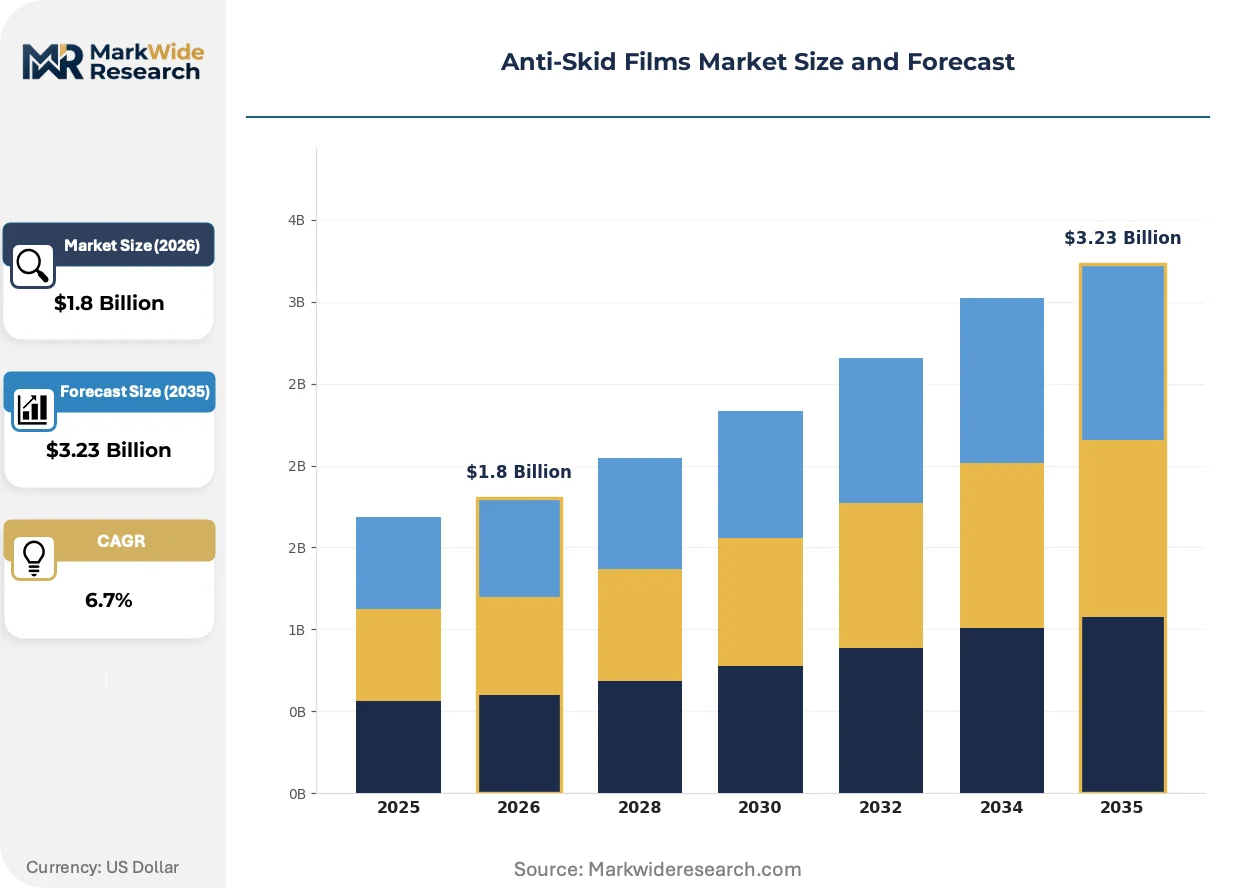
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Vinyl, Polyester, Polypropylene End User: Construction, Automotive, Aerospace, Consumer Goods Application: Flooring, Packaging, Automotive Interiors, Sports Equipment Technology: Coextruded, Laminated, Extruded, Film Forming |
| Companies Covered | 3M, Nitto Denko Corporation, Avery Dennison Corporation, PPG Industries, Sherwin-Williams, Rust-Oleum, Hempel A/S, Axalta Coating Systems, Sika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Skid Films Market Strategic Shifts
Surface engineering and substrate architecture are converging to eliminate secondary processing steps while meeting tightening friction and chemical compliance requirements across regulated end-uses.
Coextruded barrier-slip-adhesion films are hybridizing previously separate functional layers into unified sheet structures. Aerospace MRO facilities and heavy-duty industrial flooring contractors are specifying these integrated products for dimensional stability under sustained mechanical load. The technology is compressing toll lamination demand and consolidating margin capture within vertically integrated extrusion houses.
REACH restrictions on per- and polyfluoroalkyl substances are forcing coating chemistry transitions across European supply chains. Industrial flooring and logistics packaging formulators are accelerating silicone and mineral particulate substitutions to maintain friction performance while preempting regulatory disqualification. German and French specification bodies are tightening supplier qualification protocols, favoring compounders with in-house analytical certification capabilities.
Specification-driven procurement now favors certified friction performance over unit cost in liability-sensitive verticals. Third-party testing laboratories and OEM-certified applicator networks are displacing spot-market bulk film distributors in US commercial construction and warehousing segments. California and Texas municipal procurement codes exemplify this shift, embedding ASTM slip-resistance testing into mandatory pre-qualification requirements.
Anti-Skid Films Market Segmentation
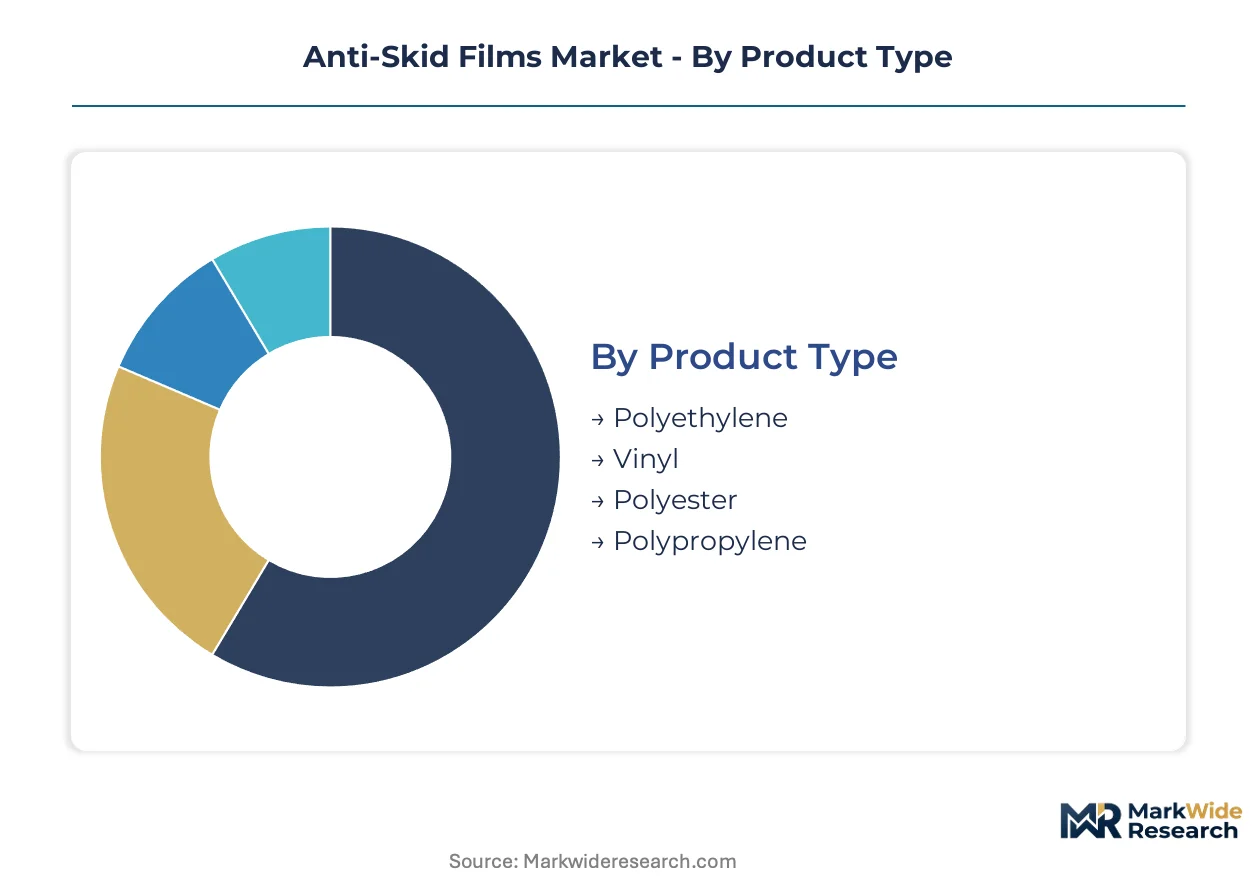
Anti-skid film specifications diverge sharply across load-bearing requirements, chemical exposure profiles, and regulatory compliance thresholds. Material substrate selection and surface engineering technology determine which segments capture specification-driven procurement versus price-sensitive volume accounts.
Product Type:
Mature commodity grades dominate volume throughput while technical substrates command specification premiums in regulated end-uses.
- Polyethylene:Cost-efficient extrusion and broad chemical resistance make this the default substrate for pallet stabilization films in logistics packaging. China's Yangtze River Delta manufacturing corridors consume substantial volumes for export container security, though petroleum feedstock volatility compresses margin visibility for producers without long-term resin contracts.
- Vinyl:Conformability to irregular surfaces and superior printability sustain growth in consumer goods packaging where branded presentation integrates with slip resistance. Digital print-compatible formulations are opening premium retail segments for on-demand customization.
- Polyester:Dimensional stability under sustained mechanical load commands technical premiums in aerospace maintenance facilities and heavy-duty industrial platforms.
- Polypropylene:Chemical resistance and moisture barrier properties serve specialized pharmaceutical and food-contact packaging applications.
Polyethylene handles the majority of throughput; vinyl is gaining share fastest as digital print integration reshapes consumer packaging specifications.
End User:
Application requirements span liability-sensitive commercial construction to precision-tolerance aerospace environments.
- Construction:OSHA walking-working surface standards mandate slip-resistant treatments in US commercial and industrial facilities. Sika and construction-chemical suppliers leverage specification lock-in through sealant system compatibility.
- Consumer Goods:Conformable vinyl grades enable branded packaging with integrated anti-skid functionality for electronics and premium retail.
- Aerospace:Dimensional stability requirements under mechanical load drive polyester specifications for maintenance platforms and cargo handling systems.
- Automotive:Interior trim applications require low-VOC formulations meeting OEM material qualification protocols.
Construction absorbs the largest volume base; consumer goods is expanding most quickly as e-commerce packaging requirements proliferate.
Application:
Functional performance thresholds separate industrial safety specifications from logistics efficiency requirements.
- Packaging:Pallet stabilization and load security films dominate Asia-Pacific logistics operations. Coextruded multi-layer architectures displace secondary lamination, compressing production steps while integrating slip, adhesion, and barrier functions.
- Flooring:Coefficient-of-friction certification exceeding 0.5 is mandatory for commercial and industrial facilities under OSHA standards. Third-party testing laboratories are displacing spot-market bulk distributors in procurement workflows.
- Automotive Interiors:Low-emission and tactile surface requirements govern OEM supplier qualification.
- Sports Equipment:Specialized grip surfaces for recreational and professional athletic applications.
Packaging commands the highest volume throughput; flooring is climbing the fastest as liability-driven specification tightens.
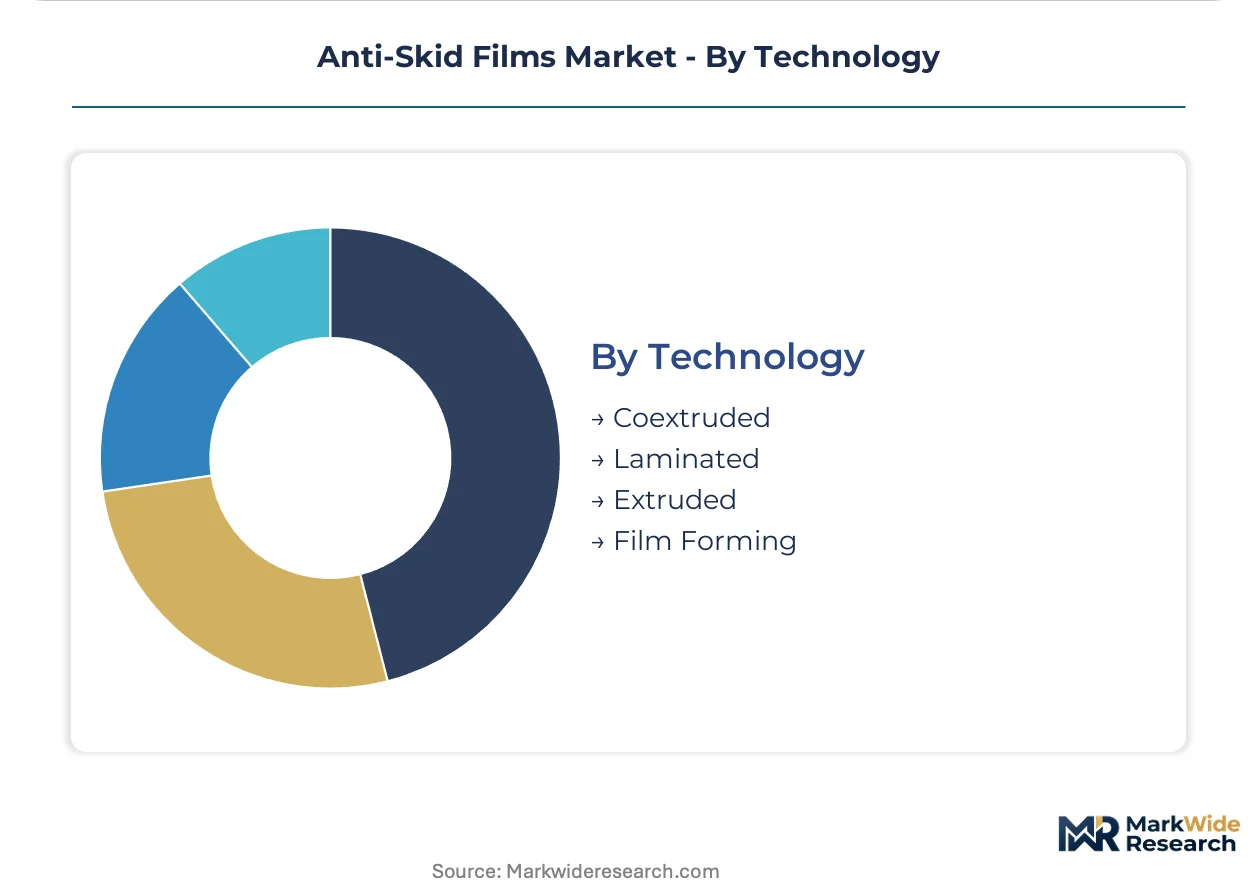
Technology:
Manufacturing process selection determines margin capture potential and barrier-to-entry height for competing suppliers.
- Coextruded:Multi-layer manifold designs integrate distinct slip, adhesion, and barrier functions without secondary lamination. This architecture rewards capital-intensive producers with integrated compounding capabilities and locks out toll converters dependent on multi-step processing. Complex die engineering expertise concentrates among European and Japanese equipment suppliers.
- Laminated:Secondary bonding of functional layers persists in legacy installations and specialized applications requiring dissimilar material combinations.
- Extruded:Single-layer commodity production serves cost-sensitive volume segments.
- Film Forming:Cast and blown film processes for basic substrate manufacturing.
Coextruded technology handles the majority of new capacity investment; laminated processes are ceding share fastest to integrated single-pass architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's manufacturing corridors exhibit the lowest price elasticity, absorbing premium specifications for export compliance, while logistics operators in Southeast Asia remain highly sensitive to unit film costs.
China
Yangtze River Delta and Pearl River Delta logistics hubs drive substantial polyethylene film consumption for containerized freight security. GB standards compliance for food-contact materials and industrial safety tighten supplier qualification protocols. Shanghai and Shenzhen manufacturing clusters specify coextruded multi-layer films for pallet stabilization in export-oriented electronics and automotive supply chains.
United States
OSHA walking-working surface standards mandate coefficient-of-friction certified films across warehousing and commercial construction. FDA food-contact notifications govern packaging applications with incidental consumable exposure. Texas and California municipal procurement codes embed ASTM slip-resistance testing into mandatory pre-qualification, displacing spot-market bulk distributors.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force coating chemistry transitions across industrial flooring supply chains. ECHA reformulation mandates on heavy metal additives extend supplier qualification timelines. Bavaria and North Rhine-Westphalia specification bodies tighten analytical certification requirements, favoring compounders with in-house testing capabilities.
India
Production-linked incentive schemes for advanced polymer processing attract greenfield extrusion capacity targeting domestic consumer goods packaging. BIS standards compliance for industrial safety materials creates certification barriers for imported alternatives. Maharashtra and Gujarat pharmaceutical export corridors specify anti-skid films for pallet stabilization in temperature-controlled logistics.
Japan
METI industrial safety guidelines and JIS standards for slip-resistant surface treatments sustain specification demand in precision manufacturing environments. Chubu and Kansai aerospace maintenance facilities require polyester substrates for dimensional stability under sustained mechanical load. Osaka industrial platforms specify silica-aluminum oxide particulate coatings achieving friction values exceeding 0.5.
Anti-Skid Films Market Competitive Environment
Capability concentration sits with specialized compounders possessing in-house analytical certification and coextrusion die engineering expertise; scale advantage sits with diversified materials conglomerates leveraging integrated resin supply chains. The market structures around three tiers: patent-anchored technology licensors, regional converter networks, and construction-chemical integrators. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with third-party testing laboratories for specification lock-in.
Among diversified materials conglomerates, 3M and Avery Dennison Corporation exemplify patent-anchored positioning through microreplication technology portfolios and direct converter relationships respectively. Sika occupies a position within the construction-chemical integrator tier where specification bundling with sealant systems creates procurement stickiness. These three entities represent distinct archetypes: technology licensing, supply chain anchoring, and application-system integration.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| PPG Industries |
| Sherwin-Williams |
| Rust-Oleum |
| Hempel A/S |
| Axalta Coating Systems |
| Sika |
| Others |
Value Chain & Pricing Dynamics
Petroleum-derived feedstock volatility compresses margin visibility for extrusion-dependent producers without long-term resin contracts, simultaneously widening pricing tier spreads between polyethylene commodity grades and polyester technical premiums while reshaping supply chain investment toward integrated compounding capabilities.
Pricing Analysis
Aftermarket film application services drive lifetime value through specification-certified installation contracts rather than unit film sales. Three-tier pricing structure across premium, standard, and economy levels separates coextruded multi-layer architectures with in-house analytical certification from toll-converted commodity grades and basic extruded single-layer products. Cost compression in polyethylene logistics films is intensifying because petroleum feedstock volatility erodes contract pricing predictability. Logistics operators in Southeast Asia exhibit highest price sensitivity, while aerospace maintenance facilities in Japan and Germany absorb technical premiums for dimensional stability certification.
Supply Chain Analysis
Contract manufacturing concentration for coextrusion die engineering sits with European and Japanese equipment suppliers including specialized manifold designers in Germany and layer distribution control specialists in Japan. Geographic supply concentration centers on China for polyethylene resin compounding, Germany for REACH-compliant coating chemistry, and the United States for FDA food-contact certified formulations. Raw material dependencies draw from naphtha and ethylene spot markets, silica-aluminum oxide particulate suppliers, and fluorinated slip agent alternatives under regulatory pressure. Single-source vulnerability concentrates in specialized coextrusion tooling expertise. Distribution runs through OEM-certified applicator networks displacing spot-market bulk distributors in liability-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-skid film procurement is shifting toward platform-based specification systems where third-party testing laboratories and certified applicator networks create interoperability lock-in, mirroring ecosystem economics seen in construction-chemical bundling.
For Market Incumbents: Build certification moats by acquiring in-house analytical testing capabilities and securing parallel FDA food-contact, REACH substance registration, and GB standards compliance to preempt multi-jurisdictional qualification timelines. Backward integration into resin compounding secures margin capture against petroleum feedstock volatility. Channel control through direct converter relationships anchors North American supply chains against emerging toll-converter competition. For New Entrants and Emerging Players: Build out PFAS-free formulation capabilities as US EPA and EU ECHA restrictions expand, targeting the white space created by fluorinated slip agent substitution. India's PLI scheme for packaging materials offers the most penetrable geography for greenfield extrusion capacity. Digital print-compatible vinyl grades for consumer electronics packaging provide a differentiated go-to-market angle against commodity polyethylene competition. For Investors and Strategic Acquirers: REACH restrictions on per- and polyfluoroalkyl substances reshape the acquisition landscape by disqualifying legacy coating chemistries and elevating compounders with in-house reformulation capabilities. Long-term viability favors vertically integrated extrusion houses with captive coextrusion die engineering partnerships over toll-dependent converters. Watch for ECHA substance registration deadlines as inflection indicators for supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply secures margin visibility against naphtha spot market volatility. |
| PFAS-Free Formulation Development | Silicone and mineral particulate substitutions preempt REACH and US EPA regulatory disqualification. |
| Third-Party Testing Laboratory Partnership | ASTM slip-resistance certification embeds specification lock-in for OSHA-compliant flooring contracts. |
| Digital Print-Compatible Vinyl Capacity | On-demand branded packaging integration opens premium consumer electronics and retail segments. |
| Multi-Jurisdictional Certification Investment | Parallel FDA, REACH, and GB compliance accelerates product launch cycles across export corridors. |
Study Parameters
A spread of perspectives from plant managers at extrusion facilities, procurement leads at logistics packaging OEMs, distribution channel partners, technical R&D directors, and aftermarket film applicators converged on the working assumptions shaping demand forecasts. Primary interview insights were validated against customs and trade data, American Chemistry Council and Cefic polymer reports, SEC 10-K filings from diversified materials conglomerates, and regulatory submission databases from FDA and ECHA. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to constrain variance.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume trajectories against extrusion capacity expansion and raw material availability constraints. Segmentation dimensions included substrate type, end-use industry, surface engineering technology, and regional regulatory cluster. CAGRs were derived from slope-intercept modeling of historical consumption patterns and elasticity-adjusted projection. Industry-specific forecast inputs incorporated OSHA enforcement intensity indices and REACH substance registration timelines.
Stress conditions across petroleum feedstock price bands, REACH reformulation compliance costs, and coextrusion equipment lead times were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and substitution technology maturation. Cross-checking against customs trade flow data and polymer resin price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Handle Gusseted Bags Market
Packaging
Cassava Bags Market
Packaging
Metal Crates Market
Packaging
Custom Boxes Market
Packaging
Flow Wrap Packaging Market
Packaging
Bulk Tote Dumpers Market
Packaging
Spigot End Cap Market
Packaging
Die Cut Labels Market
Packaging
Cold Chain Temperature Monitoring Market
Packaging
Flexible Film Market
Packaging
Automotive Adhesive Tapes Market
Packaging
Blind Box Machine Market
Packaging
Media Bottles Market
Packaging
Banding Machine Market
Packaging
Global Single Use Plastic Packaging Market
Packaging
Flexible Paper for Food & Beverages Packaging Market