
 Airport Runway Safety System Market | 2026-2036
Airport Runway Safety System Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Runway Safety System Market Outlook
Modular system bundling is broadening buyer choice as airports shift from standalone components to integrated runway safety platforms. ADB SAFEGATE leverages its end-to-end airfield lighting and guidance portfolio to anchor large hub deployments across Europe and the Middle East. Honeywell International Inc. sustains technology leadership through deep R&D investment in automated alert algorithms and sensor fusion architectures. Saab AB competes on geographic dominance in Nordic and Asia-Pacific markets with specialized surface movement radar configurations.
Airport runway safety systems encompass integrated hardware and software platforms designed to detect, prevent, and mitigate runway incursions, excursions, and surface movement conflicts through real-time surveillance, alerting, and guidance functions; core specifications include millimeter-wave radar resolution under 0.1 degrees, ground sensor latency below 100 milliseconds, and redundant communication links operating at 1090 MHz and 1030 MHz frequencies to ensure continuous airside operational integrity. Surface movement guidance systems currently occupy the largest product category as legacy airports prioritize visual aids and signage upgrades over full automation transitions. Radar systems lead technology adoption due to proven all-weather performance, while ground sensors represent the fastest-expanding segment driven by fiber-optic and acoustic innovations that reduce maintenance cycles and electromagnetic interference.
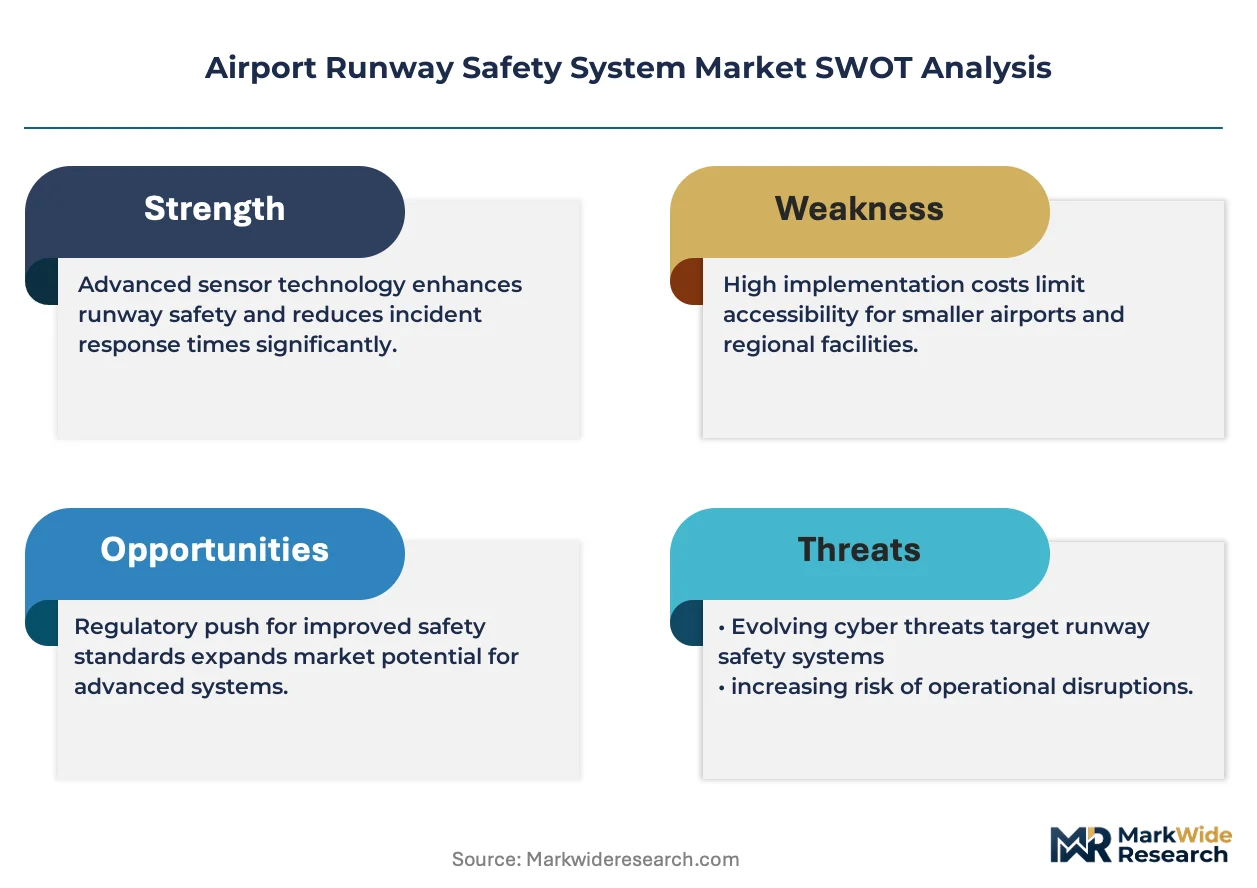
The Federal Aviation Administration imposes stringent certification standards through Advisory Circular 150/5210-24 for runway safety area improvements, while the European Union Aviation Safety Agency enforces CS-ADR-DSN design specifications that mandate advanced surface guidance at category III airports; ICAO Annex 14 provisions further harmonize international baseline requirements for incursion prevention infrastructure. The EU Green Deal and national carbon neutrality programs are beginning to shape procurement criteria, favoring lower-energy sensor networks and LED-integrated guidance systems. Stakeholders must monitor evolving ICAO Global Reporting Format requirements for runway condition assessment and determine whether to prioritize retrofit portability or permanent integrated architectures in capital planning cycles.
Market Dynamics
Airport operators face mounting pressure to reconcile aging infrastructure with zero-tolerance safety mandates, forcing capital allocation toward sensor fusion architectures that unify legacy radar with fiber-optic ground detection networks.
Growth Catalysts
- ICAO Annex 14 harmonization:International baseline provisions for incursion prevention infrastructure compel tier-2 and tier-3 airports to upgrade surface guidance capabilities.
- FAA Advisory Circular 150/5210-24:Stringent runway safety area improvement standards in the United States tighten certification timelines and accelerate replacement cycles.
- LED-integrated guidance systems:Energy-efficient visual aid technologies align with EU Green Deal procurement criteria, expanding addressable retrofit opportunities.
Market Restraints
- Millimeter-wave radar component concentration:Specialized semiconductor foundry capacity clusters in East Asian manufacturing hubs, exposing supply chains to geopolitical friction.
- Dual-frequency transponder costs:Redundant 1090 MHz and 1030 MHz communication links require aerospace-grade components with limited qualified supplier pools.
- Legacy airfield lighting incompatibility:Pre-2010 incandescent infrastructure lacks digital control interfaces, forcing complete subsystem replacement rather than modular upgrade.
Strategic Opportunities
- India tier-2 airport modernization:Airports Authority of India capital deployment creates concentrated demand for integrated runway monitoring suites.
- Acoustic-fiber sensor convergence:Combined vibration and temperature sensing reduces electromagnetic interference while extending maintenance intervals.
- Performance-based navigation integration:Surface movement guidance systems that interface with satellite-based approaches command procurement preference.
Industry Challenges
- Sensor fusion algorithm expertise:Integration of radar, lidar, and ground sensor streams demands specialized software engineering talent scarce in aviation electronics.
- Category III certification timelines:European Union Aviation Safety Agency CS-ADR-DSN validation protocols extend product qualification by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Runway Safety System Market |
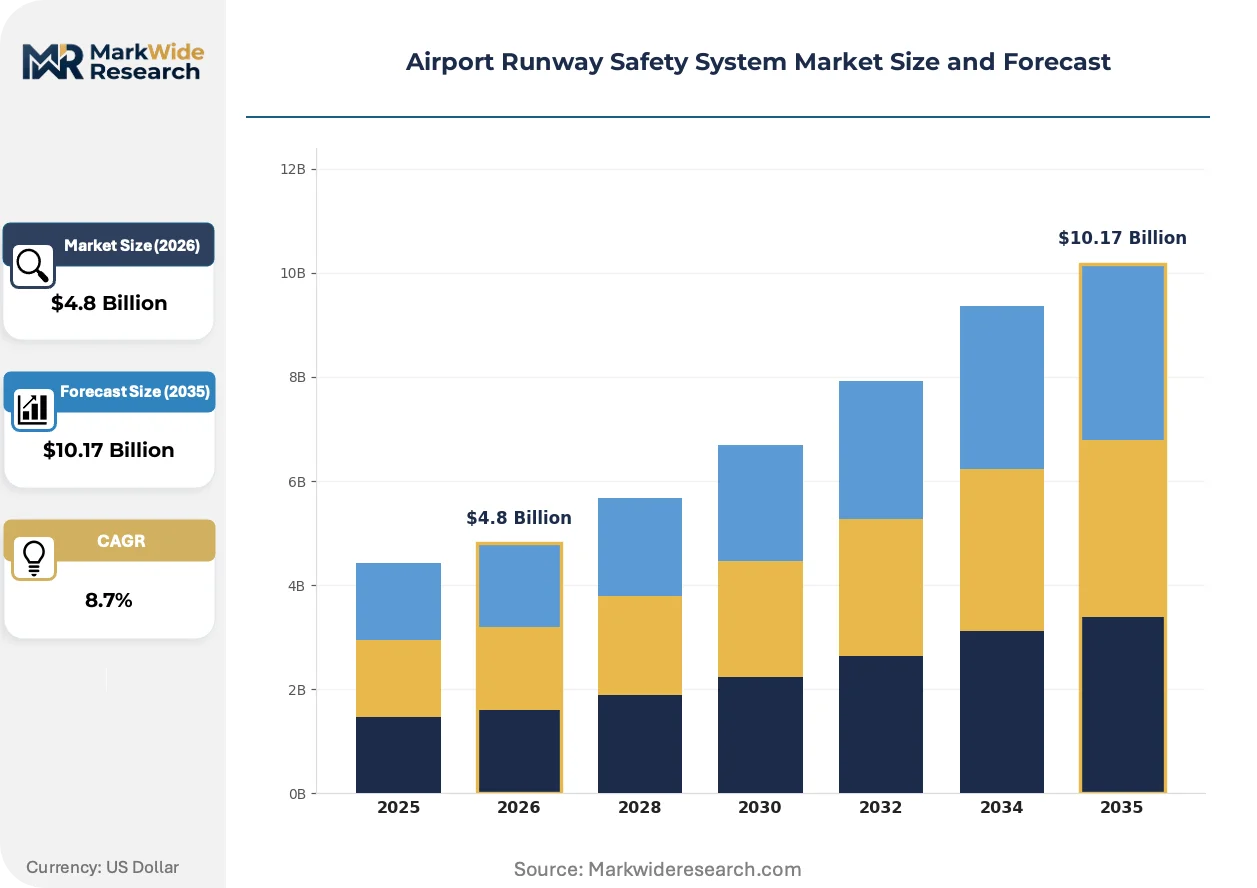
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Movement Guidance, Runway Incursion Prevention, Automated Alert Systems, Weather Monitoring Systems End User: Airports, Aviation Authorities, Airlines, Military Installations Technology: Radar Systems, Terrestrial Systems, Satellite Systems, Ground Sensors Installation Type: Permanent Systems, Portable Systems, Retrofit Solutions, Integrated Solutions |
| Companies Covered | Honeywell International Inc., ADB SAFEGATE, Saab AB, Leonardo S.p.A., Indra Sistemas S.A., Varec, Boeing, NEC Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Runway Safety System Market Strategic Shifts
Real-time data architectures are compressing the gap between detection and alert generation, redefining operational expectations for surface movement management across hub and spoke configurations.
Fiber-optic distributed acoustic sensing is electrifying perimeter and runway edge monitoring by converting standard telecommunications cable into continuous vibration detection arrays. Tier-1 hubs in Germany and the United Arab Emirates are deploying these systems for foreign object debris detection. This convergence of civil infrastructure materials with aviation safety functions is electrifying procurement specifications for integrated sensor networks.
The EU Green Deal is embedding carbon neutrality criteria into airfield lighting tenders, mandating lifecycle emissions assessments for LED-integrated guidance systems. European category III airports must now document energy consumption per landing equivalent. Surface movement guidance manufacturers are responding with modular architectures that separate power and control electronics for targeted replacement.
Consolidated procurement frameworks are displacing component-by-component acquisition as airport authorities bundle lighting, radar, and alerting systems into single-vendor contracts. Middle Eastern hub operators pioneered this model; Indian tier-2 airports are now adopting similar consolidated tender structures. This concentration of buying power favors suppliers with end-to-end airfield portfolios over specialized component vendors.
Airport Runway Safety System Market Segmentation
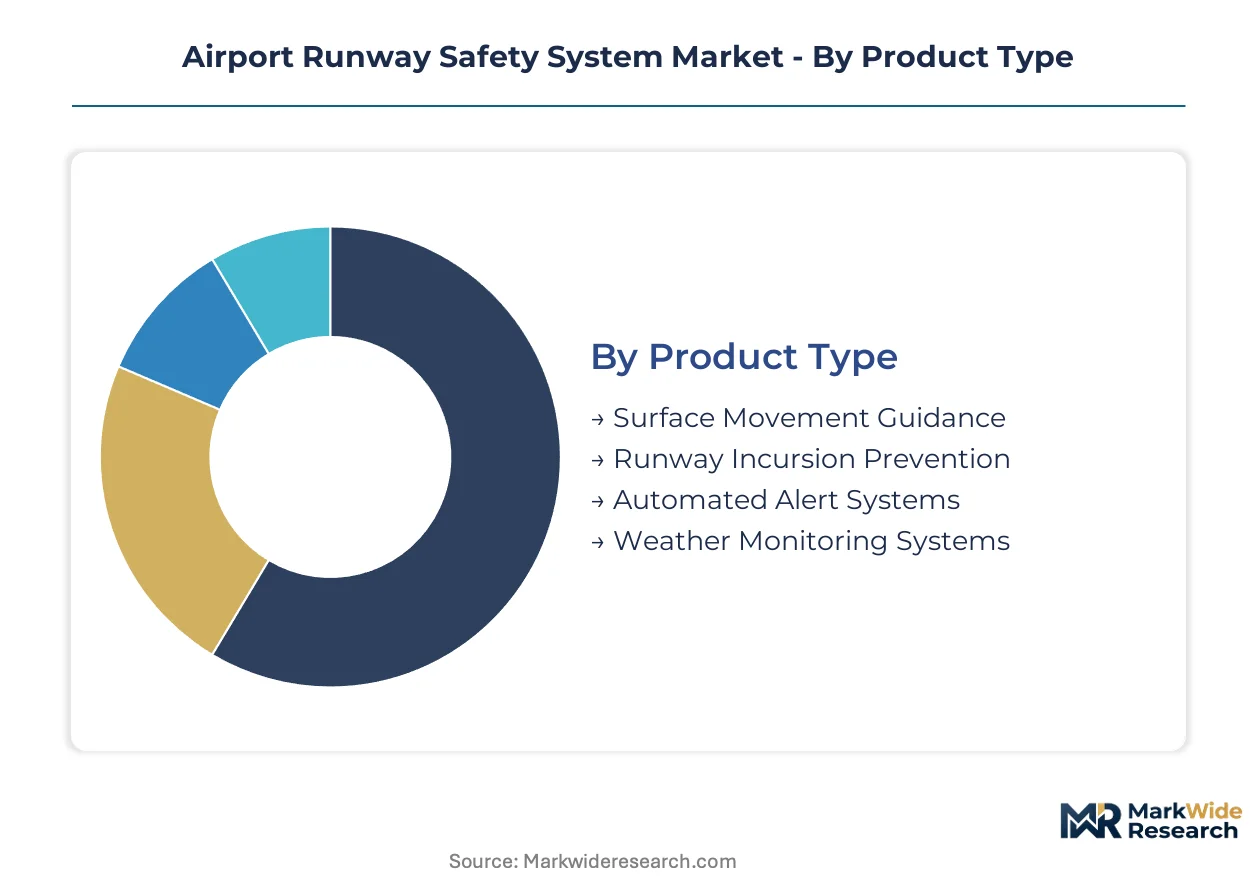
Airport operators select runway safety components based on operational tempo, weather exposure, and integration complexity with legacy airfield infrastructure. Procurement patterns diver sharply between hub airports pursuing full automation and regional facilities prioritizing discrete subsystem upgrades.
Product Type:
Buyer differentiation hinges on whether airports seek visual aid modernization or comprehensive incursion prevention architectures.
- Surface Movement Guidance:Visual signaling platforms combining LED signage, stop-bar lighting, and taxiway centerline markers dominate capital allocation at legacy facilities. German category III hubs and Dubai International anchor procurement volumes as operators reconcile EU Green Deal energy mandates with ICAO Annex 14 baseline compliance.
- Runway Incursion Prevention:Multi-sensor fusion platforms integrating radar, ground sensors, and automated alerting command premium positioning at greenfield developments. Indian tier-2 airports under Airports Authority of India modernization directives represent concentrated deployment momentum for integrated suites.
- Automated Alert Systems:Software-defined conflict detection modules process surveillance feeds to generate controller advisories.
- Weather Monitoring Systems:Runway condition assessment platforms incorporating friction measurement and contaminant detection.
Volume sits with Surface Movement Guidance; growth tilts toward Runway Incursion Prevention.
End User:
Procurement scale and certification rigor separate institutional buyers across the aviation ecosystem.
- Airports:Direct infrastructure owners specify integrated platforms spanning surveillance, guidance, and alerting. Commercial hubs in the United Arab Emirates and Singapore drive consolidated tender structures bundling multiple safety subsystems.
- Aviation Authorities:National regulators including FAA and EASA mandate equipment standards without direct procurement, shaping vendor qualification requirements.
- Airlines:Carrier-led investments concentrate at hub bases where ground operations integration delivers fleet-wide efficiency gains.
- Military Installations:Defense airfields prioritize hardened communications and electromagnetic resilience over civil certification paths.
Revenue concentrates with Airports; policy influence rests with Aviation Authorities.
Technology:
Performance under adverse weather and maintenance burden differentiate sensor architectures.
- Radar Systems:Millimeter-wave and X-band surface movement radars deliver all-weather detection with sub-0.1-degree angular resolution. Nordic airports in Norway and Sweden sustain demand for specialized configurations addressing snow and low-visibility operations.
- Ground Sensors:Fiber-optic distributed acoustic sensing and electromagnetic induction arrays convert perimeter infrastructure into continuous detection networks. German tier-1 hubs deploy these for foreign object debris monitoring, drawn by extended maintenance intervals and reduced electromagnetic interference.
- Terrestrial Systems:Camera-based visual surveillance with infrared augmentation for night operations.
- Satellite Systems:GNSS-augmented surface tracking for performance-based navigation integration.
Established deployments favor Radar Systems; Ground Sensors are climbing the fastest.
Installation Type:
Capital cycle timing and operational disruption tolerance determine architecture selection.
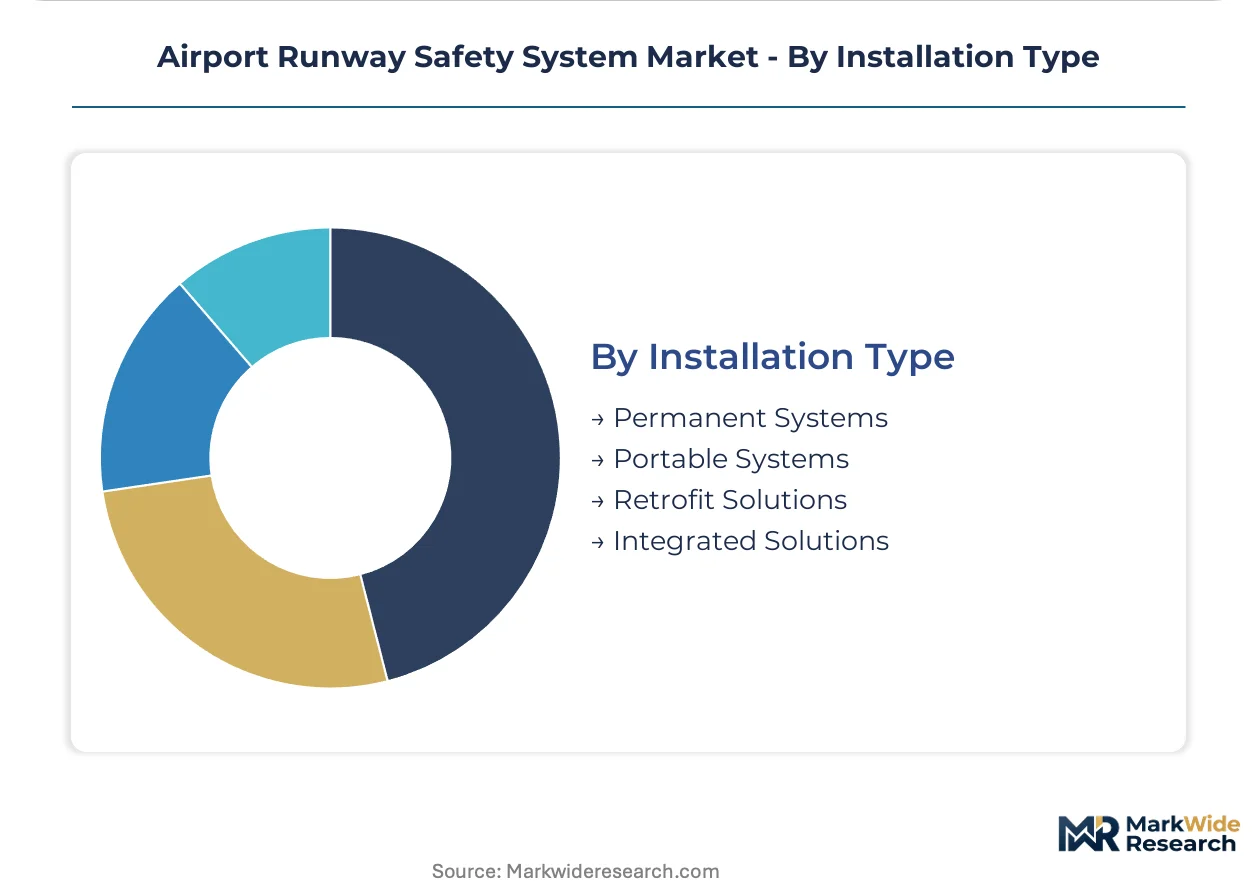
- Permanent Systems:Embedded infrastructure with 20-year design life anchors greenfield airport construction. Middle Eastern hub developments in Saudi Arabia and Qatar specify these for synchronized commissioning with terminal expansions.
- Retrofit Solutions:Modular upgrades preserving legacy lighting foundations dominate mature airport capital planning. Pre-2010 incandescent infrastructure across Italian and Spanish regional airports forces controller-electronics replacement without full airfield reconstruction.
- Portable Systems:Rapidly deployable trailer-mounted radars and communications for temporary runway operations.
- Integrated Solutions:Single-vendor platforms unifying multiple safety functions through unified control interfaces.
Deployment scale belongs to Permanent Systems; procurement momentum gathers around Retrofit Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for millimeter-wave radar components and fiber-optic sensors clusters in East Asian foundries, while deployment demand concentrates at hub airports across the United States, Germany, India, and the United Arab Emirates. Procurement patterns diverge between mature markets prioritizing retrofit solutions and greenfield developments specifying integrated platforms.
United States
FAA Advisory Circular 150/5210-24 mandates runway safety area improvements that accelerate replacement cycles at legacy facilities. The Federal Aviation Administration enforces stringent certification timelines for surface movement guidance equipment. Dallas-Fort Worth International and Atlanta Hartsfield-Jackson anchor procurement volumes as operators reconcile zero-tolerance safety mandates with aging incandescent infrastructure.
Germany
EU Green Deal carbon neutrality criteria embed lifecycle emissions assessments into airfield lighting tenders at category III airports. The European Union Aviation Safety Agency enforces CS-ADR-DSN design specifications mandating advanced surface guidance. Frankfurt and Munich tier-1 hubs deploy fiber-optic distributed acoustic sensing for foreign object debris detection, drawn by extended maintenance intervals.
India
Airports Authority of India capital deployment across tier-2 and tier-3 airports creates concentrated demand for integrated runway monitoring suites. The country's national aviation regulator aligns procurement specifications with ICAO Annex 14 baseline provisions for incursion prevention infrastructure. Bangalore and Hyderabad anchor modernization momentum as secondary hubs transition from standalone components to unified safety platforms.
United Arab Emirates
Dubai International and Abu Dhabi International pioneered consolidated procurement frameworks bundling lighting, radar, and alerting systems into single-vendor contracts. The General Civil Aviation Authority mandates equipment standards that exceed ICAO baseline requirements for surface movement management. Emirates' hub operations drive specification preferences for performance-based navigation integration.
Sweden
Nordic snow and low-visibility operations sustain specialized demand for surface movement radar configurations with proven all-weather performance. The Swedish Transport Agency enforces national adaptations of EASA CS-ADR-DSN specifications for category III operations. Stockholm Arlanda anchors regional deployment volumes as operators prioritize millimeter-wave resolution under 0.1 degrees for year-round operational integrity.
Airport Runway Safety System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. Large integrated technology groups leverage cross-divisional R&D budgets to anchor multi-airport contracts, while specialized airfield equipment manufacturers defend positions through deep domain expertise in surface movement algorithms. Three archetypes dominate: end-to-end airfield portfolio suppliers, sensor technology specialists, and defense-aerospace conglomerates with civil aviation divisions. Competitive dynamics center on consolidated tender participation and certification timeline acceleration through regulatory pre-qualification.
Among diversified technology conglomerates, Honeywell International Inc. and NEC Corporation occupy positions spanning multiple aviation safety segments. ADB SAFEGATE and Saab AB exemplify the focused specialist archetype with concentrated airfield portfolios. Leonardo S.p.A. and Thales Group represent defense-aerospace conglomerates leveraging dual-use sensor technologies across civil and military runway applications. These named entities anchor the competitive map without exhausting the vendor ecosystem.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ADB SAFEGATE |
| Saab AB |
| Leonardo S.p.A. |
| Indra Sistemas S.A. |
| Varec |
| Boeing |
| NEC Corporation |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FAA/EASA-qualified integrated suites and non-certified modular components manifests in divergent pricing architectures and supplier qualification barriers. Tier-1 hub operators in Germany and the United Arab Emirates absorb 40-60% procurement premiums for end-to-end airfield portfolios, while tier-2 airports in India and Spain prioritize retrofit-compatible subsystems that preserve legacy lighting foundations.
Pricing Analysis
Cost-down pressure on ground sensor arrays accelerates because fiber-optic component commoditization is displacing proprietary radar configurations. Project-based contracting dominates integrated runway safety platforms, with pricing stratifying across certified-premium, standard-compliant, and economy-retrofit tiers. Price differentiation hinges on EASA CS-ADR-DSN validation status and after-sales service bundling. Tier-2 airport authorities in India exhibit highest price sensitivity; Middle Eastern hub operators show lowest sensitivity due to consolidated single-vendor tender structures.
Supply Chain Analysis
EASA and FAA certification gating restricts qualified supplier pools for millimeter-wave radar semiconductors and aerospace-grade transponder components. Manufacturing concentrates in Taiwan, South Korea, and Germany for specialized foundry capacity. Supply chains draw from gallium arsenide substrates, precision optical fiber, and redundant 1090/1030 MHz communication chipsets. Single-source vulnerability persists in qualified semiconductor foundries. Distribution runs through airfield engineering contractors and direct procurement frameworks at airport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated tender structures and extended EASA certification timelines are forcing component specialists toward acquisition or partnership, compressing viable vendor count over the coming half-decade.
For Market Incumbents: Anchor multi-airport maintenance contracts through predictive analytics service layers that lock in recurring revenue beyond initial hardware deployment. Deepen backward integration into fiber-optic sensor manufacturing to defend margin position against commoditization pressure from Chinese component suppliers. Prioritize regulatory pre-qualification investments that compress EASA CS-ADR-DSN validation timelines by 12-18 months versus competitors. For New Entrants and Emerging Players: Capture white-space in Indian tier-2 airport retrofit solutions where Airports Authority of India capital deployment outpaces incumbent service capacity. Target acoustic-fiber sensor convergence for foreign object debris detection as the fastest-penetrable technology segment. Pursue joint-development partnerships with German tier-1 hubs to establish certification credentials for broader European expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to defense-aerospace conglomerates seeking civil aviation diversification. Long-term viability favors suppliers with captive certification expertise and installed base density across 10+ hub airports. Acquisition target archetype: fiber-optic sensing specialists with EASA validation and existing deployments at Frankfurt or Munich. Watch for inflection when Indian Airports Authority of India tender awards exceed incumbent fulfillment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Qualification Investment | Accelerates EASA CS-ADR-DSN certification timelines against competitor product pipelines. |
| Sensor Fusion Platform Integration | Unifies radar, lidar, and ground sensor streams into single-vendor control architectures. |
| Performance-Based Navigation Interface | Aligns surface movement guidance with satellite-based approach procedures at Emirates hub operations. |
| Acoustic-Fiber Sensor Convergence | Combines vibration and temperature sensing for foreign object debris detection at German tier-1 hubs. |
| Consolidated Tender Participation | Bundles lighting, radar, and alerting systems to match Middle Eastern and Indian procurement frameworks. |
Study Parameters
ICAO regulatory filings, FAA Advisory Circular documentation, and EASA certification databases formed the secondary backbone, cross-referenced against customs records for millimeter-wave radar and fiber-optic sensor trade flows. Primary fieldwork encompassed airport operations directors, airfield engineering procurement leads, aviation safety system integrators, and regulatory compliance officers across Germany, India, the United Arab Emirates, and the United States. Bottom-up segment sizing triangulated against top-down aviation infrastructure spending forecasts from national airport authorities.
Historical deployment trendlines for surface movement guidance and runway incursion prevention systems anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, technology architecture, installation category, and airport operational tier. CAGRs derived from regression analysis of capital expenditure patterns and regulatory mandate implementation schedules. Forecast inputs included Airports Authority of India modernization commitment trajectories and EU Green Deal energy procurement criteria evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain disruptions and ICAO Global Reporting Format adoption timelines. Model outputs reflect assumptions regarding certification timeline stability and tier-2 airport capital access continuity. A model refresh is warranted upon material change in FAA surface movement guidance mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
North America Ammunition Market
Aerospace & Defense
Global Commercial Aircraft Airframe Materials Market
Aerospace & Defense
Air Crane Helicopter Market
Aerospace & Defense
General Aviation Engines Market
Aerospace & Defense
Autonomous Underwater Gliders (AUG) Market
Aerospace & Defense
Nuclear Bombs and Missiles Market
Aerospace & Defense
Cabin Reconfiguration and Retrofit MRO Services Market
Aerospace & Defense
Helicopter-Based Transportation Market
Aerospace & Defense
Laser Telemetry Binoculars Market
Aerospace & Defense
UK Space Propulsion System Market
Aerospace & Defense
Aircraft Ignition System Market
Aerospace & Defense
Aircraft Arresting System Market
Aerospace & Defense
Firefighting Aircraft Market
Aerospace & Defense
Aircraft Wiring Harness Market
Aerospace & Defense
Angle of Attack Sensor Market
Aerospace & Defense
Electronically Scanned Array Radar Market