
 Airport Retailing Market | 2026-2036
Airport Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Retailing Market Intelligence
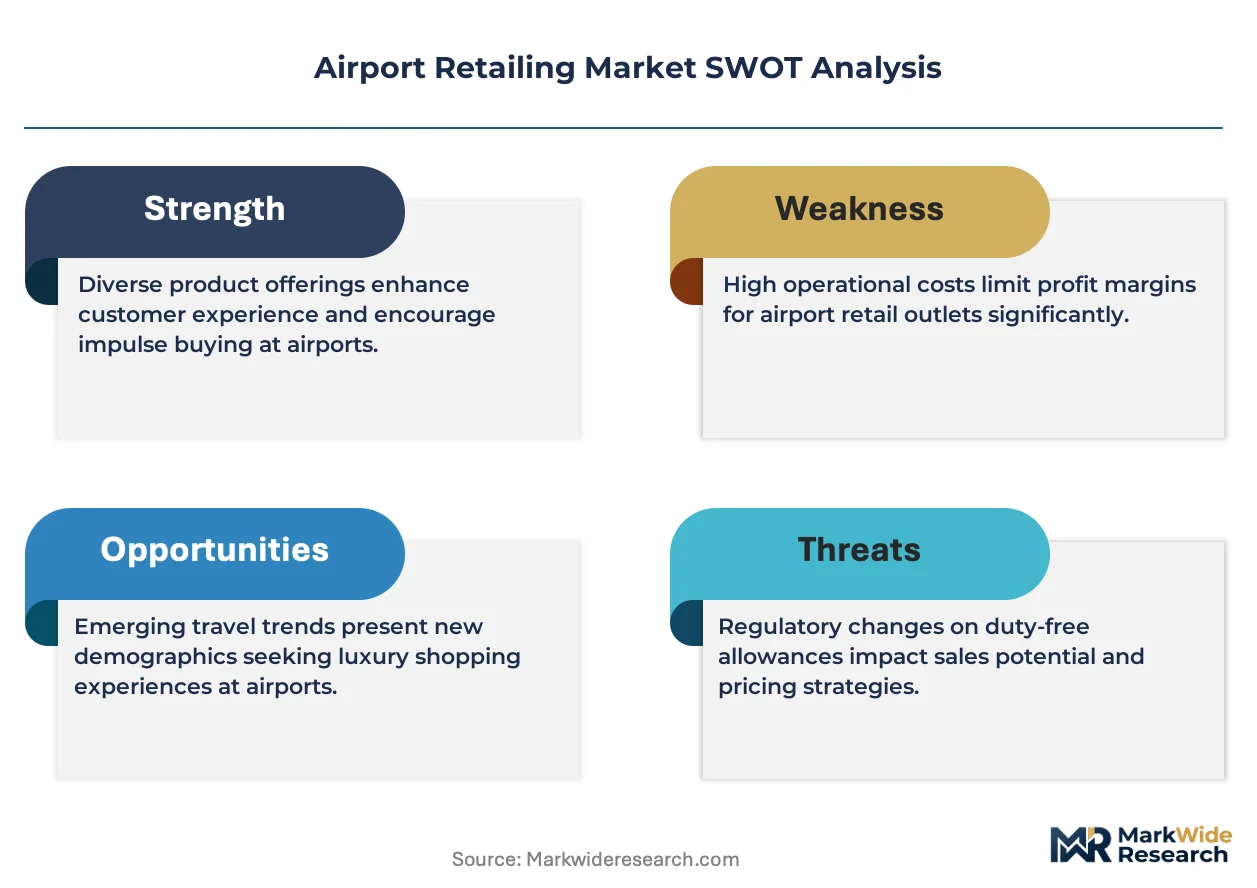
The EU Green Deal is pivoting airport retail concessions toward sustainable sourcing mandates across European hubs. Dufry AG leverages its global concession network to secure prime terminal real estate in high-traffic corridors. China Duty Free Group anchors its dominance through captive supply of luxury inventory across Hainan and mainland airport gateways. Avolta differentiates via experience-zone concepts that merge retail with passenger dwell-time entertainment.
Airport retailing encompasses commercial sales operations within passenger terminals, leveraging duty-exempt status and captive audience dynamics to generate revenue from travelers in transit. The model depends on concession agreements with airport authorities, typically structured as revenue-sharing contracts with minimum annual guarantees. Duty-free goods command the largest revenue pool among product categories, sustained by price arbitrage on tobacco, spirits, and cosmetics. Online platforms represent the fastest-growing sales channel, driven by pre-order functionality and gate-side collection services that compress transaction time. Concessionaires retain the dominant service-type position, though specialty stores are capturing margin share through curated luxury assortments.
FDA regulations govern cosmetic and skincare product claims sold in US airport retail, while REACH compliance shapes chemical safety standards for European duty-free inventory. EMA and ECHA frameworks collectively tighten ingredient disclosure requirements, forcing concessionaires to reformulate or relabel cross-border merchandise. Stakeholders must monitor evolving customs duty thresholds and digital sales tax treatments that threaten the traditional duty-free price advantage.
Market Dynamics
Biometric boarding and digital payment rails are compressing transaction windows at checkout, forcing concessionaires to reconfigure floor plans around dwell-time capture rather than throughput volume.
Growth Catalysts
- Hainan duty-free expansion:China's offshore duty-free policy is pulling luxury inventory toward mainland airport gateways and reshaping regional supply allocation.
- REACH chemical disclosure:European reformulation mandates are accelerating clean-label cosmetics development, opening premium positioning for compliant concessionaires.
- Pre-order platform adoption:Gate-side collection services are extending sales windows beyond security checkpoint constraints.
Market Restraints
- Concession fee escalation:Minimum annual guarantees at Dubai International and Heathrow are consuming 18-25% of gross revenue.
- Luxury brand supply concentration:LVMH, Richemont, and Kering control 60% of high-margin inventory, limiting assortment differentiation.
- Digital sales tax ambiguity:OECD framework delays threaten the price arbitrage foundation of duty-free cosmetics and spirits.
Strategic Opportunities
- Saudi Arabia hub development:King Salman International Airport's retail masterplan offers first-mover positioning in underdeveloped premium corridors.
- EU Green Deal sustainable sourcing:Mandates for recycled packaging and carbon-disclosed supply chains reward early-compliant concessionaires with preferential lease terms.
- AI-driven personalization:Facial recognition loyalty systems are converging with mobile payment rails to enable dynamic pricing by passenger profile.
Industry Challenges
- Biometric integration complexity:Legacy POS systems at aging terminals require costly retrofitting to interface with facial recognition boarding gates.
- Inventory localization:SKU rationalization across 200+ airport locations demands real-time demand forecasting capabilities most concessionaires lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Retailing Market |
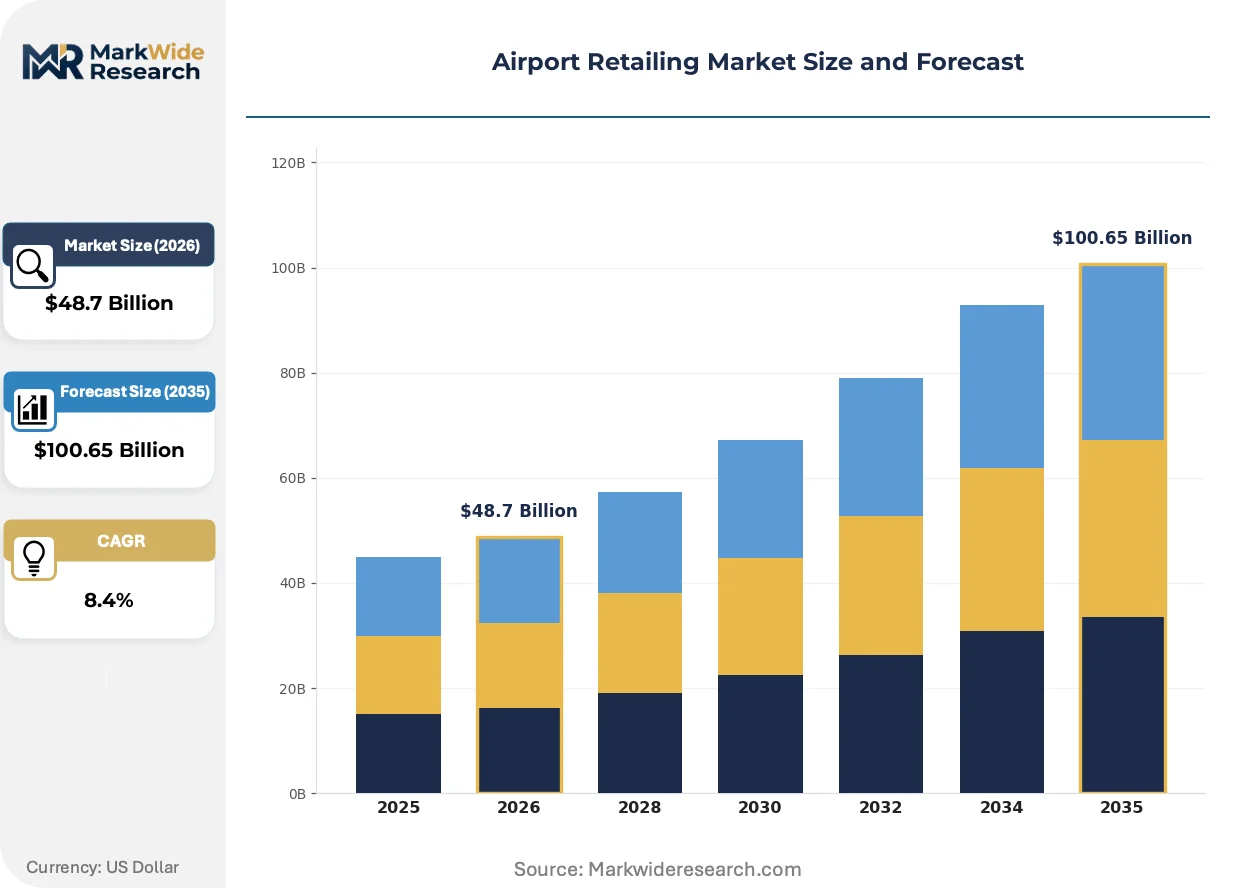
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Duty-Free Goods, Luxury Items, Travel Accessories, Snacks Customer Type: Leisure Travelers, Business Travelers, Airport Employees, VIP Customers Sales Channel: Retail Stores, Kiosks, Online Platforms, Airport Lounges Service Type: Concessionaires, Specialty Stores, Pop-Up Shops, Experience Zones |
| Companies Covered | Dufry AG, China Duty Free Group Co. Ltd., Avolta AG, Gebr. Heinemann SE & Co. KG, Aer Rianta International, DFS Group Ltd., Lagardère Travel Retail, Airport Retail Group LLC, Dubai Duty Free, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Retailing Market Strategic Shifts & Innovations
Experience-zone concepts are displacing traditional aisle-based retail, merging F&B, entertainment, and product discovery into contiguous passenger destinations that extend dwell time and basket size simultaneously.
RFID-enabled smart shelving is modularizing inventory tracking across duty-free cosmetics and spirits categories. Dufry and Avolta are deploying these systems at Singapore Changi and Zurich to enable real-time stock visibility without manual cycle counts. The technology is modularizing how concessionaires manage omnichannel fulfillment, compressing the gap between pre-order warehouses and gate-side collection points.
EMA and ECHA frameworks are tightening ingredient disclosure thresholds for European duty-free skincare. Concessionaires must now maintain parallel inventory streams: reformulated products for EU gates versus legacy formulations for Middle Eastern and Asian hubs. Fragrance and skincare segments are responding by consolidating suppliers who can manufacture dual-compliant SKUs from single production runs.
Leisure travelers now research duty-free pricing on mobile apps before airport arrival, collapsing the traditional impulse-purchase window. This behavior is fragmenting the passenger journey into pre-trip planning, security-to-gate transit, and lounge dwell phases. Chinese and UAE hubs are seeing the most pronounced shift, with pre-order platforms capturing 30-40% of transaction value before passengers reach terminal retail zones.
Airport Retailing Market Segmentation
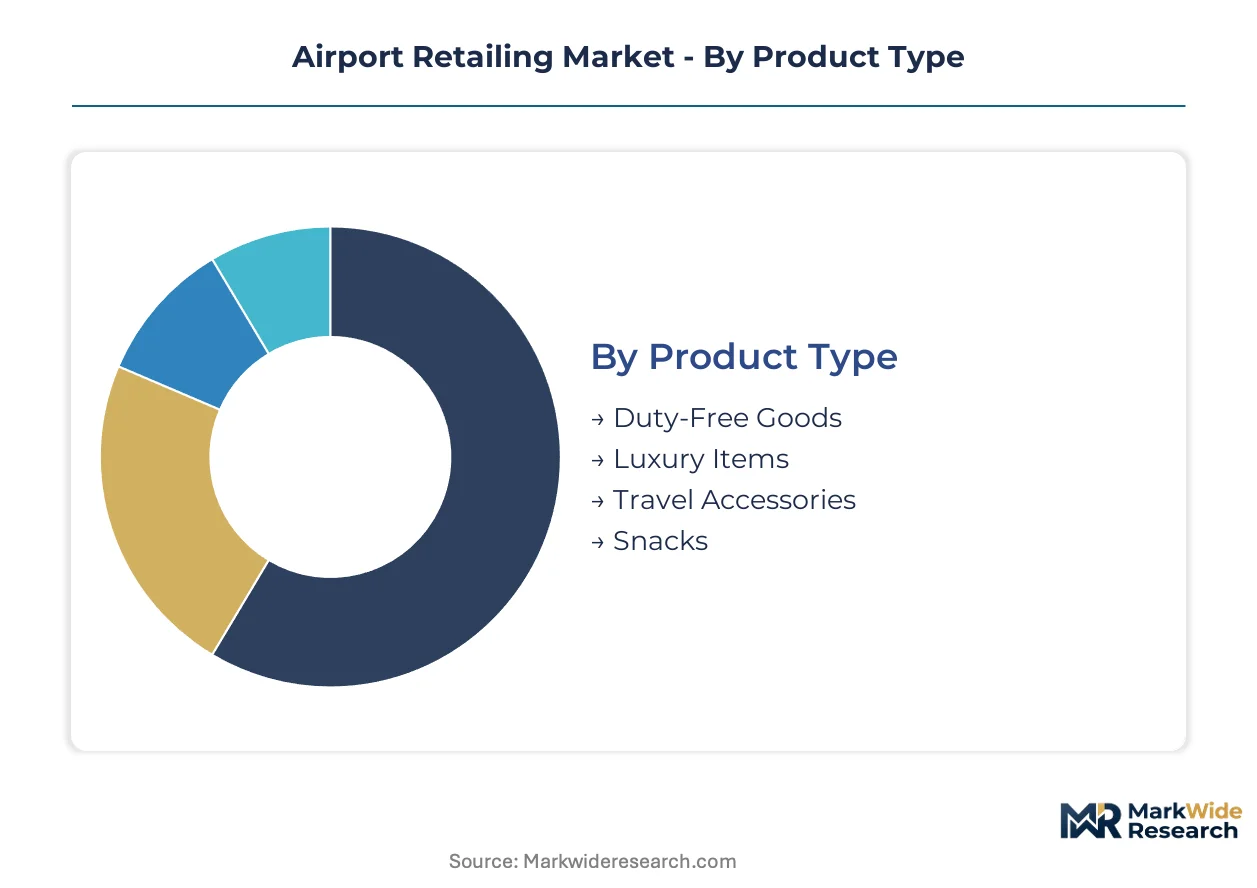
Airport retailing operates through layered segmentation where duty-exempt status, passenger dwell-time, and concession economics intersect. Each dimension shapes inventory allocation, lease negotiations, and technology deployment differently across terminal zones.
Product Type:
Standalone categories dominate revenue floors while embedded offerings integrate into passenger service flows.
- Duty-Free Goods:Comprising tobacco, spirits, and cosmetics sold under tax-exempt status, this segment anchors concession revenue through price arbitrage. Demand concentrates at Dubai International and Heathrow where minimum annual guarantees consume 18-25% of gross revenue, pressuring margin structures.
- Luxury Items:High-end watches, leather goods, and jewelry command premium positioning in high-traffic corridors. Chinese and UAE hubs drive volume as leisure travelers research pricing on mobile apps before arrival, collapsing traditional impulse-purchase windows.
- Travel Accessories:Electronics, luggage, and convenience items fill mid-tier terminal zones with functional, time-sensitive purchases.
- Snacks:Grab-and-go food and beverage items serve compressed transaction windows near boarding gates.
Volume placements concentrate in Duty-Free Goods; the faster expansion belongs to Luxury Items.
Customer Type:
Passenger economics stratify sharply between discretionary spenders and captive utilitarian buyers.
- Leisure Travelers:Extended dwell times and vacation mindsets drive basket size, with pre-order platforms capturing 30-40% of transaction value before terminal arrival at Chinese hubs.
- Business Travelers:Compressed schedules favor convenience-oriented purchases in lounge-adjacent retail zones.
- Airport Employees:Local demand for convenience goods operates outside duty-free frameworks with standard taxation.
- VIP Customers:Private terminal access enables personalized service and exclusive inventory access beyond security checkpoints.
Revenue concentration sits with Leisure Travelers; Business Travelers are expanding most quickly as premium cabin traffic recovers.
Sales Channel:
Physical footprint requirements vary dramatically between fixed retail and flexible fulfillment models.
- Retail Stores:Full-format concessions with dedicated staff and inventory depth anchor terminal revenue.
- Kiosks:Compact footprints near gates capture last-minute purchases with limited SKU breadth.
- Online Platforms:Pre-order functionality with gate-side collection compresses transaction time and extends sales windows beyond security constraints, climbing the fastest among channel options.
- Airport Lounges:Embedded retail within premium passenger zones targets high-yield captive audiences.
Fixed Retail Stores retain volume dominance; Online Platforms show the steepest expansion trajectory.
Service Type:
Operational models range from outsourced concession management to vertically controlled brand experiences.
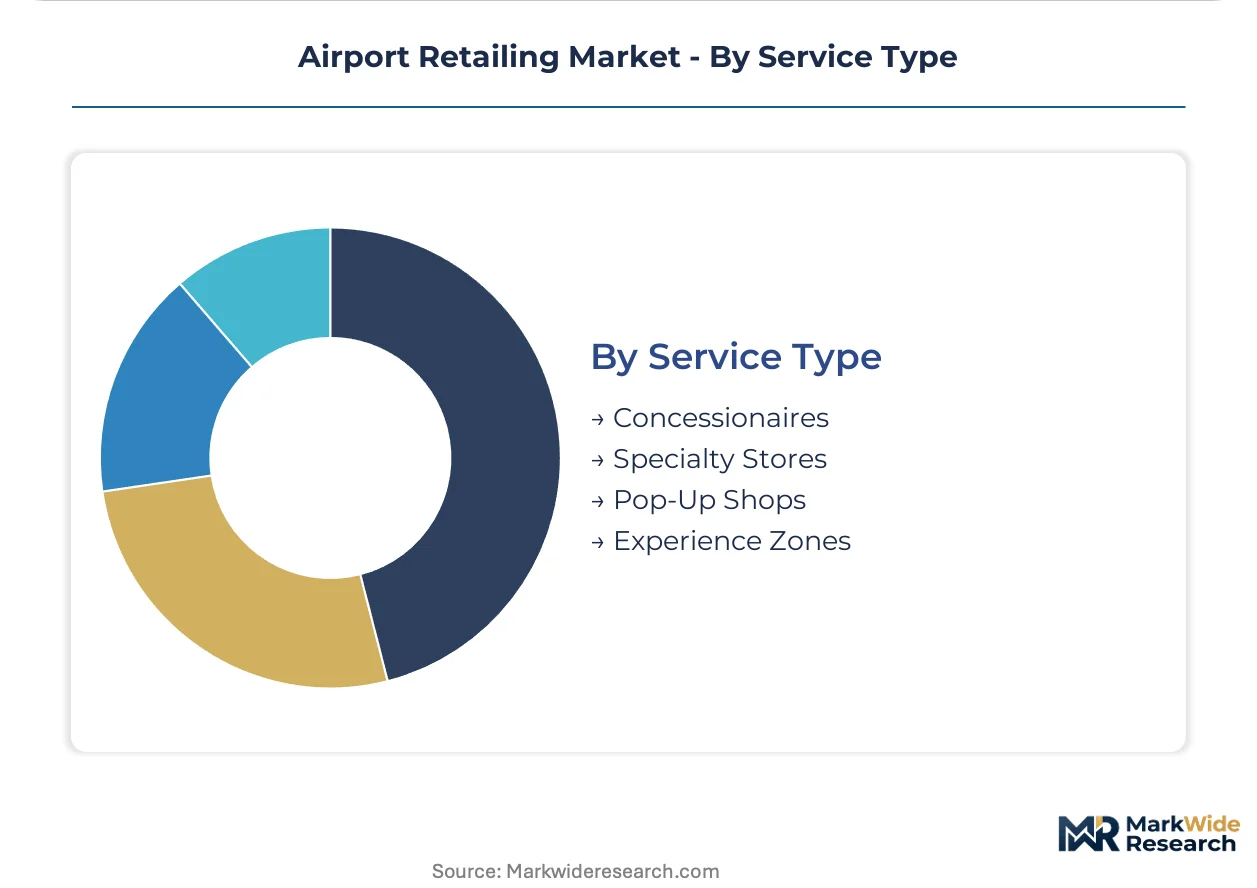
- Concessionaires:Revenue-sharing contracts with minimum annual guarantees dominate terminal economics, with Dufry and Avolta securing prime real estate through global network scale.
- Specialty Stores:Curated luxury assortments capture margin share through brand-direct relationships outside traditional concession structures.
- Pop-Up Shops:Temporary activations exploit seasonal traffic surges with flexible lease terms.
- Experience Zones:Merged F&B, entertainment, and product discovery concepts extend dwell time and basket size simultaneously at Singapore Changi and Zurich.
Concessionaires hold volume concentration; Experience Zones gain share fastest as dwell-time economics reshape terminal design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport retailing concentrates where passenger throughput intersects with duty-free policy liberalization. China consumes luxury inventory through offshore duty-free channels while the UAE and UK compete for transit-hub dominance through terminal expansion programs.
China
Hainan's offshore duty-free policy pulls luxury inventory toward mainland airport gateways. NMPA cosmetics registration requirements force reformulation timelines for international brands entering Shanghai Pudong and Beijing Daxia. The Yangtze River Delta cluster anchors pre-order platform adoption, with gate-side collection services capturing 30-40% of transaction value before terminal arrival.
United Arab Emirates
Dubai International's passenger volumes drive concession fee structures consuming 18-25% of gross revenue. MOHAP product registration mandates shape cosmetics and fragrance inventory selection for Emirates hub operations. Abu Dhabi International's terminal expansion creates competing premium corridor capacity within the same metropolitan catchment.
United Kingdom
Heathrow's minimum annual guarantee structures pressure concessionaire margins across duty-free spirits and tobacco. REACH chemical disclosure thresholds force parallel inventory streams for EU-compliant versus legacy formulations. London's terminal retail zones concentrate luxury watch and leather goods positioning for transatlantic business traffic.
United States
FDA cosmetic labeling requirements govern skincare claims sold at JFK and LAX duty-free locations. Domestic passenger volumes lack duty-exempt status, compressing price arbitrage opportunities versus international hubs. The Pacific Northwest corridor experiments with biometric payment integration at Seattle-Tacoma's renovated retail concourses.
Saudi Arabia
King Salman International Airport's retail masterplan offers first-mover positioning in underdeveloped premium corridors. SFDA product registration timelines extend inventory onboarding cycles versus established Gulf hubs. Riyadh's hub development competes with Jeddah for religious pilgrimage transit traffic with expanded duty-free allowances.
Airport Retailing Market Key Industry Players
The competitive structure tilts toward global concessionaires with scale-driven concession networks. Revenue-sharing contracts with minimum annual guarantees favor operators spanning 200-plus airport locations. Three archetypes dominate: diversified travel retail conglomerates, regional duty-free specialists, and airport-authority-affiliated operators. Geographic expansion and concession renewal timing constitute the dominant competitive moves, with prime terminal real estate securing multi-year revenue visibility.
Among global-scale concessionaires, Dufry AG, China Duty Free Group Co. Ltd., and Avolta AG occupy positions representing distinct strategic vectors. Dufry exemplifies the diversified network archetype through its concession footprint across European and American hub airports. China Duty Free Group represents the captive-supply model, leveraging policy-protected access to Hainan and mainland gateway inventory flows. Avolta sits within the experience-zone tier, merging retail operations with passenger dwell-time entertainment concepts at Singapore Changi and Zurich. Gebr. Heinemann SE & Co. KG and Lagardère Travel Retail anchor mid-tier positioning through specialized regional concentration.
| Leading Market Players |
|---|
| Dufry AG |
| China Duty Free Group Co. Ltd. |
| Avolta AG |
| Gebr. Heinemann SE & Co. KG |
| Aer Rianta International |
| DFS Group Ltd. |
| Lagardère Travel Retail |
| Airport Retail Group LLC |
| Dubai Duty Free |
| Others |
Cost & Logistics Intelligence
Leisure travelers concentrated at Chinese and UAE hubs drive revenue-sharing concession contracts where minimum annual guarantees consume substantial gross revenue shares, tethering pricing power to passenger throughput volatility and duty-free policy arbitrage.
Pricing Analysis
Margin tightening in luxury inventory reflects LVMH, Richemont, and Kering's control over high-margin supply, compressing assortment differentiation for concessionaires. Three-tier pricing structure across premium, standard, and economy levels stratifies by brand tier and dwell-time zone proximity. Pricing pressure stems from concession fee escalation at Dubai International and Heathrow. Leisure travelers show lowest price sensitivity due to vacation mindsets, while business travelers exhibit highest sensitivity to time-compressed transactions.
Supply Chain Analysis
Air freight costs for luxury cosmetics and spirits hinge on temperature-controlled lanes from France, Switzerland, and Italy into duty-free distribution hubs. Inventory draws from dual-compliant production runs serving EU REACH mandates alongside legacy formulations for Middle Eastern and Asian gates. Single-source vulnerability concentrates in LVMH-dominated fragrance supply. Distribution runs through Dufry and Avolta's warehouse networks into gate-side collection points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport retailing is becoming a vertical-integration race where concessionaires pursue captive supply agreements with luxury houses to secure margin control and inventory priority.
For Market Incumbents: Hedge concession renewal exposure by securing multi-hub concession clusters that dilute single-airport revenue concentration. Deepen backward integration into experience-zone development at Singapore Changi and Zurich to capture dwell-time economics beyond traditional retail footprints.
For New Entrants and Emerging Players: The mid-market price-point gap between luxury concessions and convenience kiosks offers white-space positioning for curated travel accessory concepts. Target Saudi Arabia's King Salman International Airport retail masterplan before incumbent saturation. Deploy pre-order platform partnerships as the primary go-to-market angle to bypass prime real estate barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional duty-free specialists with concentrated Middle Eastern or Southeast Asian footprints during concession renegotiation windows. Long-term viability rests on biometric integration capabilities and AI-driven personalization infrastructure. Monitor biometric boarding adoption rates at Chinese and UAE hubs as the inflection signal for technology-forward concessionaire valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Experience Zone Development | Merges F&B and entertainment to extend passenger dwell time at Singapore Changi and Zurich terminals. |
| Biometric Payment Integration | Compresses transaction windows and enables facial recognition loyalty systems at Seattle-Tacoma and Dubai International. |
| Dual-Compliant Inventory Sourcing | Secures REACH-compliant cosmetics supply for EU gates while maintaining legacy formulations for Asian hubs. |
| Pre-Order Platform Expansion | Captures 30-40% of transaction value before terminal arrival through gate-side collection services. |
| Sustainable Sourcing Certification | Aligns with EU Green Deal mandates to secure preferential lease terms across European airport authorities. |
Research Approach
Trade databases, customs records, and airport authority concession filings formed the secondary backbone for this analysis. Primary interviews with concession operations directors, luxury brand retail strategists, airport procurement managers, and duty-free regulatory consultants validated demand assumptions. Bottom-up passenger throughput modeling triangulated against top-down concession revenue estimates.
Historical trendline analysis across passenger volume, concession fee structures, and duty-free policy changes established baseline growth patterns. Segmentation dimensions spanned product category, passenger type, sales channel, and service model across the projection horizon. CAGRs derived from elasticity modeling between passenger traffic recovery curves and per-passenger retail spend benchmarks. Forecast inputs incorporated biometric boarding adoption timelines and Hainan duty-free policy evolution.
Inputs from airport authority disclosure documents and concessionaire financial filings were available through the study window; gaps in real-time inventory velocity data introduce uncertainty bands around pre-order platform penetration assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Myanmar Residential Real Estate Market
Real Estate
US Property Management Software Market
Real Estate
Indonesia Real Estate Market
Real Estate
Panama Facility Management Market
Real Estate
Canada Condominiums and Apartments Market
Real Estate
North America Soft Facility Management Market
Real Estate
Canada Residential Real Estate Market
Real Estate
Saudi Arabia Office Real Estate Market
Real Estate
United States Real Estate Services Market
Real Estate
Bahrain Co-Working Office Space Market
Real Estate
Germany Manufactured Homes Market
Real Estate
Property Management Software Market
Real Estate
Romania Facility Management Market
Real Estate
Residential Real Estate Market
Real Estate
Canada Real Estate Services Market
Real Estate
Global Facility Management Software Market