
 Agave Nectar Market | 2026-2036
Agave Nectar Market Size, Share, and Industry Trends Forecast 2026-2036
Agave Nectar Market Analysis
USDA Organic certification is unwinding competitive access for suppliers lacking verified supply chain documentation. Wholesome Sweeteners Inc. leverages its established organic certification infrastructure to sustain premium shelf placement across North American retail channels. NOW Health Group, Inc. anchors its market position through vertical integration into supplement-grade agave sourcing, while Ciranda, Inc. specializes in bulk organic ingredient distribution to mid-sized food manufacturers.
Agave nectar constitutes a viscous sweetener extracted primarily from Agave tequilana and Agave salmiana species, containing approximately 60-90% fructose with a glycemic index substantially lower than sucrose, produced through enzymatic hydrolysis of agave pinas or thermal concentration of raw sap. The ingredient serves commercial applications spanning beverage formulation, baked goods, and condiment manufacturing where clean-label positioning drives procurement decisions. Organic agave nectar commands the dominant value share as consumer willingness-to-pay for certified organic sweeteners outpaces conventional alternatives, while raw agave nectar captures accelerating growth among paleo and minimally-processed diet adherents. The food and beverage end-user segment concentrates the majority of volume offtake, though pharmaceutical and nutraceutical applications are deepening as excipient-grade specifications mature.
FDA nutrition labeling requirements for added sugars disclosure reshape formulation transparency expectations across the supply chain, while USDA National Organic Program standards govern certification integrity for premium product tiers. Mexico's Secretariat of Agriculture and Rural Development (SADER) regulates agave cultivation permits and geographical indication protections that constrain raw material expansion outside designated zones. Stakeholders must monitor evolving EU regulatory classifications for novel sweeteners under EFSA evaluation protocols, as potential reclassification would alter import tariff structures and competitive access for non-EU suppliers.
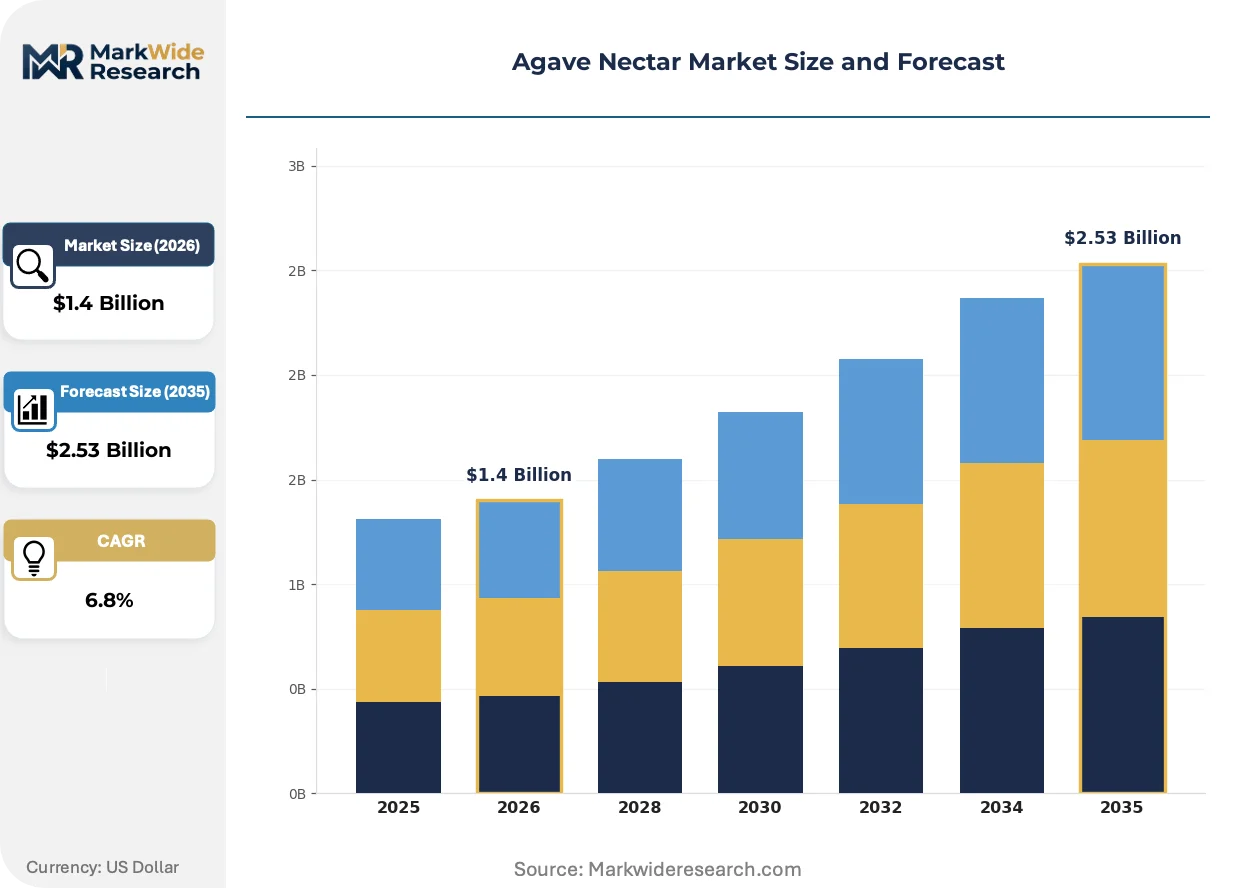
Market Dynamics
USDA Organic certification requirements and FDA labeling standards for natural sweeteners are tightening compliance thresholds, forcing suppliers to document verified supply chains or exit premium shelf placement. This regulatory compression concentrates procurement power among certified processors while raising barriers for new entrants lacking established organic infrastructure.
Growth Catalysts
- Clean-label beverage formulation:Beverage manufacturers in the United States and Europe are reformulating with agave nectar to meet consumer demand for low-glycemic sweeteners. FDA added sugars disclosure rules accelerate this substitution pattern.
- REACH and EU Green Deal alignment:European food manufacturers prioritize certified organic inputs to satisfy EFSA evaluation protocols and sustainability reporting under CSRD. This creates preferential procurement for compliant Mexican suppliers.
- Raw agave nectar processing:Minimal thermal concentration methods preserve enzymatic activity and appeal to paleo diet adherents. This processing innovation expands addressable demand beyond conventional sweetener buyers.
Market Restraints
- Blue agave monoculture concentration:Jalisco region in Mexico supplies the majority of raw material, creating geographic single-point-of-failure risk. Climate vulnerability and agave maturation cycles amplify supply volatility.
- Fructose metabolic scrutiny:Nutritional science debates around high-fructose sweetener health impacts generate regulatory friction. EFSA novel food classifications could trigger re-evaluation of import tariff structures.
- Enzymatic hydrolysis input costs:Commercial enzyme prices fluctuate with biotechnology feedstock markets. Thermal concentration alternatives require capital-intensive evaporator infrastructure.
Strategic Opportunities
- Pharmaceutical excipient-grade specifications:Nutraceutical manufacturers in Germany and Switzerland seek USP-grade agave syrup for tablet binding and coating applications. This vertical commands price premiums over food-grade supply.
- Carbon accounting integration:EU CSRD mandatory climate disclosures incentivize food manufacturers to source from SADER-permitted cultivation zones with verified low-carbon transport routes.
- Direct-to-bakery distribution:Artisan bakeries in France and Italy bypass traditional ingredient distributors through specialized organic importers. This channel compression captures margin previously allocated to wholesale tiers.
Industry Challenges
- Organic certification timeline compression:USDA National Organic Program transition periods extend 36 months for new cultivation sites. Existing suppliers with grandfathered certification maintain procurement advantages during this gap.
- Agave piña quality grading standardization:Absence of unified brix and purity metrics across Jalisco processing cooperatives creates batch inconsistency. Food manufacturers reject shipments that fail internal specification thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agave Nectar Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Agave Nectar, Raw Agave Nectar, Processed Agave Nectar, Light Agave Nectar End User: Food & Beverage, Personal Care, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Application: Baking, Sweetening, Sauces, Beverages |
| Companies Covered | The Agave Sweetener Company, Wholesome Sweeteners Inc., NOW Health Group, Inc., Malt Products Corporation, Ciranda, Inc., Groovy Food Company Ltd, Whole Earth Brands Inc., Arizona Beverages USA, LLC, Sisana Sweeteners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agave Nectar Market Emerging Trajectories
Enzymatic processing advances and regulatory transparency mandates are reconfiguring how agave nectar moves from cultivation to formulation. These shifts favor suppliers with documented supply chains and flexible processing capabilities.
Cold-pressed raw agave extraction is displacing thermal concentration in premium positioning. Specialty food manufacturers in California and Oregon specify enzymatically hydrolyzed syrup with minimal heat exposure. This processing method preserves native inulin content and commands shelf placement in natural channel retailers.
EFSA novel food evaluation protocols under the EU regulatory framework are reshaping import compliance requirements. Non-EU suppliers must submit comprehensive toxicological dossiers for fructose-rich sweetener classifications. German and Dutch food manufacturers front-load regulatory preparation to avoid customs detention at Rotterdam and Hamburg ports.
Buyer concentration among certified organic distributors is compressing supplier negotiation leverage. Mid-sized food manufacturers in Spain and Italy consolidate procurement through Ciranda and comparable bulk organic ingredient specialists. This channel consolidation rewards processors with USDA Organic and EU Organic dual certification.
Agave Nectar Market Segmentation
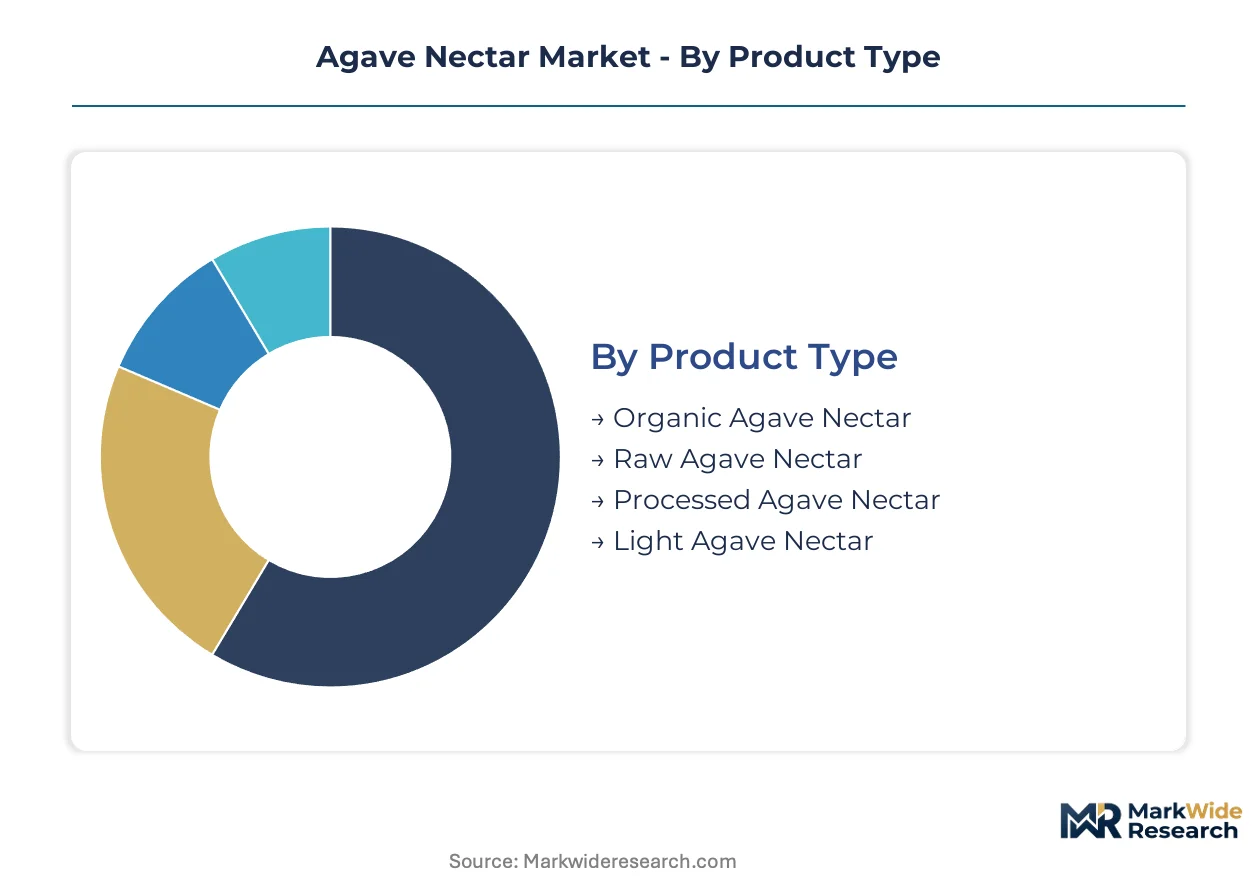
Agave nectar procurement decisions pivot on certification tiers, end-use specifications, and channel economics. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
USDA Organic and EU Organic certification requirements create tiered access thresholds that separate premium shelf placement from commodity positioning.
- Organic Agave Nectar:Derived from SADER-permitted cultivation zones with verified supply chain documentation meeting USDA National Organic Program standards. Beverage manufacturers in the United States and Germany prioritize certified organic inputs to satisfy clean-label procurement mandates and avoid FDA added sugars disclosure penalties.
- Raw Agave Nectar:Minimal thermal concentration preserves native inulin and enzymatic activity, appealing to paleo diet adherents and minimally-processed food formulators. Specialty retailers in California and Oregon command shelf placement premiums for enzymatically hydrolyzed syrup with documented heat exposure below threshold levels.
- Processed Agave Nectar:Standard thermal concentration achieves consistent brix specifications for industrial food manufacturing.
- Light Agave Nectar:Filtered variant with reduced color and flavor intensity for neutral sweetening applications.
Established volume favors Organic Agave Nectar; emerging adoption favors Raw Agave Nectar.
End User:
Formulation specifications diverge sharply between food-grade flexibility and pharmaceutical-grade purity requirements.
- Food & Beverage:Dominates volume offtake through clean-label reformulation across beverage, bakery, and condiment manufacturing. FDA added sugars disclosure rules accelerate substitution patterns in the United States, while EU Green Deal alignment drives certified organic procurement in Germany and France.
- Pharmaceuticals:USP-grade specifications for tablet binding and coating command price premiums over food-grade supply. Swiss and German nutraceutical manufacturers seek excipient-grade agave syrup with documented purity metrics and batch consistency.
- Personal Care:Humectant properties drive formulation in natural cosmetics and skincare products.
- Nutraceuticals:Functional positioning as prebiotic fiber source expands addressable demand beyond conventional sweetener applications.
Food & Beverage anchors current revenue concentration; Pharmaceuticals delivers the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture versus volume scale tradeoffs for processors at different certification tiers.
- Supermarkets:Mass retail placement requires dual USDA Organic and EU Organic certification for premium tier access, with slotting fees favoring established suppliers with grandfathered documentation.
- Specialty Stores:Natural channel retailers in France and Italy specify cold-pressed raw agave with minimal heat exposure, bypassing conventional wholesale tiers through direct importer relationships.
- Online Retail:Direct-to-consumer channels enable margin capture for artisan processors lacking supermarket scale.
- Food Service:Bulk procurement by restaurant chains and institutional buyers prioritizes cost efficiency over certification premiums.
Supermarkets concentrate premium pricing power; Specialty Stores are climbing the fastest in per-unit margin realization.
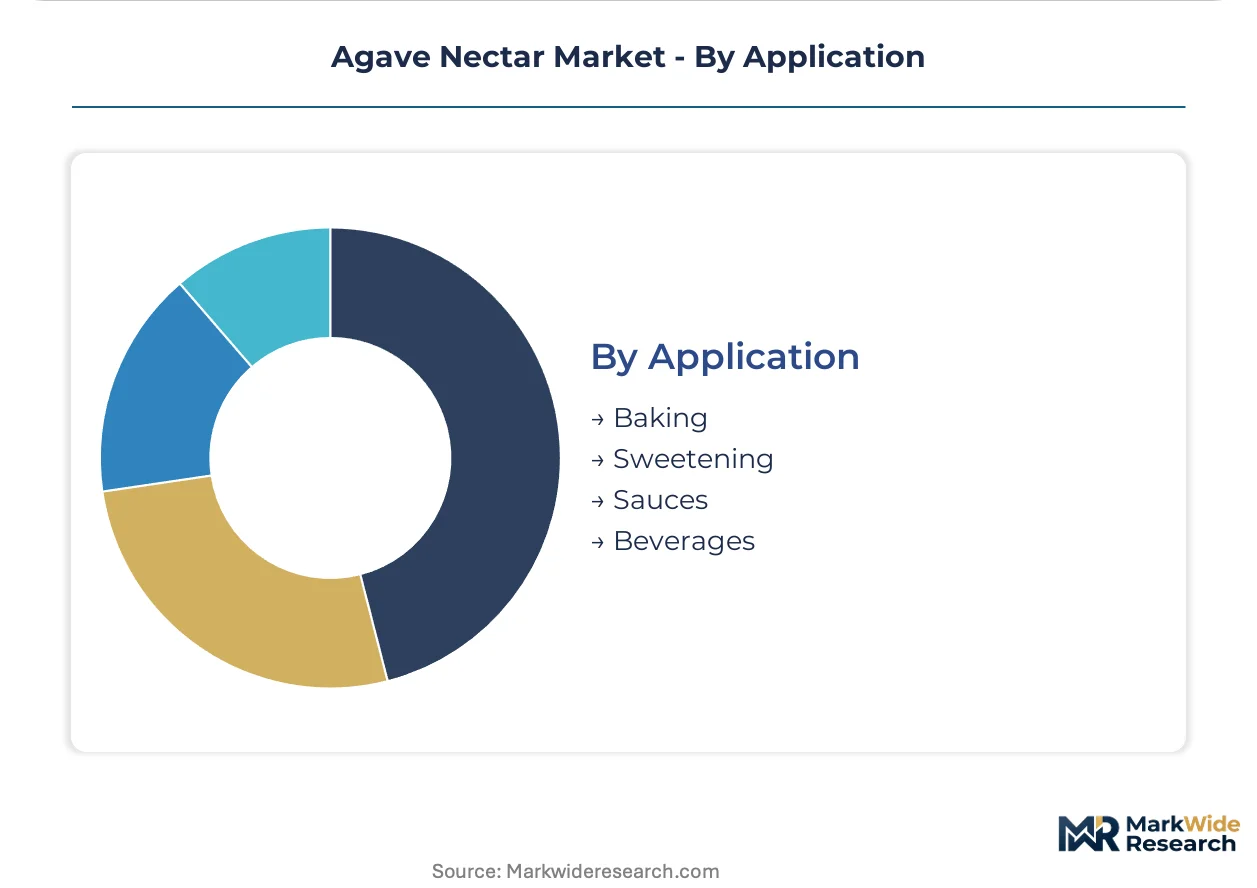
Application:
Functional requirements range from thermal stability in industrial baking to flavor neutrality in neutral beverage bases.
- Beverages:Low-glycemic positioning drives reformulation in carbonated soft drinks, ready-to-drink teas, and functional beverages. Clean-label demands from California and Oregon manufacturers accelerate enzymatically hydrolyzed syrup adoption.
- Baking:Maillard reaction compatibility and moisture retention properties suit artisan bakery applications in France and Italy.
- Sweetening:Direct table-top use competes with honey and maple syrup in natural product retail channels.
- Sauces:Viscosity and sheen enhancement for condiment and dressing manufacturing.
Beverages dominates formulation innovation investment; Baking shows strongest growth in certified organic ingredient penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Manzanillo handles the majority of agave nectar export volumes from Mexico's Pacific coast, connecting Jalisco cultivation zones to Pacific Rim markets. This maritime infrastructure underwrites Mexico's dominance in raw material supply while European and North American processing clusters compete for finished product value capture.
United States
Beverage manufacturers in California and Oregon drive clean-label reformulation with agave nectar as a low-glycemic alternative. FDA added sugars disclosure rules accelerate substitution patterns across carbonated soft drinks and ready-to-drink teas. Los Angeles and Portland anchor West Coast formulation clusters where enzymatically hydrolyzed syrup specifications command premium procurement.
Germany
EFSA evaluation protocols under the EU Green Deal reshape import compliance for fructose-rich sweeteners entering Rotterdam and Hamburg ports. German nutraceutical manufacturers in Bavaria seek USP-grade agave syrup for tablet binding applications. Munich and Stuttgart concentrate pharmaceutical excipient demand with documented purity requirements.
Mexico
SADER cultivation permits constrain blue agave expansion outside Jalisco's designated geographical indication zones. The Tequila-Arandas corridor processes raw piña through enzymatic hydrolysis for export-grade syrup. Guadalajara anchors the concentration of organic certification infrastructure serving North American premium channels.
France
Artisan bakeries in Paris and Lyon bypass traditional wholesale tiers through direct relationships with specialized organic importers. EU CSRD mandatory climate disclosures incentivize sourcing from SADER-permitted zones with verified low-carbon transport routes. Île-de-France concentrates natural channel retail placement for cold-pressed raw variants.
Switzerland
Swissmedic excipient-grade specifications command price premiums over food-grade supply for nutraceutical applications. Basel and Zurich anchor pharmaceutical manufacturing clusters requiring batch consistency documentation. Swiss buyers front-load regulatory preparation to avoid customs detention under evolving EFSA novel food classifications.
Agave Nectar Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and channel access dimensions. The supplier base concentrates around established organic processors with grandfathered USDA documentation, while new entrants face 36-month transition timelines for cultivation site certification. Three archetypes dominate: vertically integrated cultivator-processors, bulk organic ingredient distributors, and supplement-grade specialists. Competitive moves center on dual certification acquisition and direct-to-bakery channel compression.
Within the certified organic tier, Wholesome Sweeteners Inc. and NOW Health Group, Inc. exemplify divergent positioning strategies. Wholesome Sweeteners occupies a position anchored in retail shelf placement infrastructure, while NOW Health Group represents upstream control into supplement-grade sourcing specifications. Ciranda, Inc. sits within the bulk distribution archetype, serving mid-sized food manufacturers with dual USDA-EU Organic certification. These three entities collectively illustrate how regulatory documentation and channel selection separate premium positioning from commodity supply.
| Leading Market Players |
|---|
| The Agave Sweetener Company |
| Wholesome Sweeteners Inc. |
| NOW Health Group, Inc. |
| Malt Products Corporation |
| Ciranda, Inc. |
| Groovy Food Company Ltd |
| Whole Earth Brands Inc. |
| Arizona Beverages USA, LLC |
| Sisana Sweeteners |
| Others |
Supply Flow & Price Mechanics
USDA National Organic Program standards gate both supply qualification and price differentiation simultaneously, separating grandfathered certified processors from entrants facing 36-month transition timelines while commanding shelf placement premiums in North American retail channels.
Pricing Analysis
Volume-discount tiering structures stratify across organic certification grade, with dual USDA-EU Organic certification commanding the steepest premiums over single-certified or conventional supply. Price differentiation rests on enzymatic processing method and thermal exposure documentation, with cold-pressed raw variants capturing margin premiums from paleo-positioned buyers. Cost compression in conventional processed tiers is intensifying because of enzymatic input price volatility and evaporator infrastructure amortization. Food service buyers exhibit the highest price sensitivity, while pharmaceutical nutraceutical manufacturers demonstrate the least due to USP-grade purity requirements.
Supply Chain Analysis
Inventory lead times stretch across agave piña maturation cycles spanning 7-10 years, creating procurement planning horizons unmatched by annual crop commodities. Geographic supply concentrates in Mexico's Jalisco region, with secondary processing clusters in the United States and Germany. Raw material dependencies draw from blue agave monoculture, commercial enzyme feedstocks, and organic certification infrastructure. Single-source vulnerability runs through SADER-permitted cultivation zones concentrated in the Tequila-Arandas corridor. Distribution runs through bulk organic ingredient specialists serving mid-sized food manufacturers and direct-to-bakery importers bypassing wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against monk fruit and allulose sweeteners penetrating clean-label beverage formulations, requiring strategic repositioning around certification moats and processing differentiation.
For Market Incumbents: Consolidate procurement advantages by locking multi-year offtake agreements with SADER-permitted Jalisco cooperatives before transition timelines expire for new entrants. Deepen backward integration into enzymatic hydrolysis capacity to capture margin from cold-pressed raw agave demand expansion. Defend against monk fruit substitution by embedding USDA Organic certification into retailer slotting contracts.
For New Entrants and Emerging Players: Anchor in pharmaceutical excipient-grade specifications where USP purity requirements and Swissmedic documentation create defensible niche positioning away from commodity food-grade competition. Target artisan bakery channels in France and Italy through direct importer relationships that bypass established wholesale consolidation. Pursue carbon accounting integration as the go-to-market angle for EU CSRD-compliant manufacturers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dual-certification processing infrastructure as 36-month organic transition timelines extend effective payback periods. Long-term viability favors processors with grandfathered USDA documentation and established SADER cultivation permits rather than greenfield entrants. The acquisition target archetype is vertically integrated Jalisco-based processors with captive organic acreage and existing EU export relationships. Watch EFSA novel food reclassification protocols as the signal for potential tariff structure disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Acquisition | USDA-EU Organic dual certification unlocks premium shelf placement in California and German retail channels. |
| Backward Integration into Cultivation | SADER-permitted acreage in Jalisco secures raw material supply against climate-induced piña volatility. |
| Pharmaceutical Grade Specification | USP-grade purity documentation commands price premiums from Swiss and German nutraceutical manufacturers. |
| Direct-to-Bakery Distribution | Channel compression captures margin from Paris and Lyon artisan bakeries bypassing wholesale tiers. |
| Cold-Pressed Processing Investment | Minimal thermal concentration methods preserve inulin content for paleo-positioned California specialty retailers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across beverage formulation executives, organic certification auditors, SADER cultivation permit holders, and pharmaceutical excipient procurement managers. Secondary validation drew from FDA added sugars disclosure filings, USDA National Organic Program operator databases, EFSA novel food evaluation dossiers, and SADER geographical indication registries. Bottom-up volume estimates from Jalisco processing cooperatives were triangulated against top-down demand assessments from North American and European food manufacturers.
Across the analysis window, forecasts model product type segmentation by certification tier and processing method, end user segmentation by food-grade versus pharmaceutical-grade specifications, and distribution channel segmentation by mass retail versus specialty direct. CAGRs were derived from elasticity-adjusted demand projections incorporating clean-label reformulation rates and regulatory disclosure compliance timelines. Industry-specific inputs include agave piña maturation cycle dynamics and enzymatic hydrolysis capacity expansion pipelines.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA added sugars disclosure enforcement and stable SADER cultivation permit allocations; material deviation in EFSA reclassification or Jalisco climate patterns would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Sugar Syrups Market
Sweeteners
China Saccharin Market
Sweeteners
India Food Sweetener Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Oligofructose Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Sugar Polyols Market
Sweeteners
Maltodextrin Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Icing Sugar Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Sugar Alcohol Market