
 3D Printed Jewelry Market | 2026-2036
3D Printed Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Jewelry Market Analysis
Mass-market retail consumers is collapsing as a dominant buyer archetype while high-net-worth collectors and bespoke design studios gain share in 3D printed jewelry procurement. NERVOUS SYSTEM specializes in algorithmically generated botanical forms that command premium positioning in museum retail channels. Shapeways, Inc. operates a distributed manufacturing network that extends on-demand production to independent designers lacking capital equipment. Materialise anchors European medical-grade metal printing expertise that transfers directly to biocompatible jewelry alloys.
3D printed jewelry comprises ornamental and decorative objects fabricated through additive manufacturing processes, typically employing precious metals, photopolymer resins, or thermoplastic filaments deposited in layer thicknesses ranging from 25 to 100 microns to achieve intricate lattice geometries impossible through lost-wax casting. The primary commercial purpose centers on enabling mass customization, reducing material waste by 30-40% versus subtractive methods, and compressing design-to-delivery cycles from weeks to days. Rings dominate current revenue pools due to sizing complexity that additive workflows resolve without inventory risk, while SLA technology leads precision outcomes for fine filigree work where surface finish determines retail price realization. Gold and silver materials concentrate margin capture among bullion-integrated producers with direct refining relationships.
FDA oversight of direct metal laser sintering for implantable devices creates downstream certification pathways that jewelry producers leverage for hypoallergenic claims, while REACH restrictions on nickel release and cadmium content shape European material sourcing decisions. In the United States, FTC jewelry marking requirements and EPA emissions standards for precious metal powder handling add compliance layers that favor capitalized producers over artisan entrants. Stakeholders must monitor evolving ISO/ASTM additive manufacturing standards as these frameworks increasingly incorporate consumer product safety protocols that will determine market access for cross-border digital design platforms.
Market Dynamics
Direct-to-consumer additive manufacturing programs at luxury fashion houses are compressing traditional wholesale channels while Shenzhen production clusters absorb design-to-print workflows for export fulfillment.
Growth Catalysts
- REACH compliance tightening:European nickel release and cadmium content restrictions are forcing material certification upgrades that premium producers leverage for hypoallergenic positioning.
- SLA precision advancement:Layer thickness control below 50 microns enables fine filigree geometries impossible through lost-wax casting, unlocking museum retail channels.
- China production clustering:Shenzhen-based facilities integrate cloud-native design platforms with same-day metal sintering capacity for North American and European direct shipping.
Market Restraints
- Precious metal powder volatility:Gold and silver feedstock price swings compress margin buffers for producers lacking direct refining relationships or bullion-integrated supply.
- Equipment capex concentration:Direct metal laser sintering systems require seven-figure capital deployment, restricting installed base to venture-backed studios and luxury house captive operations.
- FDA certification pathway friction:Biocompatible alloy claims require implantable-device-grade documentation timelines that extend 18-24 months for jewelry-specific applications.
Strategic Opportunities
- India bridal customization:Untapped demand for algorithmically generated mandala geometries in 22-karat gold presents white space for design-to-print platforms targeting wedding registry channels.
- Medical-grade alloy transfer:Materialise's European biocompatible expertise transfers directly to nickel-free jewelry production, opening dermatological retail partnerships.
- Algorithmic design retail:NERVOUS SYSTEM's botanical generative models demonstrate premium positioning in museum shops, replicable for independent designer marketplaces.
Industry Challenges
- ISO/ASTM standardization lag:Evolving additive manufacturing safety protocols lack jewelry-specific consumer product guidelines, creating cross-border platform compliance uncertainty.
- Powder handling EPA compliance:US emissions standards for precious metal particulate require specialized ventilation infrastructure that artisan entrants cannot finance.
- Design-to-print workflow integration:Legacy CAD tools lack native lattice optimization, forcing manual file preparation that extends delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Jewelry Market |
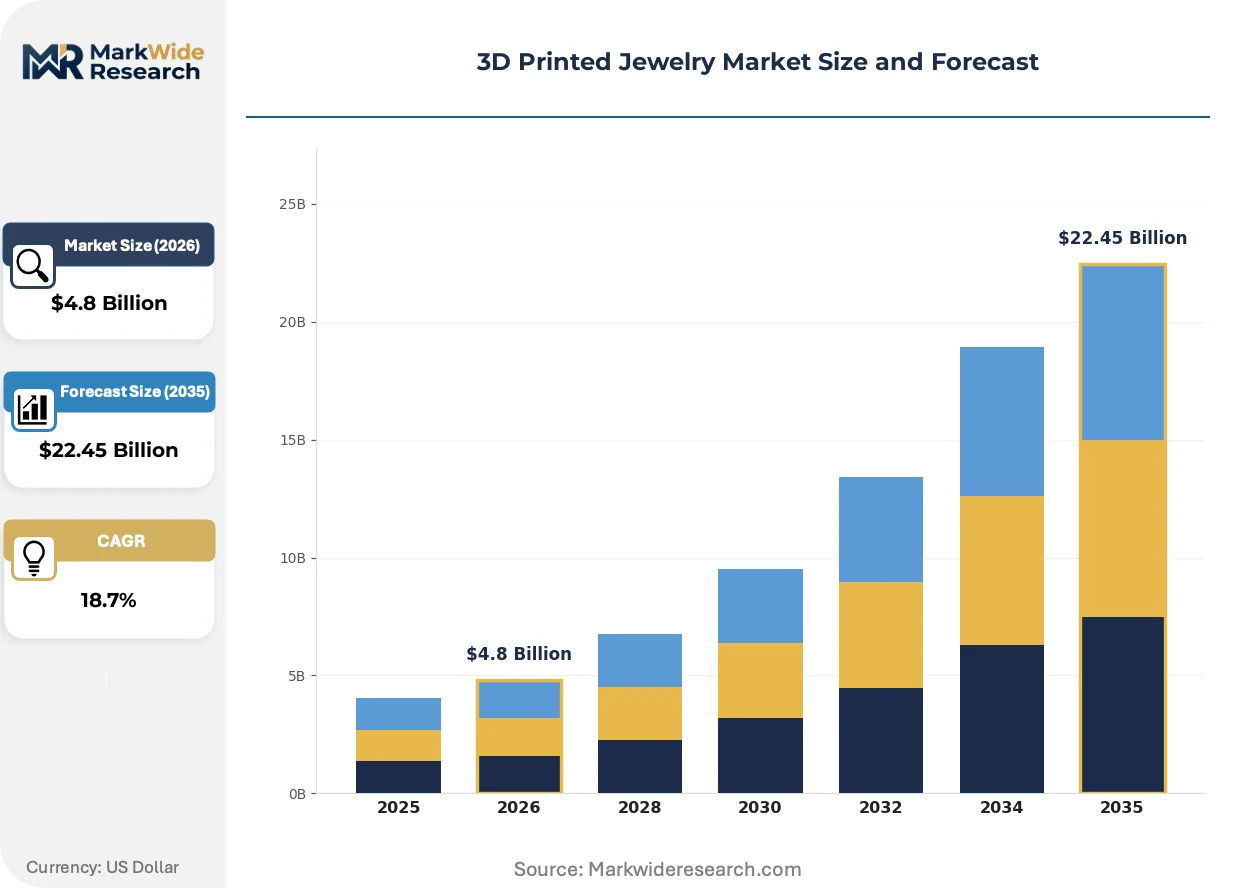
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Earrings, Bracelets Material: Silver, Gold, Resin, Plastic Technology: SLA, SLS, FDM, Binder Jetting End User: Retail Consumers, Designers, Manufacturers, Artisans |
| Companies Covered | Imaginarium, MIRAKIN, EnvisionTEC, NERVOUS SYSTEM, RADIAN, Shapeways, Inc., Stratasys, Materialise, OLA Jewelry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Jewelry Market Emerging Trajectories
Generative design algorithms and distributed manufacturing networks are collapsing the traditional jewelry value chain from months to days while regulatory frameworks scramble to catch up with material safety claims.
Micro-resolution stereolithography is miniaturizing feature sizes for filigree work below 100 microns. High-net-worth collectors and bespoke studios are adopting these capabilities fastest, displacing traditional hand-engraving ateliers in Geneva and Paris. Surface finish quality now determines retail price realization more than metal weight alone.
REACH restrictions on nickel release are reshaping European material sourcing decisions. ECHA enforcement actions against non-compliant imports have triggered supplier audits throughout Shenzhen production clusters. German and French retailers now require batch-specific migration test certificates before listing 3D printed alloy pieces.
Mass-market retail procurement is fragmenting toward direct-to-consumer platforms. Independent designers bypass wholesale distributors through Shapeways distributed nodes, collapsing traditional 40-60% retailer markups. This channel compression is most visible in North American urban markets where same-week customization expectations have normalized.
3D Printed Jewelry Market Segmentation
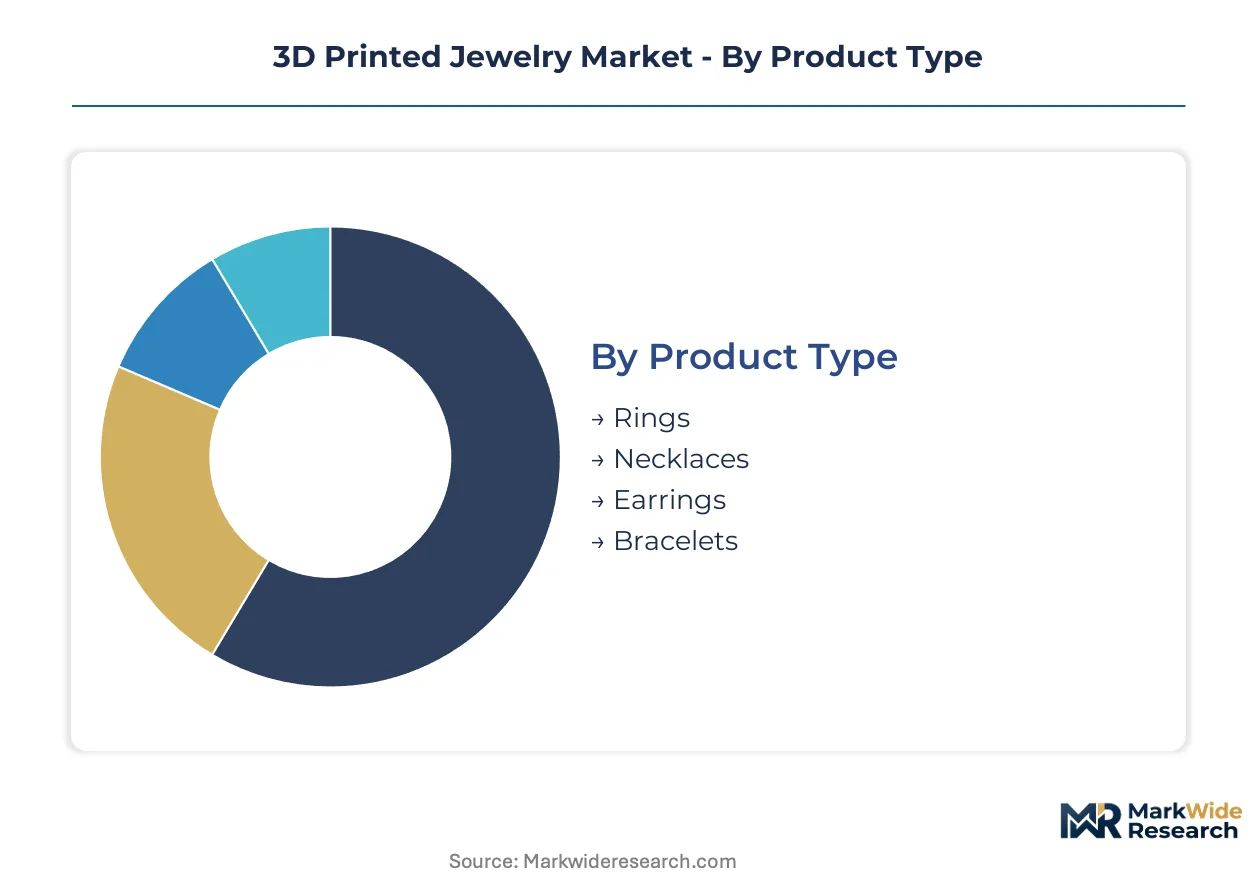
Segmentation in 3D printed jewelry reveals how additive workflows reshape procurement patterns across product categories and buyer archetypes. Material selection and technology choice determine which segments capture margin versus volume in this expanding market.
Product Type:
Rings face the most acute substitution pressure from traditional casting as sizing complexity becomes additive's signature advantage, while bracelets and necklaces compete against established handmade alternatives.
- Rings:Layer-by-layer fabrication resolves sizing complexity without inventory risk, compressing design-to-delivery cycles from weeks to days. Demand concentrates among bespoke design studios in North American urban markets where same-week customization expectations have normalized.
- Necklaces:Algorithmically generated pendant geometries enable mass customization at price points unattainable through hand-engraving ateliers. High-net-worth collectors drive procurement through museum retail channels seeking botanical and mandala-inspired forms.
- Earrings:Lightweight lattice structures reduce material consumption by 30-40% versus subtractive methods.
- Bracelets:Cuff and bangle forms leverage direct metal laser sintering for complex articulation mechanisms.
Rings retain volume leadership; necklaces hold the steepest expansion curve.
Material:
Cost tier stratification separates bullion-integrated producers from resin-based entrants, with precious metal volatility dictating margin resilience across the category.
- Silver:Most accessible precious metal for independent designers entering distributed manufacturing networks. Shenzhen production clusters dominate supply integration with cloud-native design platforms for North American direct shipping.
- Gold:22-karat alloys command premium positioning in bridal registry channels, particularly for algorithmically generated geometries. Indian wedding markets present untapped white space for design-to-print platforms targeting mandala-inspired customization.
- Resin:Photopolymer formulations enable sub-50 micron layer thickness for fine filigree work at accessible price points.
- Plastic:Thermoplastic filaments serve costume jewelry segments with rapid prototyping turnaround.
Silver dominates current volume; gold carries the highest margin capture potential.
Technology:
Application-specific precision requirements segment the installed base, with surface finish quality determining retail price realization more than build speed.
- SLA:Stereolithography achieves layer thickness control below 50 microns for museum-grade filigree surface finish. European REACH compliance on nickel release favors SLA-produced biocompatible resins for hypoallergenic claims.
- SLS:Selective laser sintering of nylon and polymer powders enables durable, flexible geometries for articulating components. German and French retailers require batch-specific migration test certificates before listing SLS alloy pieces.
- FDM:Fused deposition modeling serves entry-level prototyping with thermoplastic filament cost advantages.
- Binder Jetting:Powder-bed processes accelerate metal production throughput for scaled direct-to-consumer fulfillment.
SLA commands premium positioning; binder jetting scales fastest for mass customization.
End User:
Customer type fragmentation reflects collapsing wholesale channels, with capital equipment access separating venture-backed studios from artisan entrants.
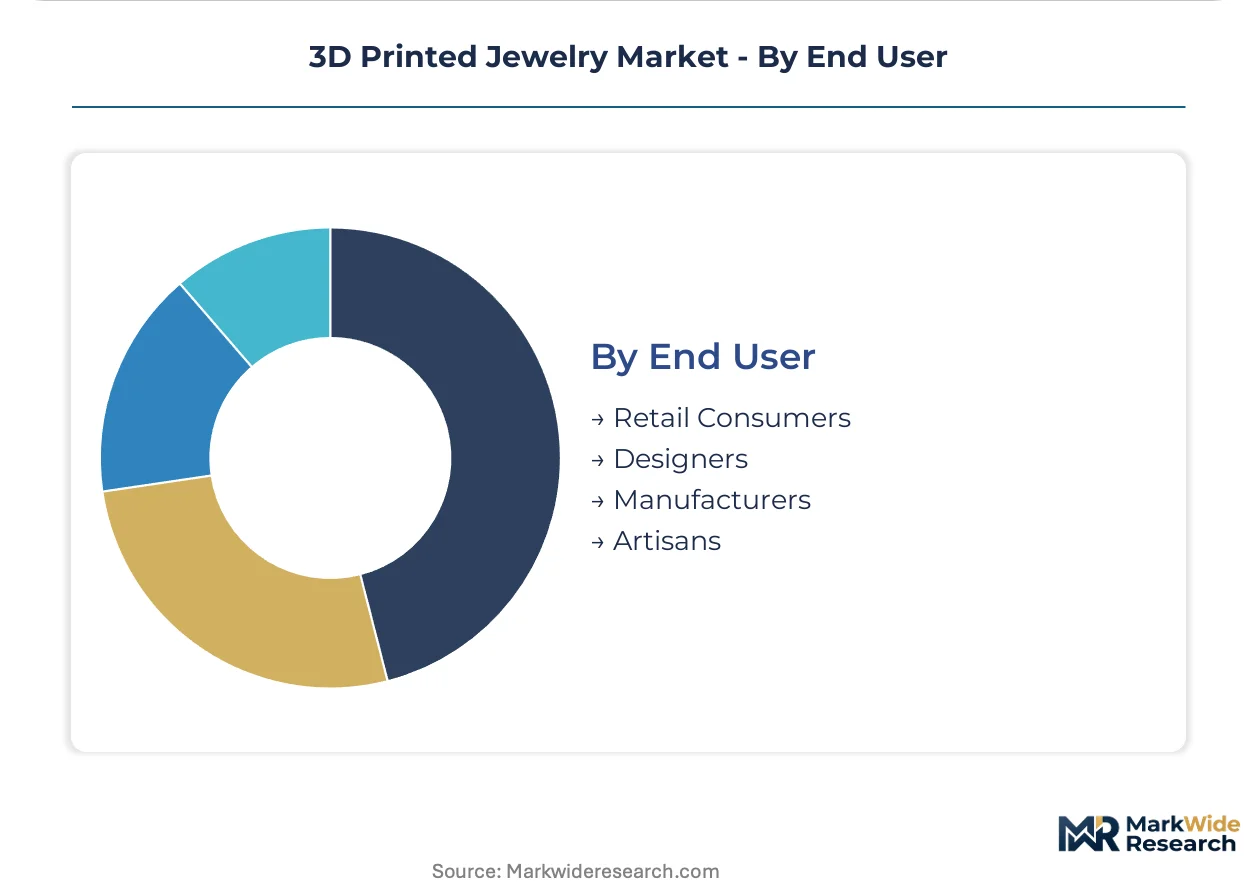
- Retail Consumers:Direct-to-consumer platforms bypass traditional 40-60% retailer markups through distributed manufacturing nodes. Same-week customization expectations have normalized in North American urban markets.
- Designers:Independent creators leverage cloud-native design platforms integrated with Shenzhen same-day metal sintering capacity. Algorithmic generative models demonstrate premium positioning in museum shop channels.
- Manufacturers:Luxury fashion houses deploy captive direct metal laser sintering systems requiring seven-figure capital deployment.
- Artisans:Individual makers face EPA emissions standards for precious metal powder handling that favor capitalized producers.
Retail consumers drive current volume; designers represent the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen production clusters ship finished pieces directly to North American and European consumers, compressing traditional wholesale channels into single-origin export corridors.
United States
High-net-worth collectors in New York and Los Angeles drive bespoke procurement through museum retail channels. FTC jewelry marking requirements and EPA emissions standards for precious metal powder handling favor capitalized producers over artisan entrants. Brooklyn-based design studios integrate with distributed manufacturing nodes for same-week customization fulfillment.
China
Shenzhen facilities absorb cloud-native design platforms for export markets demanding algorithmically generated geometries. MIIT standards on additive manufacturing equipment certification shape domestic production quality benchmarks. Guangdong province metal sintering clusters now offer same-day turnaround for North American direct shipping.
Germany
REACH compliance on nickel release and cadmium content forces material certification upgrades across imported alloy pieces. ECHA enforcement actions have triggered supplier audits throughout Asian production networks. Frankfurt and Munich retailers now require batch-specific migration test certificates before listing 3D printed jewelry.
India
Untapped bridal demand for 22-karat gold mandala geometries presents white space for design-to-print platforms targeting wedding registry channels. BIS hallmarking requirements on precious metal purity create documentation layers for imported additive pieces. Mumbai and Surat jewelry trading hubs are integrating algorithmic design tools for export-oriented production.
France
Luxury fashion houses in Paris deploy captive direct metal laser sintering systems requiring seven-figure capital deployment. ANSM oversight of biocompatible materials creates downstream certification pathways for hypoallergenic jewelry claims. Lyon and Grenoble production facilities transfer medical-grade alloy expertise into nickel-free consumer collections.
3D Printed Jewelry Market Vendor Landscape
Player mix skews toward venture-backed studios and luxury house captive operations, with seven-figure equipment capex restricting installed base concentration. The structure fragments across three tiers: algorithmic design specialists, distributed manufacturing platforms, and vertically integrated precious metal refiners. Strategic moves center on M&A for cloud-native design platform acquisition and geographic expansion through Shenzhen production partnerships.
Within the algorithmic design specialist tier, NERVOUS SYSTEM and RADIAN exemplify botanical generative models commanding premium museum retail positioning. Shapeways, Inc. anchors the distributed manufacturing archetype, extending on-demand production to independent designers lacking capital equipment. Materialise occupies the medical-grade alloy transfer position, leveraging European biocompatible expertise for dermatological retail partnerships.
| Leading Market Players |
|---|
| Imaginarium |
| MIRAKIN |
| EnvisionTEC |
| NERVOUS SYSTEM |
| RADIAN |
| Shapeways, Inc. |
| Stratasys |
| Materialise |
| OLA Jewelry |
| Others |
Supply Flow & Price Mechanics
REACH nickel release and cadmium content restrictions gate both European market access and hypoallergenic premium positioning simultaneously, forcing material certification investments that stratify producers by compliance tier and pricing power. Bullion-integrated refiners with direct precious metal sourcing capture margin buffers unavailable to resin-based entrants or distributed manufacturing nodes.
Pricing Analysis
Prior-generation FDM thermoplastic filament systems anchor economy pricing at entry-level costume jewelry tiers, while current-generation SLA precision workflows command museum retail premiums for sub-50 micron filigree surface finish, and next-generation direct metal laser sintering with biocompatible alloy certification targets luxury bridal registry channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and vertical integration depth. Cost compression in standard-tier resin production intensifies because Shenzhen production clusters absorb cloud-native design platforms for same-day fulfillment. Mass-market retail consumers exhibit highest price sensitivity, while high-net-worth collectors purchasing through museum channels demonstrate lowest elasticity.
Supply Chain Analysis
China anchors precious metal powder production and same-day sintering capacity for North American direct shipping, Germany concentrates REACH-compliant alloy certification and medical-grade expertise transfer, and India supplies 22-karat gold feedstock for bridal customization markets. Raw material dependencies draw from gold and silver bullion markets, photopolymer resin formulations, and nickel-free alloy compositions. Single-source vulnerability concentrates in Shenzhen production clusters where ECHA enforcement actions have triggered supplier audit cascades. Distribution runs through direct-to-consumer platforms that collapse traditional 40-60% retailer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward high-net-worth collectors and bespoke design studios as mass-market retail procurement fragments, with independent designers leveraging distributed manufacturing nodes to bypass wholesale markups entirely.
For Market Incumbents: Secure direct refining relationships with bullion-integrated suppliers to defend margin buffers against precious metal powder volatility, and invest in REACH-compliant biocompatible alloy certification to maintain European market access against tightening ECHA enforcement timelines. Shapeways distributed manufacturing networks represent an emerging entrant archetype threatening captive production models. For New Entrants and Emerging Players: FDA biocompatible certification fast-track for implantable-device-grade documentation creates dermatological retail partnership pathways for hypoallergenic jewelry claims, opening white space in nickel-free collections. Target India bridal customization demand for algorithmically generated 22-karat gold mandala geometries through wedding registry channel partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across direct metal laser sintering equipment deployment, favoring venture-backed studios over artisan entrants unable to finance seven-figure capex. Algorithmic design platform specialists with museum retail channel access represent priority acquisition archetypes. Signal to watch: MIIT certification timelines for Chinese additive manufacturing equipment exports.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatible Alloy Certification | FDA implantable-device-grade documentation unlocks hypoallergenic premium positioning in dermatological retail partnerships. |
| Cloud-Native Design Platform Integration | Shenzhen production clusters absorb same-day metal sintering workflows for North American direct-to-consumer fulfillment. |
| Museum Retail Channel Partnership | Algorithmic generative models from botanical specialists command premium placement displacing traditional hand-engraving ateliers. |
| Backward Integration into Bullion Refining | Direct precious metal sourcing relationships buffer margin compression from gold and silver feedstock price volatility. |
| REACH Compliance Investment | ECHA enforcement actions on nickel release force batch-specific migration test certificates for European market access. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with additive manufacturing equipment operators, jewelry design studio founders, museum retail procurement managers, and precious metal refining executives; and secondary validation against MIIT equipment certification databases, ECHA REACH enforcement records, FDA biocompatibility guidance documents, and customs trade data for precious metal powder imports. Bottom-up and top-down triangulation cross-checked production capacity estimates against end-user procurement patterns.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, material tier, technology generation, and end-user archetype, with CAGRs derived from historical production volume trajectories and forward-looking equipment installation data. Key inputs incorporated cloud-native design platform adoption curves and REACH regulatory enforcement intensity indices.
Underlying assumptions cover sustained precious metal price volatility and ECHA certification timeline stability, with deviation risk concentrated in FDA biocompatibility pathway revisions and MIIT export certification delays. Recalibration cycles align with material shifts in regulatory enforcement patterns and equipment technology transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Japan Jewellery Market
Jewelry
China Luxury Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Smart Jewelry Market
Jewelry
Bead Products Market
Jewelry
China Jewellery Market
Jewelry
Imitation Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Body Jewelry Market
Jewelry
Chalcedony Earrings Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Europe Luxury Jewelry Market