
 3D Fighting Games Market | 2026-2036
3D Fighting Games Market Size, Share, and Industry Trends Forecast 2026-2036
3D Fighting Games Market Insights
Buyer concentration across the 3D Fighting Games Market is rebalancing from traditional retail purchasers toward digital platform holders and streaming audiences. Capcom leverages its proprietary RE Engine to sustain visual fidelity across competitive and story mode releases. Bandai Namco Entertainment anchors its position through the Tekken franchise's enduring tournament circuit presence. NetherRealm Studios differentiates via cinematic narrative integration within one-on-one formats.
3D fighting games constitute interactive software built on real-time polygonal rendering engines, frame-precise input detection systems, and netcode infrastructure enabling sub-20ms latency for competitive viability. Their commercial purpose centers on monetizing skill-based player engagement through base sales, seasonal content passes, and cosmetic microtransactions. The platform dimension shows console installations commanding the deepest monetization pools while VR represents the fastest-growing addressable base. Character design stratifies across realistic military aesthetics and fantasy anime archetypes, with the latter capturing dominant share in East Asian markets.
The US ESRB rating system, China's MIIT content approval framework, and the EU's GDPR data handling standards collectively shape release cadences, age-gating mechanics, and cross-border player data architecture. Japan's CERO rating board additionally influences violence depiction thresholds for titles targeting its domestic arcade sector. Stakeholders must monitor emerging platform commission structures and regional content localization mandates as determinants of profitable market entry sequencing.
Market Dynamics
Netcode infrastructure standardization is fragmenting competitive viability hierarchies across the 3D Fighting Games Market. Publishers now face capital allocation tradeoffs between rollback implementation costs and tournament circuit licensing returns.
Growth Catalysts
- Esports Broadcasting Rights:Streaming platforms are securing exclusive tournament distribution agreements. These contracts expand addressable audiences beyond installed player bases.
- MIIT Content Approval Acceleration:China's Ministry of Industry and Information Technology has streamlined import title review timelines. Reduced approval backlogs enable synchronized global release windows.
- Cross-Platform Matchmaking:Unified player pools across console ecosystems compress matchmaking latency. Network effect density improves player retention curves.
Market Restraints
- Rollback Netcode Development Costs:Frame-precise latency compensation engineering requires specialized systems programming talent. Compensation premiums for netcode specialists inflate development budgets.
- Arcade Hardware Supply Concentration:Japan's dedicated cabinet manufacturing base remains concentrated among three domestic fabricators. Geographic supplier density creates vulnerability to component shortages.
- Input Latency Standards Divergence:Console manufacturers maintain incompatible controller polling specifications. Cross-platform parity engineering consumes disproportionate QA resources.
Strategic Opportunities
- VR Arcade Installations:Location-based entertainment venues in South Korea are deploying haptic-feedback fighting pods. Immersive hardware differentiation commands premium per-session pricing.
- Cloud Gaming Infrastructure:Microsoft's Azure and Amazon's AWS game server stacks enable browser-based competitive play. Reduced hardware barriers expand emerging market penetration.
- GDPR-Compliant Analytics Frameworks:EU-mandated data handling protocols are creating certification moats for privacy-first matchmaking systems. Regulatory compliance becomes competitive differentiation.
Industry Challenges
- Netcode Engineering Talent Scarcity:Frame-precise multiplayer systems programming expertise concentrates among veterans of competitive fighting game studios. Recruitment pipelines for this specialization remain underdeveloped.
- Cross-Platform Certification Complexity:Sony, Microsoft, and Nintendo maintain divergent technical certification requirements. Simultaneous multi-platform launches require redundant compliance testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Fighting Games Market |
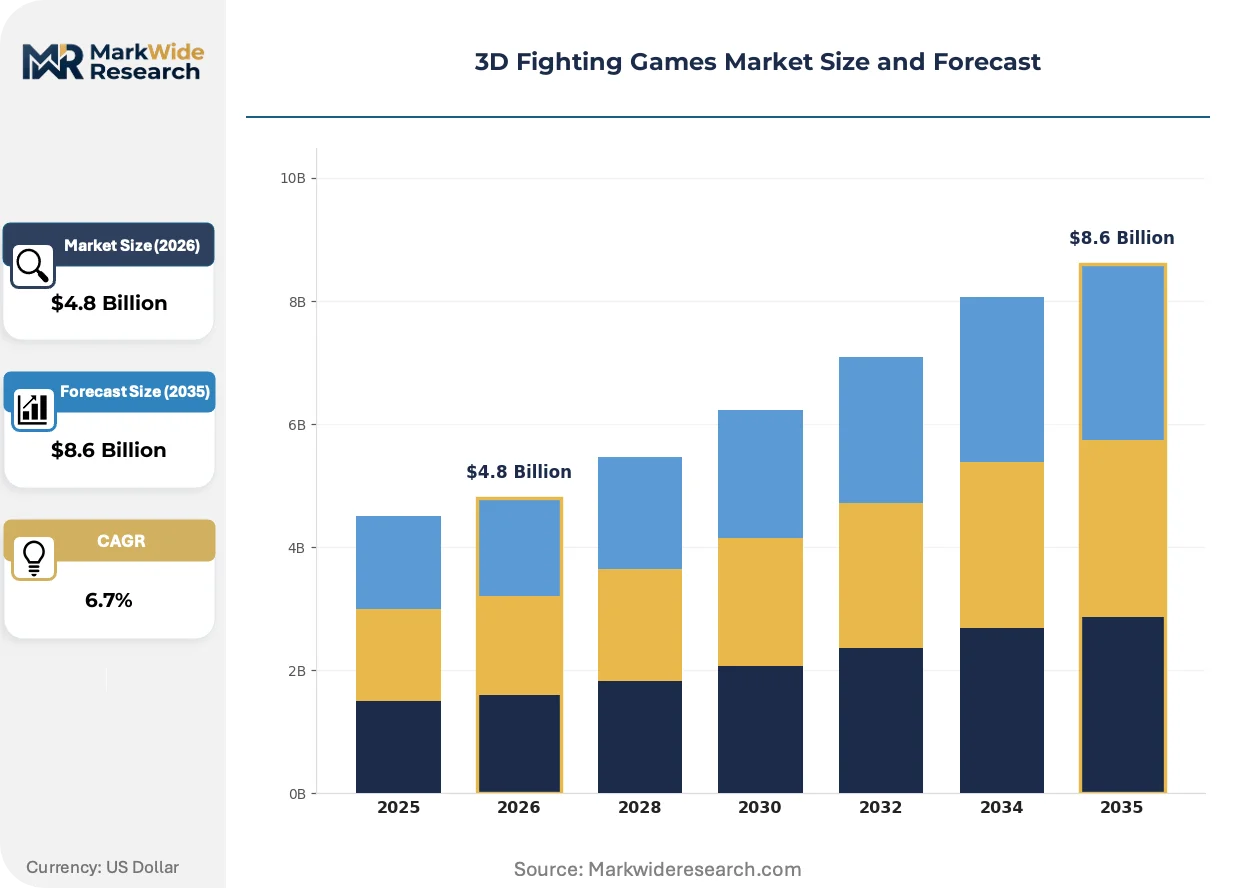
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Arcade, Competitive, Casual, Multiplayer Platform: Console, PC, Mobile, VR Character Design: Realistic, Cartoonish, Fantasy, Historical Gameplay Style: Team-Based, One-on-One, Battle Royale, Story Mode |
| Companies Covered | Project Soul, Sega, Capcom, Nintendo, WB Games, Bandai Namco Entertainment, Arc System Works, Atari, NetherRealm Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Fighting Games Market Trends and Innovations
Rollback netcode implementation is redistributing competitive viability hierarchies across publisher portfolios. This technical shift compresses the performance gap between AAA budgets and mid-tier releases.
Rollback netcode is decentralizing tournament circuit access across publisher tiers. Mid-sized studios without proprietary infrastructure now license open-source latency compensation frameworks. The competitive viability threshold is compressing from engine investment scale toward netcode implementation quality.
China's MIIT content approval framework is reshaping release cadence synchronization strategies. Import title review timelines now determine global marketing spend allocation sequencing. Publishers targeting China's domestic arcade sector are front-loading localization resources to align with approval windows.
Streaming platform exclusivity is fragmenting tournament viewership distribution models. Amazon's Twitch and Google's YouTube are securing multi-year broadcast rights for premier competitive circuits. This channel disintermediation is compressing traditional esports league revenue shares while expanding total addressable spectator bases in Southeast Asian markets.
3D Fighting Games Market Segmentation
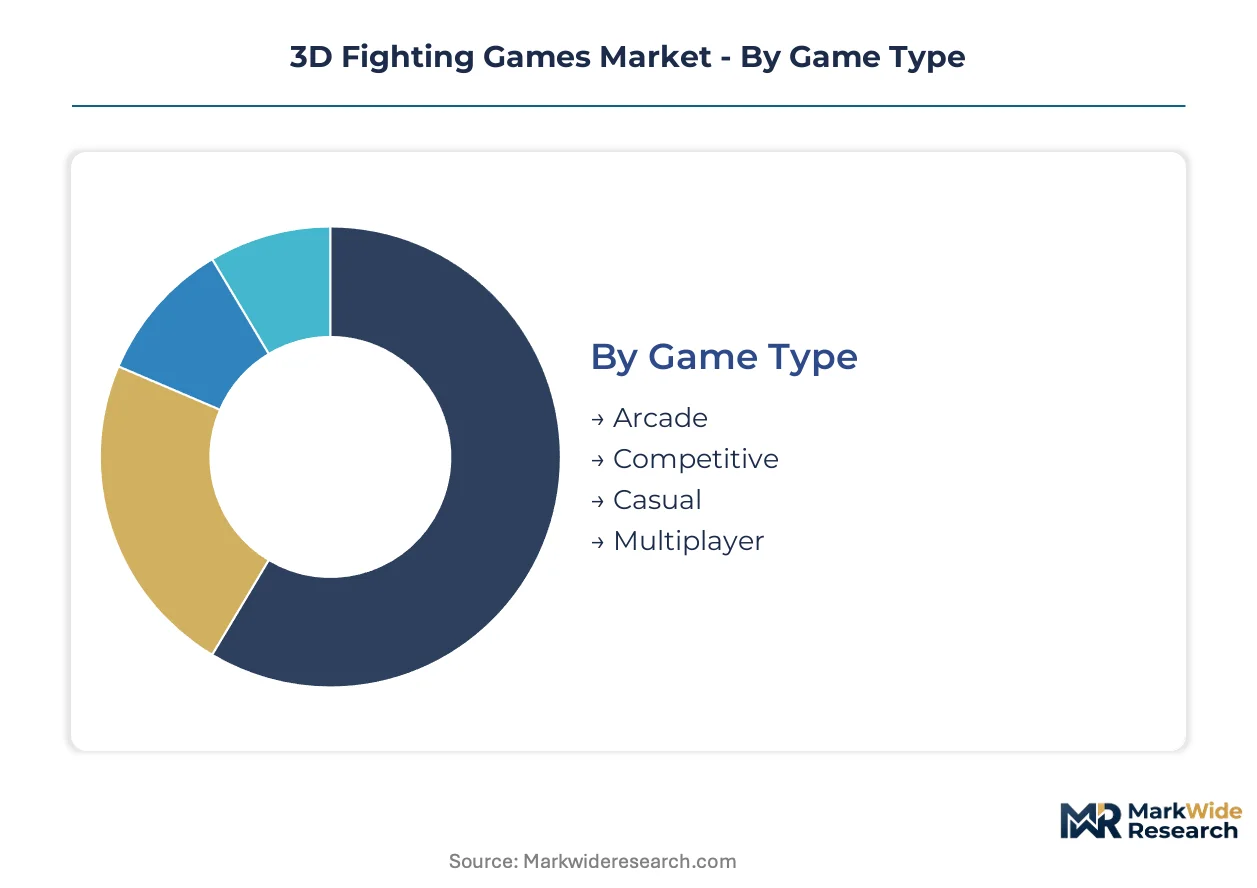
Segmentation in 3D fighting games determines capital allocation across engine development, netcode infrastructure, and content pipeline investments. Publishers calibrate release strategies against platform holder certification requirements and regional content approval frameworks. Each segment carries distinct technical specifications that shape monetization architecture and competitive viability.
Game Type:
Arcade releases face Japan's CERO rating board scrutiny for cabinet violence thresholds, while competitive titles must satisfy ESRB and PEGI standards for tournament broadcast licensing. Casual and multiplayer formats navigate China's MIIT content approval timelines for synchronized global windows.
- Arcade:Dedicated cabinet hardware demands frame-precise input detection below 16.67ms for 60Hz refresh synchronization. Demand concentrates in Japan's arcade-to-console ecosystem, where Bandai Namco Entertainment anchors tournament circuit presence through Tekken franchise installations.
- Competitive:Rollback netcode implementation enables sub-20ms latency compensation for ranked matchmaking integrity. Esports broadcasting rights from streaming platforms expand addressable audiences beyond installed player bases in Southeast Asian markets.
- Casual:Simplified input buffers attract crossover audiences from adjacent genres.
- Multiplayer:Cross-platform matchmaking infrastructure unifies player pools across console ecosystems.
Leading the category by volume: Competitive. Expanding most quickly: Multiplayer.
Platform:
Console manufacturers enforce divergent technical certification requirements that inflate QA resource allocation for simultaneous multi-platform launches. PC and mobile segments operate under less restrictive distribution gatekeeping but face fragmented hardware optimization challenges.
- Console:Sony, Microsoft, and Nintendo each maintain proprietary controller polling specifications that demand redundant parity engineering. Monetization pools run deepest here through base sales and seasonal content passes in the US and Japanese markets.
- PC:Open hardware configurations require adaptive graphics scaling across GPU generations. Steam's distribution dominance in Western markets enables direct-to-consumer pricing control bypassing retail margin extraction.
- Mobile:Touch input latency constraints limit competitive viability to casual formats.
- VR:Haptic-feedback fighting pods in South Korean location-based entertainment venues command premium per-session pricing.
Deepest monetization: Console. Steepest expansion trajectory: VR.
Character Design:
Visual aesthetic selection shapes regional content approval complexity and localization resource requirements. Fantasy and anime archetypes face streamlined review in East Asian markets, while realistic military designs trigger heightened scrutiny under multiple rating frameworks.
- Fantasy:Anime-influenced archetypes dominate East Asian market share through established merchandising pipelines. China's domestic arcade sector shows particular concentration for this aesthetic cluster.
- Realistic:Military and martial arts authenticity demands motion capture investment for competitive player acceptance. Western markets prefer this design language for tournament credibility and broadcast accessibility.
- Cartoonish:Stylized proportions reduce polygon count requirements for mobile optimization.
- Historical:Period-accurate costume design requires regional cultural consultant engagement for approval compliance.
Regional share leader: Fantasy. Gaining share fastest: Realistic.
Gameplay Style:
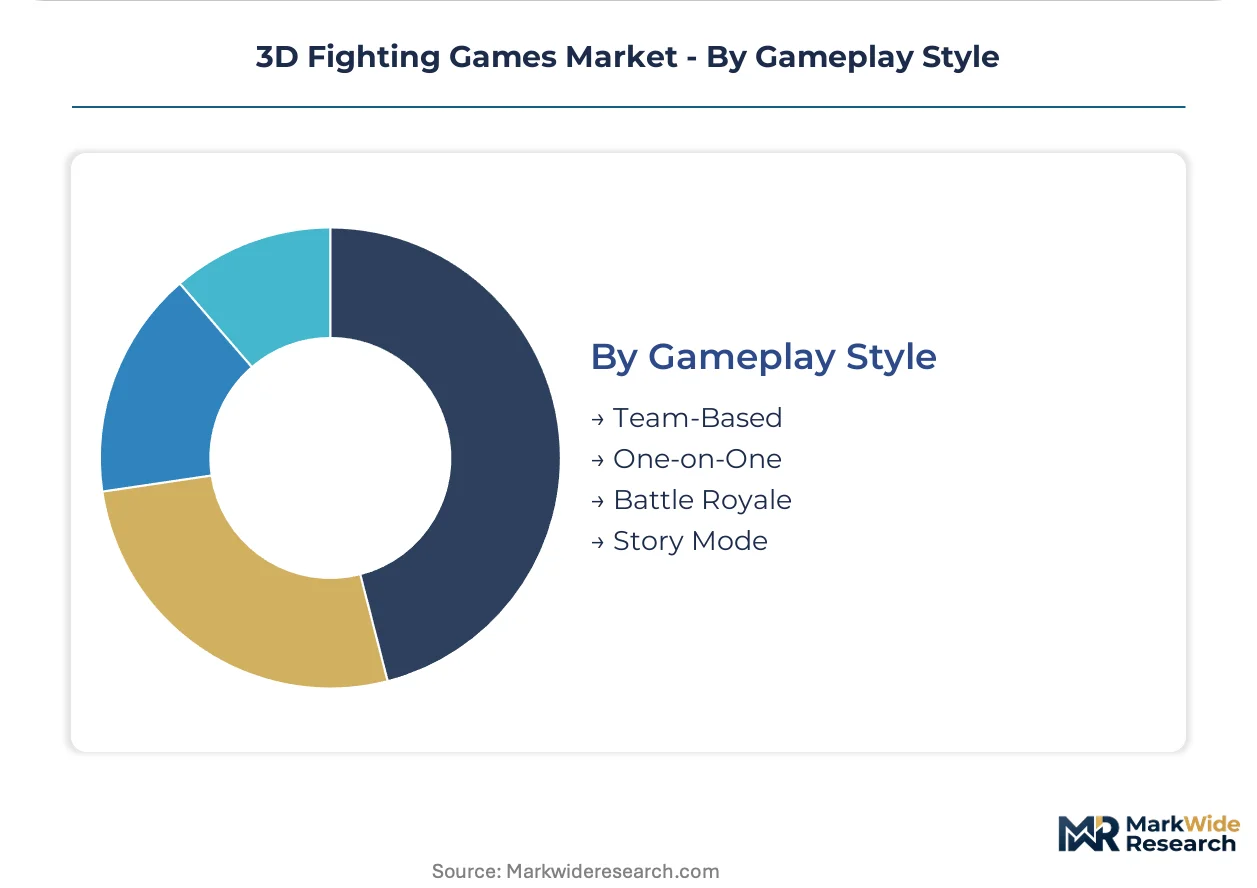
Format architecture determines netcode engineering complexity and spectator engagement potential. Team-based and battle royale configurations strain latency compensation systems, while one-on-one formats prioritize frame data precision over player count scaling.
- One-on-One:Frame-precise input detection systems enable deterministic combo execution standards essential for tournament viability. Capcom's RE Engine sustains visual fidelity across story mode and competitive releases in this format.
- Story Mode:Cinematic narrative integration demands motion capture and voice acting pipelines that differentiate NetherRealm Studios releases. Single-player content extends player lifetime value between competitive seasons.
- Team-Based:Character switching mechanics multiply netcode state synchronization overhead.
- Battle Royale:Large player counts per session prioritize server infrastructure over input precision.
Tournament standard: One-on-One. Climbing the fastest: Story Mode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's arcade-to-console ecosystem concentrates premium monetization pools for 3D fighting game publishers. China's MIIT approval timelines now determine synchronized global release windows. The United States anchors esports broadcasting rights valuation through streaming platform exclusivity contracts.
Japan
Tokyo's dedicated cabinet manufacturing cluster supplies frame-precise hardware to domestic arcades. CERO rating board scrutiny shapes violence depiction thresholds for cabinet releases. Osaka-based Bandai Namco Entertainment anchors tournament circuit presence through Tekken franchise installations.
China
Shanghai's game development studios front-load localization resources for MIIT approval alignment. Streamlined import title review timelines compress marketing spend allocation sequencing. Guangzhou's domestic arcade sector shows particular concentration for fantasy anime aesthetic titles.
United States
Los Angeles-based esports leagues secure exclusive tournament distribution agreements from streaming platforms. ESRB rating standards govern age-gating mechanics for competitive broadcast licensing. Seattle's cloud gaming infrastructure investments enable browser-based competitive play expansion.
South Korea
Seoul's location-based entertainment venues deploy haptic-feedback fighting pods commanding premium per-session pricing. MFDS data handling protocols influence regional server architecture compliance requirements. Busan's VR arcade installations represent the fastest-growing addressable base for immersive hardware differentiation.
3D Fighting Games Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent platform ecosystems and alternative monetization models. The vendor base stratifies across engine-technology owners, licensed-property holders, and specialized fighting-game studios. Three archetypes dominate: proprietary engine developers leveraging visual fidelity differentiation; franchise-anchored publishers monetizing tournament circuit presence; and cinematic-narrative specialists integrating story mode content. Competitive moves concentrate on rollback netcode implementation licensing and cross-platform certification parity engineering.
Within the proprietary engine tier, Capcom and Bandai Namco Entertainment exemplify technology-anchored positioning. Capcom occupies a position as a RE Engine developer sustaining visual fidelity across competitive and story mode releases. Bandai Namco Entertainment anchors tournament circuit presence through the Tekken franchise's enduring competitive infrastructure. NetherRealm Studios sits within the cinematic-narrative archetype, differentiating via integrated story mode content within one-on-one competitive formats.
| Leading Market Players |
|---|
| Project Soul |
| Sega |
| Capcom |
| Nintendo |
| WB Games |
| Bandai Namco Entertainment |
| Arc System Works |
| Atari |
| NetherRealm Studios |
| Others |
Pricing and Supply Chain Analysis
China's MIIT content approval acceleration gates qualified supply access and premium-tier pricing power for publishers targeting synchronized global release windows. Publishers without pre-approved localization pipelines face compressed monetization windows while compliant competitors capture first-mover pricing premiums in China's domestic arcade sector.
Pricing Analysis
The volume-versus-margin split separates mass-market console installations from premium VR arcade deployments and location-based entertainment venues. Three-tier pricing structure across premium, standard, and economy levels differentiates by platform certification tier and netcode implementation quality. Pricing pressure stems from rollback netcode development cost inflation as studios compete for scarce systems programming talent. Mobile and casual crossover segments exhibit highest price sensitivity, while tournament-licensed competitive releases command lowest elasticity.
Supply Chain Analysis
Systems programming talent scarcity in Japan, South Korea, and the United States constrains netcode engineering pipeline capacity for frame-precise latency compensation. Component sourcing draws from Taiwan's semiconductor foundries for GPU silicon, Japan's dedicated cabinet fabricators for arcade hardware, and China's display panel manufacturers for VR installations. Single-source vulnerability concentrates in Japan's three-domestic-fabricator arcade cabinet manufacturing base. Distribution runs through platform holder digital storefronts and streaming platform exclusivity contracts for esports broadcasting rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Netcode engineering talent scarcity props pricing power for studios with captive systems programming capability, creating durable supply constraints that favor incumbents with established recruitment pipelines.
For Market Incumbents: To counter mid-tier studios licensing open-source rollback frameworks, Capcom and Bandai Namco Entertainment should deepen in-house netcode engineering capacity through specialized compensation structures and exclusive tournament circuit licensing. Certification investment in China's MIIT pre-approval pipeline secures synchronized global release windows that compress competitor monetization timing. For New Entrants and Emerging Players: Enter via South Korea's VR arcade installation segment, where haptic-feedback fighting pods command premium per-session pricing with limited incumbent saturation. Cloud gaming infrastructure partnerships with Microsoft Azure or Amazon AWS enable browser-based competitive play expansion into hardware-constrained emerging markets without proprietary engine development. For Investors and Strategic Acquirers: Bandai Namco Entertainment's Tekken World Tour exclusivity renewal is the leading indicator that tournament circuit licensing value is concentrating toward franchise-anchored publishers with proven competitive infrastructure. Acquisition targets should screen for studios with MIIT pre-approval status and rollback netcode implementation capability across the five-to-ten-year viability window.| Strategic Initiative | Industry Significance |
|---|---|
| Rollback Netcode Licensing | Open-source framework adoption compresses competitive viability thresholds for mid-tier releases. |
| MIIT Pre-Approval Pipeline Investment | Front-loaded localization resources align marketing spend with China's import title review windows. |
| VR Arcade Hardware Partnership | Haptic-feedback pod deployments in South Korean LBE venues capture premium per-session pricing. |
| Cross-Platform Certification Parity | Redundant QA cycles across Sony, Microsoft, and Nintendo specifications inflate launch costs. |
| Esports Broadcasting Exclusivity | Amazon Twitch and Google YouTube contracts fragment viewership distribution models. |
Research Methodology
Independent corroboration across game development executives, netcode engineering leads, platform certification officers, and esports league operators underwrites the qualitative findings. Secondary validation draws from Steam hardware survey data, platform holder certification documentation, MIIT import title approval registries, and tournament circuit licensing disclosures. Bottom-up publisher revenue modeling and top-down addressable market sizing triangulate volume estimates.
Rate-of-change decomposition across game type, platform, character design, and gameplay style segments drives the analytical framework. CAGRs derive from installed base projections, seasonal content pass attach rates, and cosmetic microtransaction velocity assumptions. Netcode infrastructure investment cycles and MIIT approval timeline distributions inform segment-specific growth trajectories across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT approval backlog recurrence or netcode engineering talent pipeline collapse. Material deviation in rollback netcode standardization timing or streaming platform exclusivity fragmentation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Fishing Rods Market
Sports & Fitness
India Sports Team and Clubs Market
Sports & Fitness
Skating Shoes Market
Sports & Fitness
Gym Fitness Accessories Market
Sports & Fitness
United States Sports Nutrition Market
Sports & Fitness
Hydration Belt Market
Sports & Fitness
United States Wearable Sensors Market
Sports & Fitness
Licensed Sports Merchandise Market
Sports & Fitness
Latin America Fitness Ring Market
Sports & Fitness
Europe Fitness Equipment Market
Sports & Fitness
Fitness Tracker Market
Sports & Fitness
Leisure Centers Market
Sports & Fitness
Global Shooting Games Market
Sports & Fitness
Performance and Goal Management Market
Sports & Fitness
China Gym Accessories Market
Sports & Fitness
Global Sports Management Software Market